- Market Value (2025): USD 6.7 Bn
- Estimated Value (2026): USD 7.1 Bn
- Forecast Value (2036): USD 13.3 Bn
- CAGR (2026-2036): 6.5%
What is the Brain Monitoring Devices Market forecast to be worth by 2036?
USD 13.3 billion by 2036 at a 6.5% CAGR.
- The Brain Monitoring Devices Market reached USD 6.7 billion in 2025.
- Demand is projected to increase from USD 7.1 billion in 2026 to USD 13.3 billion by 2036.
- The market is forecast to expand at a CAGR of 6.5% from 2026 to 2036.
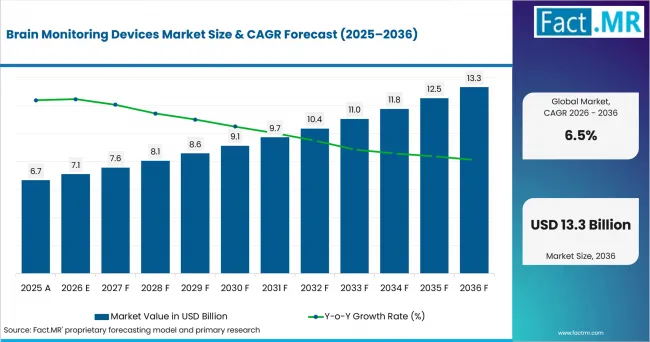
Brain Monitoring Devices Market Value Analysis | Source: Fact.MR
What are the defining numbers behind Brain Monitoring Devices Market growth?
An absolute opportunity of USD 6.2 billion is expected between 2026 and 2036.
- Demand Drivers in the Market
- Neurological care demand is broadening. The World Health Organization's 2025 Global status report on neurology states that neurological conditions affect more than one in three people worldwide, keeping diagnostic and monitoring capacity under sustained pressure.
- EEG remains embedded in seizure diagnosis. NICE recommends routine EEG when epilepsy is suspected after clinical assessment and advises that an EEG requested after a first seizure should ideally be performed within 72 hours.
- Neurocritical care supports intracranial pressure monitoring. Brain Trauma Foundation guidance recommends management of severe TBI using information from ICP monitoring to reduce early mortality, which sustains demand for reliable pressure-monitoring systems in intensive care.
- Device capability is moving toward faster deployment and assisted review. FDA classifications cover full-montage EEG, automated event-detection software and brain-injury EEG assessment aids, while current commercial platforms add wireless acquisition, remote review and AI-supported prioritization.
- Key Segments Analyzed
- Traumatic Brain Injuries lead the Disease segment with 36.8% share in 2026 as acute injury can require repeated assessment of brain pressure, electrical activity or oxygenation during emergency and intensive care.
- Devices account for 65.4% of Product demand in 2026 as EEG systems, intracranial pressure monitors and cerebral oximeters carry the main hardware value in a monitoring installation.
- Hospitals hold 33.7% of End Use demand in 2026 since emergency departments, intensive care units and inpatient neurology services manage the cases that need continuous or higher-acuity brain monitoring.
- Neurological Disorder Diagnosis represents 63.8% of Application demand in 2026 as EEG and related neurodiagnostic systems support epilepsy assessment, stroke-related evaluation and other clinical investigations.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant, Fact.MR says, "Brain monitoring purchases are increasingly shaped by workflow speed and interpretability. Hospitals still need high-fidelity systems for epilepsy units and neurocritical care, but they also want monitoring that can reach the emergency department or bedside without a long setup."
- Strategic Implications
- Prioritize portable EEG configurations that can move between routine neurology, emergency and intensive-care workflows without sacrificing signal integrity.
- Pair hardware development with interpretation software that highlights clinically relevant events while keeping final review with qualified clinicians.
- Build service coverage around uptime, electrode availability and rapid replacement because monitoring interruptions directly affect clinical workflow.
- Develop neurocritical-care packages that combine pressure, oxygenation or EEG information where hospitals prefer a more integrated brain-monitoring view.
- Support public and teaching hospitals with scalable configurations that allow a basic installation to expand into long-term monitoring as case volume grows.
How does the Brain Monitoring Devices Market break down by segment?
The Brain Monitoring Devices Market is analyzed by Disease, Product, End Use and Application, with country growth assessed separately.
Why do Traumatic Brain Injuries lead Disease?
Traumatic Brain Injuries are projected to account for 36.8% share in 2026.
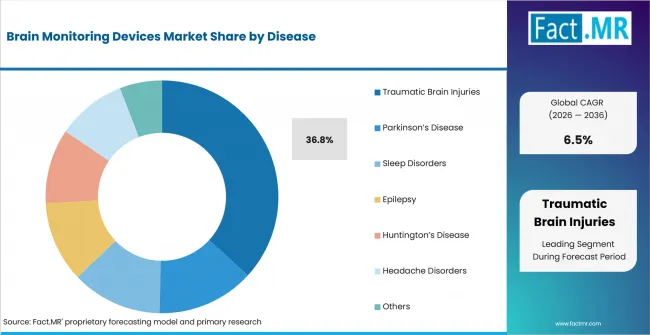
Brain Monitoring Devices Market Analysis By Disease | Source: Fact.MR
TBI monitoring spans a wide acuity range. Mild cases may require rapid neurological assessment, while severe cases can require continuous intracranial pressure measurement or multimodal monitoring in intensive care. This concentrates device spending around hospitals that manage trauma and neurosurgical emergencies.
Brain Trauma Foundation guidance gives ICP monitoring a defined role in the management of severe TBI. FDA also maintains a device classification for brain-injury adjunctive interpretive EEG assessment aids, which shows that electrical brain activity can be used as an assessment input alongside standard clinical methods.
TBI monitoring also overlaps with functional brain imaging when clinicians need structural or functional context beyond continuous bedside signals.
Why do Devices lead Product?
Devices are projected to account for 65.4% share in 2026.
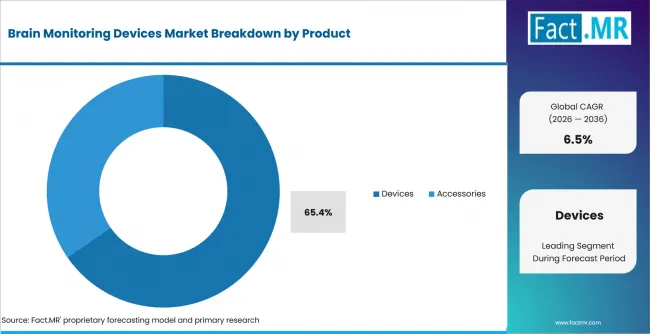
Brain Monitoring Devices Market Analysis By Product | Source: Fact.MR
The core value sits in acquisition and monitoring hardware. Electroencephalography devices capture electrical activity, intracranial pressure monitors support neurocritical care and cerebral oximeters add regional oxygenation information. Accessories such as electrodes and sensors are recurring purchases, but they depend on the installed device platform.
FDA's current full-montage electroencephalograph classification defines systems that acquire, display, store and archive signals from 16 or more electrodes. A separate FDA classification covers automated event-detection software for full-montage EEG, which is increasing the software content attached to hardware purchases without removing the need for the underlying recording system.
Why do Hospitals lead End Use?
Hospitals are projected to account for 33.7% share in 2026.
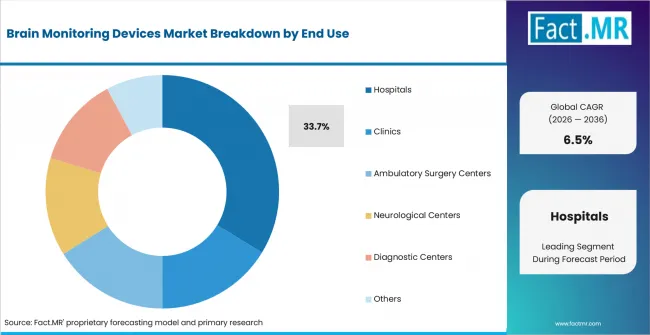
Brain Monitoring Devices Market Analysis By End Use | Source: Fact.MR
Hospitals combine several demand pathways in one site. Emergency departments receive acute head injuries, intensive care units manage patients who may need continuous monitoring and neurology services perform routine or long-term EEG. Teaching hospitals can also support intracranial monitoring or research protocols.
The hospital lead is reinforced by the need for specialist interpretation and device servicing. Point-of-care systems can distribute recording closer to the patient, but the clinical governance and escalation pathway usually remain anchored in a hospital neurology or critical-care team.
Why does Neurological Disorder Diagnosis lead Application?
Neurological Disorder Diagnosis is projected to account for 63.8% share in 2026.
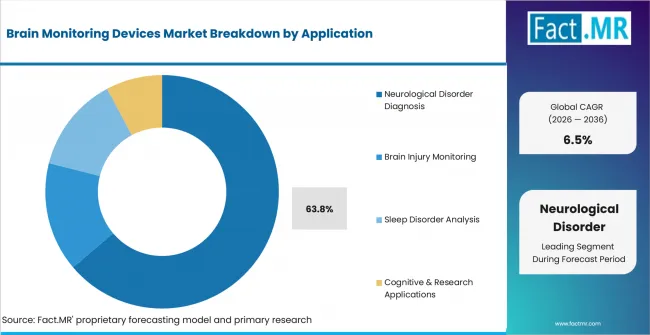
Brain Monitoring Devices Market Analysis By Application | Source: Fact.MR
Diagnosis generates repeat demand because EEG is used to investigate suspected seizure activity and can be extended to sleep-deprived or ambulatory recording when routine testing does not resolve uncertainty. NINDS also describes EEG as a tool for seizure disorders, sleep disorders and monitoring brain activity under anesthesia.
NICE guidance supports a stepped EEG pathway after a suspected seizure. Routine EEG can be followed by sleep-deprived EEG and then ambulatory EEG when diagnostic uncertainty persists. That progression supports demand for systems that can cover short examinations and longer monitoring without fragmenting patient data.
Sleep-related neurological assessment also connects with the sleeping aids market where diagnostic and monitoring tools sit alongside therapeutic products.
What is accelerating Brain Monitoring Devices Market adoption, and what is holding it back?
Adoption is being pulled by neurological case volume, defined EEG pathways and the need for continuous information in critical care. Growth is restrained by specialist workforce limits, equipment cost and the need to validate signal quality across different care environments.
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Neurological diagnosis and epilepsy testing demand | +1.4% | Global | Short term (≤ 2 years) |
| TBI and neurocritical-care monitoring | +1.2% | USA, Germany and Brazil | Short term (≤ 2 years) |
| Portable and point-of-care EEG deployment | +1.0% | USA, U.K. and Japan | Medium term (2-4 years) |
| Aging-related neurological case load | +0.8% | Germany and Japan | Long term (≥ 4 years) |
Opportunity Impact Analysis
| Opportunity | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Ambulatory and remote EEG workflows | +0.9% | USA, U.K. and Germany | Medium term (2-4 years) |
| AI-assisted EEG review and event detection | +0.8% | USA and Japan | Medium term (2-4 years) |
| Multimodal brain monitoring in OR and ICU | +0.7% | Global | Medium term (2-4 years) |
| Public neurodiagnostic capacity expansion | +0.5% | Brazil and underserved markets | Long term (≥ 4 years) |
Restraints Impact Analysis
| Restraint | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Specialist interpretation and neurophysiology workforce gaps | -0.8% | Global | Short term (≤ 2 years) |
| Capital and service burden for advanced systems | -0.7% | Brazil and cost-sensitive markets | Medium term (2-4 years) |
| Device validation and regulatory requirements | -0.5% | USA, U.K. and Japan | Medium term (2-4 years) |
| Signal quality and workflow complexity | -0.4% | Global | Long term (≥ 4 years) |
Which countries are scaling the Brain Monitoring Devices Market through 2036?
- Germany: Germany's 7.2% CAGR is supported by an aging population and established hospital neurology infrastructure. Destatis reported that people aged 60 and above represented 31% of the population at the end of 2025, which increases the care base for age-linked neurological conditions.
- Brazil: Brazil's 6.5% CAGR is supported by public-sector epilepsy pathways and expansion of EEG access through university hospitals. The Ministry of Health updated its national epilepsy clinical protocol in May 2026, while EBSERH hospitals continue to provide routine and specialized EEG services.
- USA: The USA is projected at a 5.9% CAGR as TBI care and broader neurodiagnostic demand sustain device utilization. CDC continues to report a substantial TBI burden, and FDA cleared the Pressio 3 multi-parameter neuromonitoring system in April 2026.
- U.K.: The U.K. is projected at a 5.3% CAGR as NICE guidance embeds EEG into the diagnostic pathway after a suspected seizure and supports sleep-deprived or ambulatory EEG when routine testing is inconclusive.
- Japan: Japan's 4.7% CAGR reflects a large older population and an established regulated EEG market. Japan's Statistics Bureau reported about 36.2 million people aged 65 and above in March 2026, while PMDA classifies EEG systems as Class II medical devices.
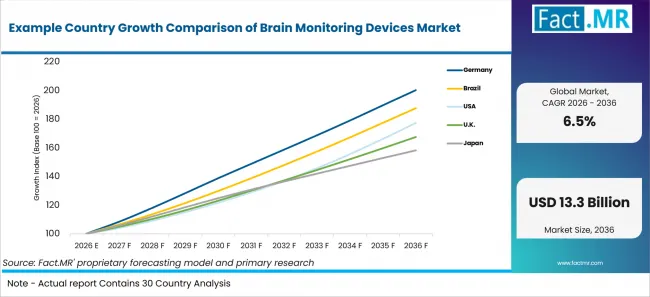
Example Country Growth Comparison Of Brain Monitoring Devices Market | Source: Fact.MR
Country CAGR (2026-2036)
| Country | CAGR (2026-2036) |
|---|---|
| Germany | 7.2% |
| Brazil | 6.5% |
| USA | 5.9% |
| U.K. | 5.3% |
| Japan | 4.7% |
What is driving Germany's growth through 2036?
Germany is projected to register a CAGR of 7.2% from 2026 to 2036.
The country's age structure raises the number of patients who may enter neurological pathways for stroke, Parkinson's disease or cognitive decline. Destatis reported that the share of people aged 60 and above reached 31% at the end of 2025.
For suppliers, the opportunity is concentrated in hospitals and specialist diagnostic settings that can support trained staff, maintenance and long-term data workflows. Replacement demand also favors platforms that combine routine EEG with higher-acuity monitoring or networked review.
What is driving Brazil's growth through 2036?
Brazil is projected to register a CAGR of 6.5% from 2026 to 2036.
Public neurology pathways are supporting a wider diagnostic base. Brazil's Ministry of Health updated the Clinical Protocol and Therapeutic Guidelines for Epilepsy in May 2026. EBSERH hospital materials also document routine EEG, sleep recording and specialized epilepsy services within the federal university hospital network.
The main commercial constraint is uneven access to neurophysiology expertise and advanced equipment. Suppliers that can support service coverage and scalable EEG configurations can address public hospitals that need reliable diagnostics without the cost structure of a full epilepsy-monitoring unit.
What is driving USA's growth through 2036?
The USA is projected to register a CAGR of 5.9% from 2026 to 2036.
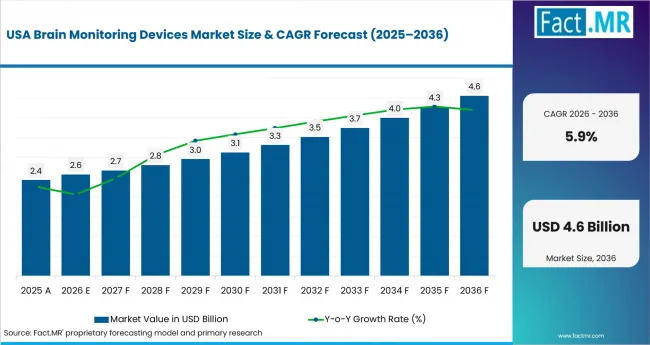
Brain Monitoring Devices Market Country Value Analysis | Source: Fact.MR
TBI and critical-care monitoring remain durable demand sources. CDC reports 68,663 TBI-related deaths in 2023 and about 214,110 TBI-related hospitalizations in 2020. FDA activity also shows ongoing product development, including the April 2026 clearance of the Pressio 3 Multi-parameter Neuromonitoring System for intracranial pressure monitoring.
The market is also moving toward quicker EEG deployment. Current point-of-care systems can be set up in emergency or intensive-care settings and can support remote neurological review. This lowers the operational barrier when a full EEG team is not immediately available.
What is driving U.K.'s growth through 2036?
The U.K. is projected to register a CAGR of 5.3% from 2026 to 2036.
NICE gives EEG a clear role after a suspected epileptic seizure and recommends performing a requested EEG as soon as possible, ideally within 72 hours after the first seizure. The pathway also allows sleep-deprived EEG and ambulatory EEG where uncertainty remains.
This creates demand across routine laboratories and longer-duration recording. Procurement therefore depends on systems that can move from short diagnostic studies to ambulatory or video-supported monitoring while maintaining consistent review and reporting.
What is driving Japan's growth through 2036?
Japan is projected to register a CAGR of 4.7% from 2026 to 2036.
Population aging keeps neurological diagnosis relevant. Japan's Statistics Bureau reported about 36.2 million people aged 65 and above in March 2026. PMDA classifies electroencephalographs as Class II devices and maintains standards for EEG systems and related software.
Local clinical use spans routine EEG, epilepsy monitoring and higher-channel systems. Product demand therefore favors established service capability, stable signal acquisition and software that supports rapid review across hospital neurology and emergency settings.
Portable and remote monitoring also intersects with wearable computing devices as healthcare systems evaluate smaller sensors and connected data workflows.
Who Leads the Brain Monitoring Devices Market?
Key players in the Brain Monitoring Devices Market include Medtronic, Advanced Brain Monitoring, B. Braun Medical, BD, Cadwell Industries Inc., CAS Medical Systems Inc., Compumedics Limited, DePuy Synthes Companies, Electrical Geodesics Inc., Elekta AB, EMOTIV Inc., General Electric, Integra LifeSciences Corporation, Koninklijke Philips N.V., Masimo Corporation, Natus Medical Incorporated, NIHON KOHDEN CORPORATION, Rimed Inc., Siemens Healthcare Private Limited and Yokogawa Electric Corporation.
Competition is shaped by clinical coverage and installed workflow. Natus supports routine EEG, ambulatory EEG, long-term monitoring and ICU use. Nihon Kohden offers Neurofax platforms for routine and higher-acuity EEG. Cadwell combines EEG with neurodiagnostic and sleep solutions, while Compumedics provides clinical and research EEG amplifiers.
Cerebral oxygenation creates a second competitive route. Masimo combines SedLine brain-function monitoring with O3 regional oximetry on its Root platform. Consolidation also affects how older company names appear in the market: Edwards Lifesciences acquired CAS Medical Systems in 2019, and Philips acquired Electrical Geodesics in 2017. General Electric's healthcare business became the independent GE HealthCare company in 2023.
Which companies are the key providers?
The key companies covered are Medtronic; Advanced Brain Monitoring; B. Braun Medical; BD; Cadwell Industries Inc.; CAS Medical Systems Inc.; Compumedics Limited; DePuy Synthes Companies; Electrical Geodesics Inc.; Elekta AB; EMOTIV Inc.; General Electric; Integra LifeSciences Corporation; Koninklijke Philips N.V.; Masimo Corporation; Natus Medical Incorporated; NIHON KOHDEN CORPORATION; Rimed Inc.; Siemens Healthcare Private Limited; and Yokogawa Electric Corporation.
- Medtronic
- Advanced Brain Monitoring
- B. Braun Medical
- BD
- Cadwell Industries Inc.
- CAS Medical Systems Inc.
- Compumedics Limited
- DePuy Synthes Companies
- Electrical Geodesics Inc.
- Elekta AB
- EMOTIV Inc.
- General Electric
- Integra LifeSciences Corporation
- Koninklijke Philips N.V.
- Masimo Corporation
- Natus Medical Incorporated
- NIHON KOHDEN CORPORATION
- Rimed Inc.
- Siemens Healthcare Private Limited
- Yokogawa Electric Corporation
Bibliography
- World Health Organization. (2025). Global status report on neurology. World Health Organization.
- Centers for Disease Control and Prevention. (2026). TBI Data. U.S. Department of Health and Human Services.
- U.S. Food and Drug Administration. (2026). Product Classification: Full-montage standard electroencephalograph. U.S. Department of Health and Human Services.
- U.S. Food and Drug Administration. (2026). Product Classification: Automatic event detection software for full-montage electroencephalograph. U.S. Department of Health and Human Services.
- U.S. Food and Drug Administration. (2026). Product Classification: Brain injury adjunctive interpretive electroencephalograph assessment aid. U.S. Department of Health and Human Services.
- U.S. Food and Drug Administration. (2026). 510(k) Premarket Notification K252241: Pressio 3 Multi-parameter Neuromonitoring System. U.S. Department of Health and Human Services.
- National Institute for Health and Care Excellence. (2022, updated 2025). Epilepsies in children, young people and adults: Diagnosis and assessment, NG217. NICE.
- National Institute of Neurological Disorders and Stroke. (2025). Neurological Diagnostic Tests and Procedures. National Institutes of Health.
- Brain Trauma Foundation. (2016). Guidelines for the Management of Severe Traumatic Brain Injury, Fourth Edition. Brain Trauma Foundation.
- American Clinical Neurophysiology Society. (2025). Guidelines and Consensus Statements. American Clinical Neurophysiology Society.
- Statistisches Bundesamt. (2026). Population by Age Groups, 2011 to 2025. Federal Statistical Office of Germany.
- Ministério da Saúde. (2026). Protocolo Clínico e Diretrizes Terapêuticas da Epilepsia. Government of Brazil.
- Empresa Brasileira de Serviços Hospitalares. (2026). Eletroencefalograma. Government of Brazil.
- Statistics Bureau of Japan. (2026). Population Estimates, March 2026 final and August 2026 provisional values. Government of Japan.
- Pharmaceuticals and Medical Devices Agency. (2026). JMDN Classification: Electroencephalograph. Government of Japan.
- Natus Medical Incorporated. (2026). Electroencephalography EEG and aEEG Solutions. Natus Medical.
- Nihon Kohden Corporation. (2026). Neurofax Electroencephalograph Solutions. Nihon Kohden.
- Cadwell Industries Inc. (2026). Neurology Solutions for Neurodiagnostic and Neuromonitoring. Cadwell Industries.
- Compumedics Neuroscan. (2026). EEG Systems and Grael Amplifier Range. Compumedics.
- Masimo Corporation. (2026). Brain Monitoring: SedLine and O3 Regional Oximetry. Masimo.
- Edwards Lifesciences Corporation. (2019). Edwards Lifesciences Completes Acquisition of CASMED. Edwards Lifesciences.
- Royal Philips. (2017). Philips Acquires Electrical Geodesics. Royal Philips.
- GE HealthCare Technologies Inc. (2023). GE HealthCare Completes Spin-Off and Begins Trading on Nasdaq. GE HealthCare.
- Yokogawa Electric Corporationtric Corporation. (2026). MEGvision Magnetoencephalograph System and Its Applications. Yokogawa Electric Corporationtric.
This Report Answers
- What is the Brain Monitoring Devices Market value in 2026 and what value is forecast for 2036?
- Why do Traumatic Brain Injuries hold the leading Disease share in 2026?
- Why do Devices account for the leading Product share?
- Why are Hospitals the leading End Use setting?
- Why does Neurological Disorder Diagnosis account for most Application demand?
- How do EEG pathways, TBI care and neurocritical monitoring affect demand?
- How do country growth rates differ across Germany, Brazil, USA, U.K. and Japan?
- Which companies are active across EEG, cerebral oximetry and broader brain monitoring?
- What limits wider adoption of advanced brain monitoring systems?
- What should hospital buyers evaluate before expanding from routine EEG into ambulatory, ICU or long-term monitoring?
What does the Brain Monitoring Devices Market cover?
The Brain Monitoring Devices Market covers commercial revenue from devices and accessories used to acquire or monitor brain-related physiological signals within the defined Disease, Product, End Use and Application categories. Revenue includes EEG devices, intracranial pressure monitors, cerebral oximeters, electrodes, sensors and data-management accessories when sold for the defined monitoring use.
The market includes hospital and clinic deployments, ambulatory surgery settings, neurological centers, diagnostic centers, rehabilitation or home-care settings where this taxonomy applies, and academic or research use tied to brain monitoring.
What is included in the scope?
Included products are Electroencephalography Devices, Intracranial Pressure Monitors and Cerebral Oximeters, along with Electrodes, Sensors and Data Management Accessories. Disease coverage includes Traumatic Brain Injuries, Parkinson's Disease, Sleep Disorders, Epilepsy, Huntington's Disease, Headache Disorders and Other neurological uses.
Application coverage includes Neurological Disorder Diagnosis, Brain Injury Monitoring, Sleep Disorder Analysis and Cognitive & Research Applications. End-use coverage follows hospital, clinic, ambulatory, neurological, diagnostic and other institutional settings.
What is excluded from the scope?
The scope excludes stand-alone MRI, CT, PET and other full neuroimaging systems when their revenue is not part of the defined monitoring-device categories. It also excludes therapeutic neurostimulation hardware, general patient monitors without a brain-monitoring function and consumer wellness products that do not fit the clinical or research applications listed in the taxonomy.
Software sold independently from an eligible monitoring workflow is excluded unless it functions as a data-management accessory attached to the covered device system. General sleep therapy equipment is outside scope unless the product is used for the specified brain-monitoring application.
How Was the Analysis Built?
The analysis uses a hybrid top-down and bottom-up framework anchored to device revenue, installed clinical workflows and the defined segment structure.
- Primary Research: The research framework focuses on neurologists, clinical neurophysiology teams, neurocritical-care staff, hospital procurement teams, distributors and device suppliers. Discussions test workflow requirements, replacement behavior, service needs and the role of consumables.
- Desk Research: Desk research uses regulator databases, clinical guidance, public health statistics, standards, company product literature and corporate disclosures relevant to EEG, intracranial pressure monitoring and cerebral oximetry.
- Market Sizing and Forecasting: Sizing combines installed equipment, replacement cycles, procedure and patient demand, accessory pull-through, average selling prices and country-specific healthcare capacity. Forecast assumptions are checked against disease pathways and regulatory requirements.
- Data Validation and Update Cycle: Market assumptions are checked against current device classifications, clinical guidance, company portfolio changes and country health-system developments. Corporate consolidation is reviewed so that legacy names do not distort the interpretation of competition.
What is the report's scope and coverage?
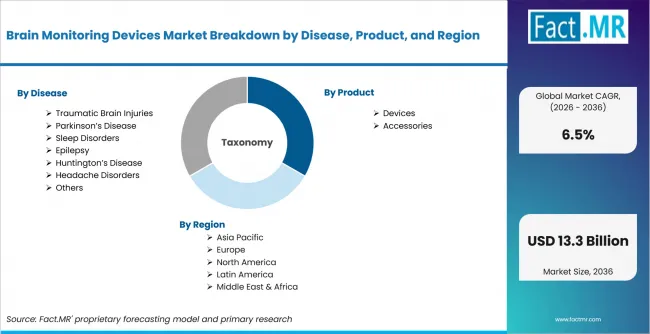
Brain Monitoring Devices Market Breakdown By Disease, Product, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Brain-monitoring devices and accessories used to record or monitor electrical activity, intracranial pressure or cerebral oxygenation within the defined clinical and research applications |
| Segments Covered | Disease; Product; End Use; Application |
| Geographic Coverage | Global market with detailed country CAGR analysis for Germany, Brazil, USA, U.K. and Japan |
| Countries Covered | Germany; Brazil; USA; U.K.; Japan |
| Key Companies Profiled | Medtronic; Advanced Brain Monitoring; B. Braun Medical; BD; Cadwell Industries Inc.; CAS Medical Systems Inc.; Compumedics Limited; DePuy Synthes Companies; Electrical Geodesics Inc.; Elekta AB; EMOTIV Inc.; General Electric; Integra LifeSciences Corporation; Koninklijke Philips N.V.; Masimo Corporation; Natus Medical Incorporated; NIHON KOHDEN CORPORATION; Rimed Inc.; Siemens Healthcare Private Limited; Yokogawa Electric Corporation. |
| Forecast Period | 2026 to 2036 |
| Base Year | 2025 |
| Market Value, 2026 | USD 7.1 billion |
| Market Value, 2036 | USD 13.3 billion |
| CAGR, 2026-2036 | 6.5% |
| Absolute Opportunity | USD 6.2 billion |
| Approach | Hybrid top-down and bottom-up approach using device installed base, replacement cycles, clinical demand, accessory pull-through, pricing and country healthcare capacity |
How is the market segmented?
-
By Disease:
- Traumatic Brain Injuries
- Mild Traumatic Brain Injuries
- Moderate Traumatic Brain Injuries
- Severe Traumatic Brain Injuries
- Parkinson's Disease
- Motor Symptom Monitoring
- Deep Brain Stimulation Monitoring
- Disease Progression Monitoring
- Sleep Disorders
- Sleep Apnea Monitoring
- Insomnia Monitoring
- Neurological Sleep Studies
- Epilepsy
- Seizure Detection
- Pre Surgical Monitoring
- Post Treatment Monitoring
- Huntington's Disease
- Cognitive Monitoring
- Motor Function Monitoring
- Disease Progression Analysis
- Headache Disorders
- Migraine Monitoring
- Tension Headache Monitoring
- Neurological Assessment
- Others
- Neurodegenerative Disorders
- Stroke Monitoring
- Brain Infection Monitoring
- Traumatic Brain Injuries
-
By Product:
- Devices
- Electroencephalography Devices
- Intracranial Pressure Monitors
- Cerebral Oximeters
- Accessories
- Electrodes
- Sensors
- Data Management Accessories
- Devices
-
By End Use:
- Hospitals
- General Hospitals
- Specialty Hospitals
- Teaching Hospitals
- Clinics
- Neurology Clinics
- Specialty Clinics
- Private Clinics
- Ambulatory Surgery Centers
- Outpatient Surgical Centers
- Neurological Surgery Centers
- Specialized Ambulatory Centers
- Neurological Centers
- Brain Research Centers
- Neurodiagnostic Centers
- Comprehensive Neurology Centers
- Diagnostic Centers
- Imaging and Diagnostic Centers
- Independent Diagnostic Labs
- Specialized Neurodiagnostic Facilities
- Others
- Rehabilitation Centers
- Home Care Settings
- Academic and Research Institutes
- Hospitals
-
By Application:
- Neurological Disorder Diagnosis
- Epilepsy Monitoring Applications
- Stroke Diagnosis Applications
- Brain Injury Monitoring
- Traumatic Brain Injury Care
- Neuro Critical Care Monitoring
- Sleep Disorder Analysis
- Sleep Apnea Monitoring Systems
- Sleep Quality Analysis Systems
- Cognitive & Research Applications
- Neuroscience Research Studies
- Behavioral Neuroscience Research
- Neurological Disorder Diagnosis
-
By Region:
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa