- Market Value (2025): USD 43.2 Bn
- Estimated Value (2026): USD 48.6 Bn
- Forecast Value (2036): USD 156.4 Bn
- CAGR (2026-2036): 12.4%
What is the GLP-1 Market forecast to be worth by 2036?
USD 156.4 billion by 2036 at a 12.4% CAGR.
- The GLP-1 Market reached USD 43.2 billion in 2025.
- Demand is projected to increase from USD 48.6 billion in 2026 to USD 156.4 billion by 2036.
- The market is projected to expand at a 12.4% CAGR from 2026 to 2036.
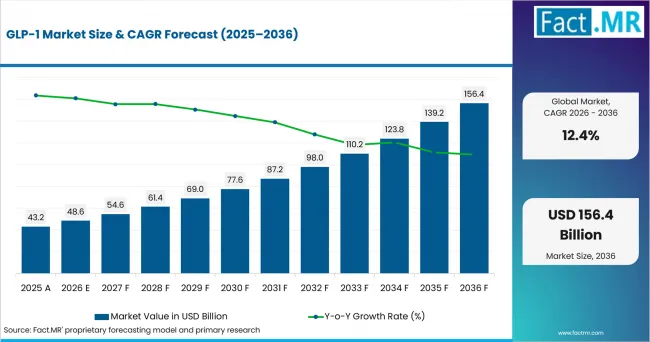
Glp 1 Market Value Analysis | Source: Fact.MR
What are the defining numbers behind GLP-1 Market growth?
An absolute opportunity of USD 107.8 billion is expected between 2026 and 2036.
- Demand Drivers in the Market
- Diabetes prevalence is widening the treatable base for incretin therapies. The International Diabetes Federation reports 589 million adults with diabetes in 2024 and projects 853 million by 2050, with type 2 diabetes accounting for more than 90% of cases. More diagnosed patients, longer treatment duration and more intensive cardiometabolic risk management increase prescribing volume for GLP-1 receptor agonists and related diabetes diagnostics.
- Obesity care is moving from lifestyle-only programmes toward medically supervised chronic treatment. WHO reports 2.5 billion adults with overweight and more than 890 million with obesity in 2022, while FDA approvals for Wegovy and Zepbound show how GLP-1 agonist drugs and dual agonists are being used for weight management and related cardiovascular or sleep-apnea risk. This expands patient entry points beyond glycemic control.
- Additional approved indications are giving physicians more reasons to keep patients on therapy. FDA expanded semaglutide use for cardiovascular-risk reduction and kidney-risk reduction, while Anvisa approved cardiovascular-risk language for Wegovy in Brazil. Broader clinical utility raises the value of continued therapy in patients with diabetes, obesity, cardiovascular disease or chronic kidney disease.
- Prefilled pens and once-weekly injections reduce friction at initiation and refill. EMA lists multiple injectable GLP-1 medicines authorised for diabetes or weight management, and Anvisa's register shows several GLP-1 products sold as injection solutions. This supports the Route Of Administration mix where injectable therapies remain the familiar base of drug delivery.
- Pharmacy channels are becoming more structured as regulators respond to off-label use, counterfeit risk and supply pressure. The UK MHRA stresses licensed use under medical oversight, while Anvisa requires prescription retention for affected GLP-1 medicines in Brazil. Regulated refill workflows support retail pharmacies and create room for adherence platforms around titration, side-effect follow-up and repeat dispensing.
- Key Segments Analyzed
- GLP-1 Receptor Agonists account for 67.8% of Product in 2026, supported by broad physician familiarity, approved use across diabetes and obesity, and established prescribing workflows.
- Injectable Therapies hold 78.5% of Route Of Administration in 2026 because weekly pens and auto injectors are embedded in current GLP-1 prescribing, storage and patient training routines.
- Type 2 Diabetes Management represents 54.3% of Application in 2026 as GLP-1 therapy remains anchored in long-duration glycemic control and cardiometabolic risk management.
- Retail Pharmacies account for 46.7% of Distribution Channel in 2026 because chronic refills, prescription checks and patient counselling sit naturally in pharmacy workflows.
- Hospitals hold 42.8% of End Use in 2026 as high-risk patients often enter therapy through endocrinology, obesity, cardiology and nephrology-linked care pathways.
- Adult Population accounts for 88.1% of Patient Type in 2026 because type 2 diabetes, obesity and cardiometabolic comorbidities are concentrated in adult treatment pathways.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant, Fact.MR, states, "The GLP-1 market is being rebuilt around sustained cardiometabolic treatment rather than short prescription bursts. Demand is strong, but the more durable advantage sits with suppliers that can combine evidence, stable pen supply, physician education, pharmacy controls and patient follow-up through titration. The next phase will be less about awareness and more about reliable, supervised access."
- Strategic Implications
- GLP-1 manufacturers should treat supply reliability, pen availability and cold-chain discipline as commercial differentiators because therapy interruption can push clinicians toward substitutes.
- Dual and multi receptor programmes should prioritize tolerability, cardiovascular outcomes, kidney outcomes and dose-escalation support rather than positioning only on weight-loss response.
- Retail pharmacies and online pharmacies need prescription validation, patient education, storage controls and refill reminders as GLP-1 use moves deeper into chronic therapy.
- Hospitals and specialty clinics should standardize patient selection and side-effect escalation because adoption depends on supervision in adult diabetes, obesity and cardiometabolic care.
- Adjacent players in companion products should avoid generic wellness claims and focus on nutrition, hydration and adherence support that clinicians can recommend.
How does the GLP-1 Market break down by segment?
The market is segmented by Product, Route of Administration, Application, Distribution Channel, End Use and Patient Type.
Why does GLP-1 Receptor Agonists lead Product?
GLP-1 Receptor Agonists are projected to account for a 67.8% share in 2026.
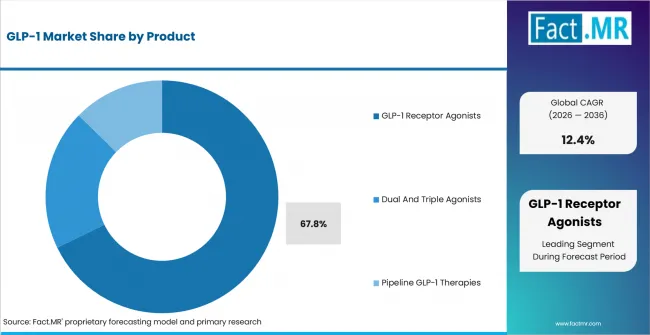
Glp 1 Market Analysis By Product | Source: Fact.MR
GLP-1 receptor agonists lead because they have the deepest prescriber familiarity across type 2 diabetes and obesity care. Semaglutide, liraglutide, dulaglutide, exenatide and lixisenatide variants give clinicians multiple dosing and product-history options, while dual and triple agonists are still expanding from a smaller base.
EMA's medicine list and Anvisa's GLP-1 prescription-control table show broad authorised use across diabetes and weight management products. That installed base makes GLP-1 receptor agonists the first step for many formulary and pharmacy workflows before pipeline therapies can displace established prescribing patterns.
Why does Injectable Therapies lead Route of Administration?
Injectable Therapies are projected to account for a 78.5% share in 2026.
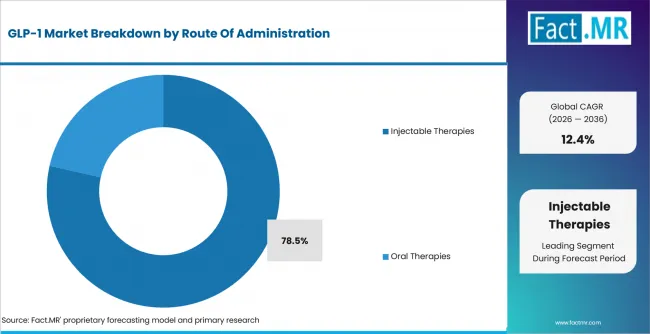
Glp 1 Market Analysis By Route Of Administration | Source: Fact.MR
Injectable therapies lead because the market has been built around once-weekly or titrated subcutaneous products supplied through pens and auto injectors. Patients may prefer oral therapies, but many high-value products still rely on injectable delivery to support dose escalation, adherence routines and clinical monitoring.
Anvisa's 2025 prescription-retention table lists many GLP-1 medicines as solution injections, including products based on liraglutide, semaglutide and tirzepatide. That record reflects why pharmacy storage, patient training and refill management remain tied to injectable workflows.
Why does Type 2 Diabetes Management lead Application?
Type 2 Diabetes Management is projected to account for a 54.3% share in 2026.
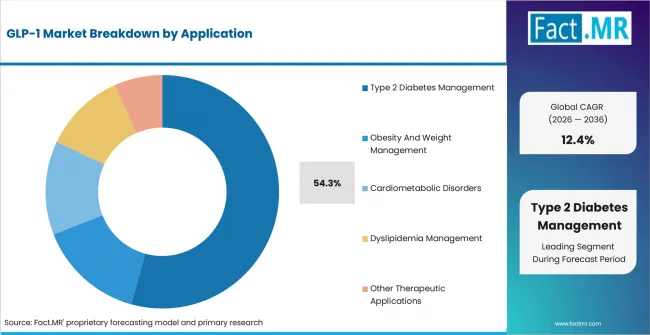
Glp 1 Market Analysis By Application | Source: Fact.MR
Type 2 diabetes management leads because GLP-1 therapy was first normalized through glucose-control pathways before the obesity wave broadened demand. Patients with type 2 diabetes often require long-duration medication and risk-factor management, so prescribers evaluate GLP-1 therapy alongside A1C control, weight, cardiovascular risk and kidney status.
The ADA's 2026 Standards of Care update highlights cardiovascular disease prevention and chronic kidney disease treatment algorithms for people with type 2 diabetes. That reinforces GLP-1 use as part of metabolic-risk management rather than an isolated weight-loss prescription.
Why does Retail Pharmacies lead Distribution Channel?
Retail Pharmacies are projected to account for a 46.7% share in 2026.
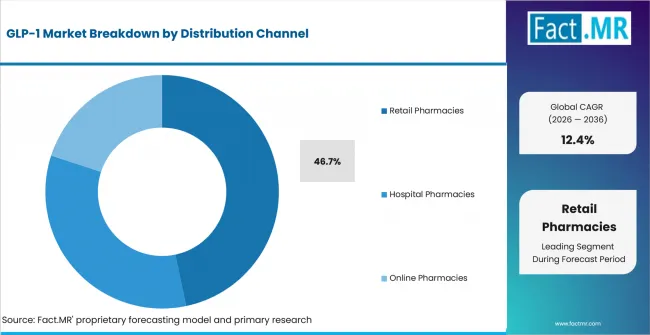
Glp 1 Market Analysis By Distribution Channel | Source: Fact.MR
Retail pharmacies lead because GLP-1 drugs depend on recurring prescriptions, refills, storage discipline and patient counselling. Once therapy is initiated, many patients move into repeat dispensing cycles that pharmacies can support through inventory visibility, prescription checks and patient education.
Regulatory guidance also pushes demand into formal pharmacy channels. The UK MHRA warns that GLP-1 medicines should be used only for licensed medical purposes, and Anvisa requires prescription retention for affected products. These controls make authorized pharmacies more central to access.
Why does Hospitals lead End Use?
Hospitals are projected to account for a 42.8% share in 2026.
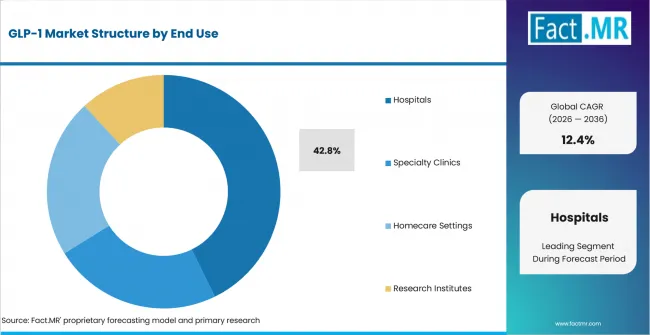
Glp 1 Market Analysis By End Use | Source: Fact.MR
Hospitals lead because complex GLP-1 initiation often intersects with endocrinology, obesity medicine, cardiology, nephrology and surgical-risk management. Patients with diabetes and obesity may need medication selection, titration, gastrointestinal side-effect management and comorbidity review before therapy settles into routine refills.
Expanded indications strengthen this institutional role. FDA approvals connected semaglutide and tirzepatide with cardiovascular, kidney and sleep-apnea outcomes, so hospital-based specialists and formulary teams influence which drugs move into protocols for higher-risk adult patients.
Why does Adult Population lead Patient Type?
Adult Population is projected to account for an 88.1% share in 2026.
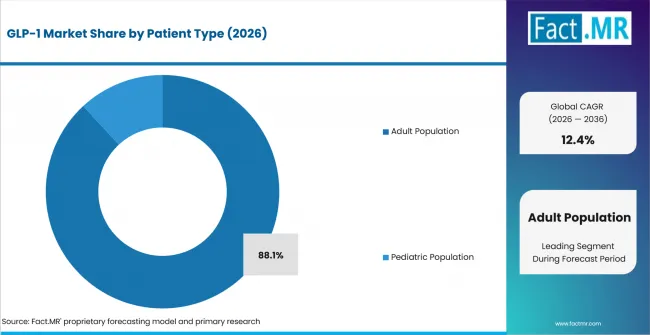
Glp 1 Market Analysis By Patient Type | Source: Fact.MR
Adult population leads because the two central demand pools, type 2 diabetes and obesity, are concentrated in adult care pathways. WHO's adult obesity data and IDF diabetes figures show the scale of adult metabolic disease, while most GLP-1 indications and reimbursement rules are written around adults with diabetes, obesity or related comorbidities.
Adolescent and pediatric indications can grow, but they remain narrower and more tightly controlled. Adult treatment volumes are also reinforced by middle-age and elderly patients who often carry overlapping glycemic, weight, blood-pressure and lipid-management needs.
What is accelerating GLP-1 Market adoption, and what is holding it back?
Rising adult diabetes and obesity burden, approved cardiometabolic indications, injectable-pen familiarity and controlled pharmacy access are increasing adoption. Supply pressure, reimbursement rules, side effects, inappropriate use controls and high out-of-pocket exposure continue to hold back wider use.
Drivers Impact Analysis
| Factor | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising diagnosed type 2 diabetes and obesity burden | +1.9% | Global | Short term (<= 2 years) |
| Cardiovascular, kidney and sleep-apnea indication expansion | +1.5% | USA, Brazil and Europe | Medium term (2-4 years) |
| Injectable pen familiarity and weekly dosing routines | +1.1% | Global | Short term (<= 2 years) |
| Regulated pharmacy refill and counselling workflows | +0.8% | USA, UK and Brazil | Medium term (2-4 years) |
| Physician confidence in established semaglutide and liraglutide use | +0.6% | Germany, Japan and USA | Long term (>= 4 years) |
Opportunity Impact Analysis
| Factor | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Oral and small molecule GLP-1 pipeline progress | +1.3% | USA, Japan and Europe | Long term (>= 4 years) |
| Dual and multi receptor agonists for broader metabolic outcomes | +1.1% | Global | Medium term (2-4 years) |
| Patient support around titration and persistence | +0.9% | USA, UK and Germany | Medium term (2-4 years) |
| Additional regulated semaglutide supply in Brazil | +0.7% | Brazil and Latin America | Short term (<= 2 years) |
Restraints Impact Analysis
| Factor | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Manufacturing shortages and starter-dose allocation | -1.4% | Global and Europe | Short term (<= 2 years) |
| Reimbursement eligibility and staged commissioning rules | -1.1% | UK, Japan and Germany | Medium term (2-4 years) |
| Gastrointestinal side effects and discontinuation during titration | -0.9% | Global | Short term (<= 2 years) |
| Regulatory action against unregistered or manipulated products | -0.5% | Brazil, UK and Europe | Medium term (2-4 years) |
Which countries are scaling the GLP-1 Market through 2036?
- Germany: Diagnosed diabetes and adult obesity indicators create a broad physician-supervised treatment pool, while EMA medical-supervision expectations keep GLP-1 use tied to formal prescribing and pharmacy controls.
- Brazil: Anvisa's approval record for Wegovy and Mounjaro, prescription-retention rules and new semaglutide registrations are expanding regulated access while steering demand away from informal channels.
- USA: CDC diabetes and obesity data create a large metabolic-care base, and FDA approvals for cardiovascular, weight-management, kidney and sleep-apnea indications widen the clinical reasons to prescribe GLP-1 and dual agonist therapies.
- UK: NICE appraisal and NHS commissioning rules are shaping a staged obesity-treatment pathway, so uptake depends on eligibility, primary-care rollout and safe-use guidance rather than unconstrained demand.
- Japan: PMDA approval of Wegovy and national diabetes burden data support use in supervised obesity and diabetes care, while restrictive prescribing criteria keep growth focused on patients with defined comorbidities.
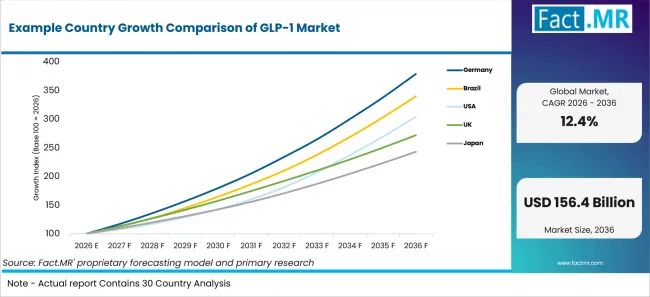
Example Country Growth Comparison Of Glp 1 Market | Source: Fact.MR
| Country | CAGR, 2026-2036 |
|---|---|
| Germany | 14.3% |
| Brazil | 13.0% |
| USA | 11.8% |
| UK | 10.5% |
| Japan | 9.3% |
What is driving Germany's growth through 2036?
Germany is forecast to expand at a 14.3% CAGR from 2026 to 2036.
RKI reported that 10.3% of adults in Germany had physician-diagnosed diabetes in 2024. The institute also reported that overweight, including obesity, affects 46.6% of women and 60.5% of men, with nearly one-fifth of adults living with obesity. This creates a sizeable pool of adults who may move through endocrinology, primary care and obesity-management pathways.
Growth is also shaped by supervision and reimbursement discipline. EMA guidance treats GLP-1 medicines as prescription products and warns against unsupervised use during shortages. That puts demand through formal channels, favouring therapies with reliable supply, clear dosing support and physician confidence.
What is driving Brazil's growth through 2036?
Brazil is forecast to expand at a 13.0% CAGR from 2026 to 2036.
Ministerio da Saude's Vigitel 2023 updates chronic disease risk indicators across Brazilian capitals, giving public-health planners a current view of obesity, diabetes, hypertension and related risks. That monitoring matters for GLP-1 therapy because demand is linked to adult metabolic-risk identification and referral.
Anvisa has also widened the formal product base. Wegovy is registered for adult weight management with comorbidities, Mounjaro is registered for type 2 diabetes, and Anvisa registered five new semaglutide pens in 2026 after prioritizing semaglutide and liraglutide review for supply reasons. Prescription retention rules keep channel growth tied to authorized pharmacies.
What is driving USA's growth through 2036?
The USA is forecast to expand at an 11.8% CAGR from 2026 to 2036.
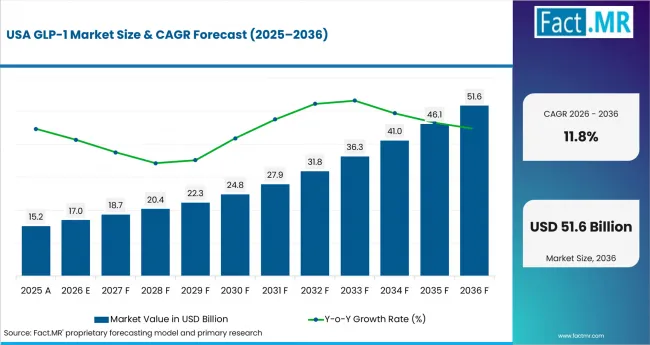
Glp 1 Market Country Value Analysis | Source: Fact.MR
CDC reported 40.1 million people with diagnosed or undiagnosed diabetes in the United States in 2023 and 115.2 million adults with prediabetes. CDC obesity statistics also show more than two in five U.S. adults with obesity. Together, these conditions create repeated prescribing opportunities in diabetes, weight management and cardiometabolic-risk care.
The FDA has expanded GLP-1 and dual agonist clinical use beyond glucose control. Wegovy is approved for cardiovascular-risk reduction in adults with obesity or overweight and established cardiovascular disease, Zepbound is approved for chronic weight management and for moderate-to-severe obstructive sleep apnea in adults with obesity, and Ozempic labeling includes kidney and cardiovascular-risk language in type 2 diabetes with chronic kidney disease.
What is driving UK's growth through 2036?
The UK is forecast to expand at a 10.5% CAGR from 2026 to 2036.
NICE recommended semaglutide for managing overweight and obesity in 2023 and tirzepatide in TA1026 for adults meeting BMI and comorbidity criteria. NHS England's interim commissioning guidance places tirzepatide into a staged pathway rather than immediate open prescribing, which shapes how quickly eligible patients move into treatment.
MHRA guidance reinforces that GLP-1 medicines should be used for licensed conditions such as diabetes or overweight and obesity, not for aesthetic weight loss. That creates a safer access framework but also limits unsupervised expansion, making pharmacy validation and clinician follow-up important growth conditions.
What is driving Japan's growth through 2036?
Japan is forecast to expand at a 9.3% CAGR from 2026 to 2036.
IDF reports 8.97 million adults with diabetes in Japan in 2024, while the National Health and Nutrition Survey provides the official long-running base for health, nutrition and lifestyle indicators. GLP-1 demand is therefore tied to established diabetes care and to obesity disease definitions rather than broad wellness use.
PMDA lists Wegovy, semaglutide, as approved in March 2023. Japan's use of regulated approval and insurance-based access supports physician-supervised adoption, especially for adult patients with defined obesity-related complications, but it also keeps the market more deliberate than countries where private self-pay channels expand quickly.
Who Leads the GLP-1 Market?
Key players in the GLP-1 Market include Novo Nordisk A/S, Eli Lilly and Company, Pfizer Inc., AstraZeneca PLC, Sanofi S.A., Boehringer Ingelheim and Amgen Inc.
Novo Nordisk and Eli Lilly have marketed GLP-1 and dual agonist experience, while Pfizer, AstraZeneca, Sanofi, Boehringer Ingelheim and Amgen participate through diabetes franchises, metabolic disease portfolios, partnerships or pipeline activity. Product differentiation increasingly depends on route, tolerability, label breadth, refill support and supply performance.
Regulatory scrutiny is now part of competition. EMA, MHRA and Anvisa materials all point to supervision, shortages or unauthorized-use concerns, so companies that protect formal channels and provide clear patient-support infrastructure are better positioned with hospitals, pharmacies and payers.
Which companies are the key providers?
Novo Nordisk A/S, Eli Lilly and Company, Pfizer Inc., AstraZeneca PLC, Sanofi S.A., Boehringer Ingelheim and Amgen Inc.
- Novo Nordisk A/S
- Eli Lilly and Company
- Pfizer Inc.
- AstraZeneca PLC
- Sanofi S.A.
- Boehringer Ingelheim
- Amgen Inc.
Bibliography
- Agencia Nacional de Vigilancia Sanitaria. (2023). Wegovy (semaglutida). Anvisa.
- Agencia Nacional de Vigilancia Sanitaria. (2023). Mounjaro (tirzepatida): novo registro. Anvisa.
- Agencia Nacional de Vigilancia Sanitaria. (2025). Medicamentos agonistas GLP-1 so poderao ser vendidos com retencao da receita. Anvisa.
- Agencia Nacional de Vigilancia Sanitaria. (2026). Anvisa aprova novas indicacoes para semaglutida e tezepelumabe. Anvisa.
- Agencia Nacional de Vigilancia Sanitaria. (2026). Anvisa registra cinco novas canetas de semaglutida. Anvisa.
- American Diabetes Association. (2025). The American Diabetes Association releases Standards of Care in Diabetes 2026. ADA.
- Centers for Disease Control and Prevention. (2024). Adult Obesity Facts. CDC.
- Centers for Disease Control and Prevention. (2026). National Diabetes Statistics Report. CDC.
- European Medicines Agency. (2024). EU actions to tackle shortages of GLP-1 receptor agonists. EMA.
- International Diabetes Federation. (2025). Facts and figures. IDF.
- International Diabetes Federation. (2026). Japan. IDF.
- Medicines and Healthcare products Regulatory Agency. (2026). GLP-1 medicines for weight loss and diabetes: what you need to know. GOV.UK.
- Ministerio da Saude. (2026). Vigitel Brasil 2023: vigilancia de fatores de risco e protecao para doencas cronicas por inquerito telefonico. Government of Brazil.
- National Health and Nutrition Survey. (2026). National Health and Nutrition Survey. National Institute of Biomedical Innovation, Health and Nutrition.
- National Institute for Health and Care Excellence. (2023). Semaglutide for managing overweight and obesity. NICE.
- National Institute for Health and Care Excellence. (2024). Tirzepatide for managing overweight and obesity. NICE.
- NHS England. (2025). Interim commissioning guidance for implementation of NICE TA1026 and the funding variation for tirzepatide. NHS England.
- Pharmaceuticals and Medical Devices Agency. (2026). Review Reports: Drugs. PMDA.
- Robert Koch Institute. (2025). Diabetes mellitus: prevalence from 18 years. RKI.
- Robert Koch Institute. (2026). Overweight and obesity. RKI.
- U.S. Food and Drug Administration. (2023). FDA approves new medication for chronic weight management. FDA.
- U.S. Food and Drug Administration. (2024). FDA approves first medication for obstructive sleep apnea. FDA.
- U.S. Food and Drug Administration. (2024). FDA approves first treatment to reduce risk of serious heart problems specifically in adults with obesity or overweight. FDA.
- U.S. Food and Drug Administration. (2025). Ozempic prescribing information. FDA.
- World Health Organization. (2025). Obesity and overweight. WHO.
This Report Answers
- Which GLP-1 therapy groups are shaping prescription demand through 2036?
- How do injectable and oral routes affect patient access, refills and adherence?
- Which applications and patient groups drive therapy use across diabetes, obesity and cardiometabolic care?
- How are pharmacy channels, hospitals and specialty clinics influencing supervised GLP-1 access?
- Which countries are expanding through distinct regulatory, disease-burden and access mechanisms?
What does the GLP-1 Market cover?
The GLP-1 Market covers prescription therapies that act through GLP-1 receptors or related dual and multi receptor mechanisms for type 2 diabetes management, obesity and weight management, cardiometabolic disorders and adjacent therapeutic applications named in the segmentation.
Revenue is counted at therapy level for approved and pipeline products within the stated product, route, application, distribution, end-use and patient groups.The assessment covers Product, Route Of Administration, Application, Distribution Channel, End Use and Patient Type across Germany, Brazil, USA, UK and Japan.
What is included in the scope?
The scope includes GLP-1 Receptor Agonists, semaglutide based therapies, liraglutide based therapies, dulaglutide based therapies, exenatide based therapies, lixisenatide based therapies, Dual And Triple Agonists, GLP-1 And GIP Agonists, GLP-1 Multi Receptor Agonists, Pipeline GLP-1 Therapies, Small Molecule GLP-1 Therapies and Long Acting Formulations.
It includes Injectable Therapies, Prefilled Pens, Auto Injectors, Oral Therapies, Tablets and Capsules when supplied as GLP-1 treatment. Applications include Type 2 Diabetes Management, Obesity And Weight Management, Cardiometabolic Disorders and Other Therapeutic Applications as listed in the segmentation.
Distribution covers Retail Pharmacies, Hospital Pharmacies and Online Pharmacies. End-use settings include Hospitals, Specialty Clinics, Homecare Settings and Research Institutes. Patient groups include Adult Population and Pediatric Population where the stated indications apply.
What is excluded from the scope?
The scope excludes insulin products without GLP-1 activity, diabetes devices sold alone, nutrition coaching, food or supplement products, digital adherence services sold separately, compounded or unregistered GLP-1 preparations, illicit products and cosmetic weight-loss use outside licensed or regulated indications.
Drug-delivery pens, cold-chain services, marketing support and patient-support services are excluded when billed separately from the GLP-1 therapy. Research reagents and laboratory GLP-1 materials are also outside the therapeutic market definition.
How Was the Analysis Built?
The analysis draws on public health statistics, regulatory approvals, clinical guidance, company portfolios and prescribing-channel evidence.
- Primary Research: Interviews with endocrinologists, obesity-care clinicians, hospital pharmacy leaders, retail pharmacy operators and pharmaceutical commercial teams examine prescribing decisions, titration support, refill behaviour, reimbursement access and supply constraints.
- Desk Research: The review covers diabetes and obesity prevalence, GLP-1 approvals, technology appraisals, national prescribing guidance, shortage notices, company product information and channel controls. External sources used in the article are recorded in the bibliography.
- Market Sizing and Forecasting: The model combines diagnosed diabetes burden, obesity eligibility, approved indications, route mix, per-patient therapy duration, refill channel, discontinuation during titration, country access conditions and pipeline conversion.
- Data Validation and Update Cycle: Findings are cross-checked against company activity, public data and industry interviews. Updates account for product approvals, label expansions, supply availability, pharmacy controls, reimbursement criteria and changes in patient eligibility.
What is the report's scope and coverage?
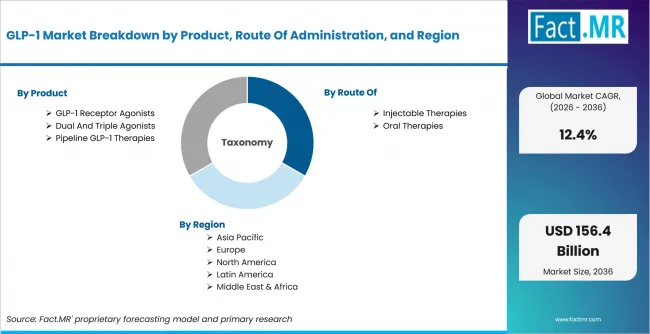
Glp 1 Market Breakdown By Product, Route Of Administration, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Prescription GLP-1, dual agonist, multi receptor agonist and pipeline GLP-1 therapies used across the specified metabolic and cardiometabolic applications |
| Segments Covered | Product; Route Of Administration; Application; Distribution Channel; End Use; Patient Type |
| Regions Covered | North America; Latin America; Europe; East Asia |
| Countries Covered | Germany; Brazil; USA; UK; Japan |
| Key Companies Profiled | Novo Nordisk A/S; Eli Lilly and Company; Pfizer Inc.; AstraZeneca PLC; Sanofi S.A.; Boehringer Ingelheim; Amgen Inc. |
| Historical Period | 2021 to 2025 |
| Forecast Period | 2026 to 2036 |
| Base Year | 2025 |
| Market Value, 2026 | USD 48.6 billion |
| Market Value, 2036 | USD 156.4 billion |
| CAGR, 2026-2036 | 12.4% |
| Absolute Opportunity | USD 107.8 billion |
| Approach | Hybrid top-down and bottom-up approach using diabetes prevalence, obesity eligibility, approved indications, route mix, refill channel, country access rules and pipeline conversion |
How is the market segmented?
-
By Product:
- GLP-1 Receptor Agonists
- Semaglutide Based Therapies
- Liraglutide Based Therapies
- Dulaglutide Based Therapies
- Exenatide Based Therapies
- Lixisenatide Based Therapies
- Dual And Triple Agonists
- GLP-1 And GIP Agonists
- GLP-1 Multi Receptor Agonists
- Pipeline GLP-1 Therapies
- Small Molecule GLP-1 Therapies
- Long Acting Formulations
- GLP-1 Receptor Agonists
-
By Route Of Administration:
- Injectable Therapies
- Prefilled Pens
- Auto Injectors
- Oral Therapies
- Tablets
- Capsules
- Injectable Therapies
-
By Application
- Type 2 Diabetes Management
- Glycemic Control
- Cardiovascular Risk Reduction
- Obesity And Weight Management
- Chronic Weight Management
- Metabolic Syndrome Management
- Cardiometabolic Disorders
- Hypertension Management
- Dyslipidemia Management
- Other Therapeutic Applications
- Neurodegenerative Disorders
- Liver Disorders
- Type 2 Diabetes Management
-
By Distribution Channel:
- Retail Pharmacies
- Hospital Pharmacies
- Online Pharmacies
-
By End Use:
- Hospitals
- Specialty Clinics
- Homecare Settings
- Research Institutes
-
By Patient Type:
- Adult Population
- Middle Age Population
- Elderly Population
- Pediatric Population
- Obesity Management
- Diabetes Management
- Adult Population
-
By Region:
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa