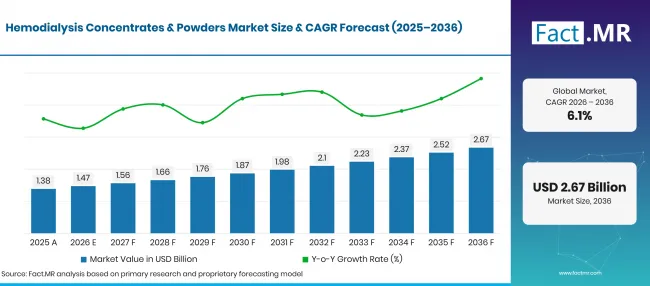
- Market Value (2025): USD 1.38 Bn
- Estimated Value (2026): USD 1.47 Bn
- Forecast Value (2036): USD 2.67 Bn
- CAGR (2026-2036): 6.1%
What is the Hemodialysis Concentrates & Powders Market forecast to be worth by 2036?
USD 1.47 billion in 2026 to USD 2.67 billion by 2036 at a 6.1% CAGR.
- The Hemodialysis Concentrates & Powders Market is estimated at USD 1.38 billion in 2026.
- Demand is projected to increase from USD 1.47 billion in 2026 to USD 2.67 billion by 2036.
- The market is forecast to record 6.1% CAGR from 2026 to 2036.
Hemodialysis Concentrates And Powders Market Breakdown End User (9) | Source: Fact.MR
What are the defining numbers behind Hemodialysis Concentrates & Powders Market growth?
An aggregate growth potential of USD 1.2 billion is anticipated between 2026 and 2036.
- Demand Drivers in the Market
- Rising chronic kidney disease and end-stage kidney disease prevalence is the base of demand. Aging populations and the growing burden of diabetes and hypertension increase the number of patients who need regular dialysis, and each treatment uses a set volume of dialysate.
- Recurring treatment schedules make demand highly predictable. Most hemodialysis patients are treated several times per week, so concentrate and powder consumption follows patient counts closely and is less exposed to economic cycles than elective care.
- Expansion of dialysis capacity in emerging markets is widening the customer base. Wider insurance coverage and the opening of new dialysis centers in countries such as Thailand and Turkey increase treatment access and the volume of concentrates required.
- Key Segments Analyzed
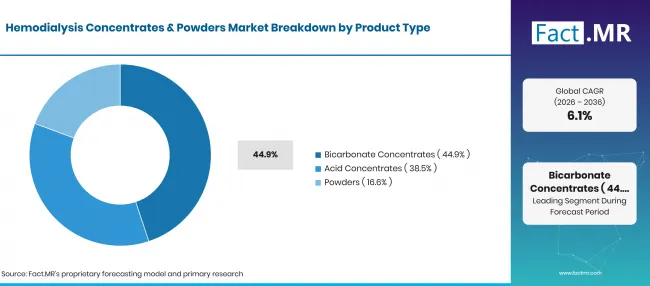
- By Product Type: Bicarbonate concentrates are positioned to secure a 44.9% share in 2026. Bicarbonate serves as the standard buffer in modern dialysate and is required in every treatment, which sustains consistent demand.
- By Application: In-center dialysis is on track to represent an 81.4% share in 2026. Most patients receive scheduled treatment in staffed facilities, which purchase concentrates in large volumes.
- By End-User: Dialysis centers are set to hold a 52.8% share in 2026. Dedicated centers perform the largest portion of treatments and procure concentrates through recurring supply contracts.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, "Dialysis concentrates represent a volume-driven business anchored in treatment frequency. Providers place the highest priority on consistent quality and dependable delivery, as any supply failure disrupts life-sustaining therapy. Bicarbonate concentrates remain central to every session, while powders and home-ready formats offer suppliers a practical route to lower logistics costs and enter new care settings."
- Strategic Implications
- Suppliers are advised to secure multi-site manufacturing and buffer inventory. Dialysis providers treat supply continuity and batch consistency as their primary selection criteria, so resilient production and stock planning strengthen a supplier's standing.
- Manufacturers of liquid concentrates are encouraged to evaluate powder and on-site mixing options. Lower freight weight and reduced storage requirements appeal to high-volume centers and to markets with long delivery distances.
- Companies targeting large provider networks would benefit from aligning pricing with tender and contract cycles. Pairing this with quality documentation that meets the regulatory and clinical standards of each country reinforces credibility with buyers.
Thailand sets the pace at 7.7% CAGR, supported by wider dialysis coverage and growing treatment capacity. Turkey ranks second at 7.3% as its large dialysis network continues to expand. The USA achieves 6.4% on the back of a large patient base and concentrated provider networks. Belgium registers 5.8% through a mature, well-reimbursed renal care system. France posts 4.9%, while Japan attains 4.5% in a highly mature market with a long-established dialysis base.
How does the Hemodialysis Concentrates & Powders Market break down by segment?
Bicarbonate Concentrates are foreseen to lead Product Type at 44.9% share in 2026; In-Center Dialysis leads Application at 81.4% share, while Dialysis Centers lead End-User at 52.8% share.
Which Product Type dominates?
Bicarbonate Concentrates are expected to hold 44.9% share in 2026.
Hemodialysis Concentrates And Powders Market Breakdown End User (2) | Source: Fact.MR
Bicarbonate concentrates hold the leading position because bicarbonate is the standard buffer used to correct acid-base balance in dialysis patients. It is required in every hemodialysis session and is blended with an acid concentrate and purified water on the dialysis machine.
Consumption per session is high, and the product must be supplied reliably in large volumes. Providers therefore contract with suppliers able to deliver consistent quality, which gives bicarbonate concentrates a steady and broad revenue base across all end users.
What leads the Application segment?
In-Center Dialysis is projected to account for 81.4% share in 2026.
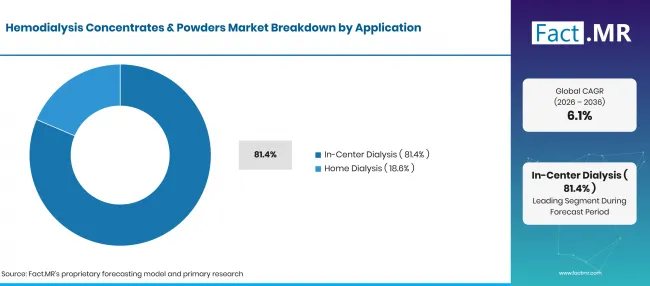
Hemodialysis Concentrates And Powders Market Breakdown End User (17) | Source: Fact.MR
In-center dialysis holds the leading position because most patients are treated in staffed facilities several times per week. These sites operate many machines in parallel and purchase concentrates and powders in bulk under supply agreements.
Home dialysis is smaller today but is set to gain share as providers and health systems encourage treatment closer to patients. This shift favors compact, easy-to-use formats, although in-center treatment remains the dominant setting through 2036.
How does End-User shape demand?
Dialysis Centers are anticipated to lead with 52.8% share in 2026.
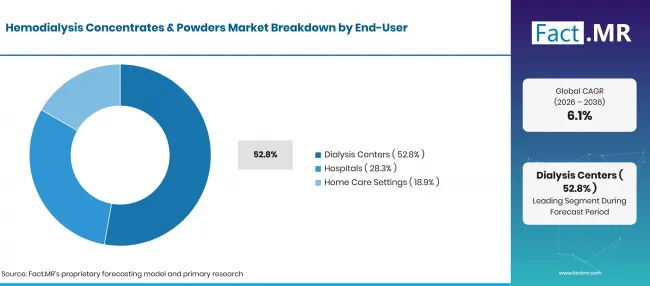
Hemodialysis Concentrates And Powders Market Breakdown End User (1) | Source: Fact.MR
Dialysis centers hold the leading position because they are dedicated to renal care and handle the highest treatment volumes. Purchasing is organized around recurring contracts and standard product specifications, which concentrates volume with suppliers able to serve many sites.
Hospitals and home care settings make up the rest of the end-user base. Hospitals treat acute and inpatient cases that require dialysis, while home care settings are expanding as more patients adopt home hemodialysis. Both buy in smaller and more varied quantities than dialysis centers.
What is accelerating Hemodialysis Concentrates & Powders Market adoption, and what is holding it back?
Demand is set to climb as dialysis patient numbers grow and treatment access widens. At the same time, expansion may be curbed by kidney transplantation, pricing pressure from large providers and the cost of meeting quality standards.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Growing prevalence of chronic kidney disease linked to ageing, diabetes and hypertension | +1.8% | Global | Medium term (2-4 years) |
| Broader dialysis capacity and insurance coverage across emerging markets | +1.3% | East Asia, Middle East & Africa, South Asia & Pacific | Medium term (2-4 years) |
| Lower logistics and storage costs enabled by powder-based supply | +0.9% | Global | Short term (<= 2 years) |
| Predictable treatment schedules that keep volumes steady | +0.7% | Global | Long term (>= 4 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Tailored supply formats and delivery services for home hemodialysis | +1.1% | North America, Europe, East Asia | Long term (>= 4 years) |
| Powder-based on-site mixing systems for high-volume centers | +0.9% | Global | Medium term (2-4 years) |
| Establishment of new dialysis networks in underserved regions | +0.7% | South Asia & Pacific, Middle East & Africa, Latin America | Long term (>= 4 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Pricing pressure from large dialysis providers and public tenders | -0.7% | Global | Short term (<= 2 years) |
| Kidney transplantation and slower disease progression reducing dialysis demand | -0.4% | Europe, North America, East Asia | Long term (>= 4 years) |
| Quality, water and regulatory compliance costs for manufacturers | -0.4% | Europe, North America | Medium term (2-4 years) |
Which countries are scaling the Hemodialysis Concentrates & Powders Market through 2036?
- The country comparison spans 3.2 percentage points and falls into three practical growth bands across the forecast period.
- Japan sits at the lower end of the range as a highly mature dialysis market with an established patient base.
- France stands 0.4 percentage point ahead of Japan, as national coverage and a growing focus on home dialysis sustain steady demand.
- Belgium is 0.9 percentage point ahead of France, owing to a mature, well-reimbursed renal care system.
- The USA is 0.6 percentage point ahead of Belgium, driven by a large patient base and concentrated provider networks.
- Turkey is 0.9 percentage point ahead of the USA, as its large dialysis network continues to expand.
- Thailand takes the top position, 0.4 percentage point ahead of Turkey, backed by wider dialysis coverage and growing treatment capacity.
Similar CAGRs can translate into very different market-entry conditions, depending on patient volumes, reimbursement models, provider structures and regulatory requirements. Full report coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Middle East & Africa.
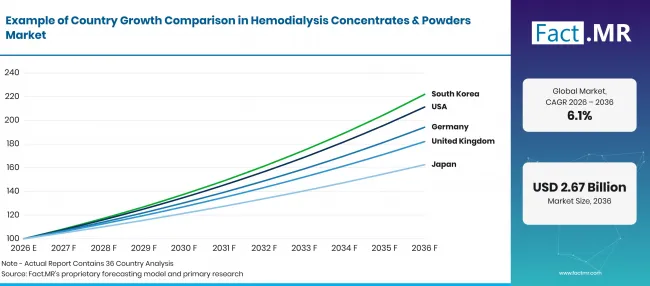
Hemodialysis Concentrates And Powders Market Breakdown End User (11) | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| United States | 6.4% |
| Belgium | 5.8% |
| Thailand | 7.7% |
| France | 4.9% |
| Turkey | 7.3% |
| Japan | 4.5% |
What supports USA adoption?
The USA is growing at a 6.4% CAGR, supported by a large patient base and concentrated provider networks.
The country has one of the largest dialysis populations in the world, and most patients are treated in facilities run by a handful of large providers. These providers purchase concentrates in high volumes under long-term contracts, which stabilizes demand and favors suppliers with national distribution and consistent quality.
How is Belgium scaling demand?
Belgium is advancing at a 5.8% CAGR, driven by a mature, well-reimbursed renal care system.
A well-developed renal care network and broad reimbursement for dialysis define the market. An ageing population keeps patient numbers edging upward, and steady purchasing by hospitals and dialysis centers sustains demand, although the small population limits growth in absolute volumes.
What supports Thailand's growth?
Thailand is expanding at a 7.7% CAGR, backed by wider dialysis coverage and growing treatment capacity.
Public coverage schemes have widened access to kidney replacement therapy, while both private and public dialysis capacity continue to grow. As more patients enter regular treatment, the number of sessions and the volume of concentrates required both rise, which underpins the fastest growth among the countries analyzed.
How is France developing demand?
France is progressing at a 4.9% CAGR, led by national coverage and a growing focus on home dialysis.
National insurance coverage for dialysis and a mature treatment network characterize the market. Policy interest in home and self-care dialysis creates some demand for new formats, but the established patient base and cost-containment measures hold growth at a moderate level.
What is supporting Turkey's adoption?
Turkey is growing at a 7.3% CAGR, driven by a large and expanding dialysis network.
The country's sizable dialysis population is treated mainly through a broad network of dialysis centers. Ongoing capacity expansion and rising patient numbers lift treatment volumes, while local manufacturing and distribution make Turkey an attractive growth market for concentrate suppliers.
How does Japan perform?
Japan is growing at a 4.5% CAGR, shaped by a long-established dialysis base in a mature market.
Dialysis use is high relative to the population, and the treatment network is deeply established. An ageing population keeps demand for concentrates steady, but the market is mature and patient growth is slow, resulting in the lowest growth among the countries analyzed.
Who leads the Hemodialysis Concentrates & Powders Market?
Fresenius Medical Care AG & Co. KGaA holds the leading position with an estimated 24% share. Its standing reflects its scale as a dialysis provider and its in-house production of dialysis products, including concentrates, which secures internal demand and supports a broad external customer base.
Baxter International Inc. and B. Braun Melsungen AG are established suppliers of renal care products to hospitals and dialysis providers. Nipro Corporation supplies dialysis products across Asia and other regions, while Rockwell Medical Inc. specializes in hemodialysis concentrates and powders for dialysis providers.
Dialife SA, Renacon Pharma Limited, Farmasol and Unipharm JSC serve regional and specialist markets with dialysis concentrates and powders. These suppliers compete on local service, flexible order sizes and competitive pricing.
Competition therefore centers on product consistency and delivery reliability. Regulatory compliance and the ability to serve large provider networks also carry weight, as does the capacity to offer both liquid and powder formats.
Which companies are the key providers?
Key companies include Fresenius Medical Care AG & Co. KGaA; Baxter International Inc.; B. Braun Melsungen AG; Nipro Corporation; Rockwell Medical Inc.; Dialife SA; Renacon Pharma Limited; Farmasol; and Unipharm JSC.
- Fresenius Medical Care AG & Co. KGaA
- Baxter International Inc.
- B. Braun Melsungen AG
- Nipro Corporation
- Rockwell Medical Inc.
- Dialife SA
- Renacon Pharma Limited
- Farmasol
- Unipharm JSC
Biblography
- Agence de la biomédecine. (2026, May 21). REIN 2024 annual report.
- B. Braun SE. (2026). Annual report 2025.
- Baxter International Inc. (2025). Annual report on Form 10-K for the fiscal year ended December 31, 2024. U.S. Securities and Exchange Commission.
- ERA Registry. (2025). ERA Registry annual report 2023. European Renal Association
- Fresenius Medical Care. (2026, March 12). Fresenius Medical Care publishes its Annual Report 2025: The power of care [Press release].
- Japanese Society for Dialysis Therapy. (2025, July). Annual dialysis data report 2022, JSDT Renal Data Registry.
- Nephrology Society of Thailand. (2025). Thailand Renal Replacement Therapy Registry 2023 annual data report: Dialysis center providers in Thailand.
- Rockwell Medical, Inc. (2026, March 26). Rockwell Medical announces fourth quarter and full-year 2025 financial and operational results [Press release].
- Turkish Society of Nephrology. (2026). Current status of kidney replacement therapy in Türkiye: A summary of 2024 Turkish Society of Nephrology Registry report.
- United States Renal Data System. (2025). 2025 annual data report. National Institute of Diabetes and Digestive and Kidney Diseases.
This Report Answers
- The report explains where hemodialysis concentrates and powders are used across product type and application. It also covers end-user and country demand.
- Segment analysis identifies the leading subsegments and the clinical and purchasing reasons providers prioritize them.
- Country analysis examines the listed markets and the patient, reimbursement or capacity factors supporting dialysis demand.
- Competitive analysis reviews current providers across bicarbonate concentrates, acid concentrates and powders. It also covers supply reliability and provider contracting positions.
- Application analysis assesses how treatment setting and patient volumes influence purchase decisions. It also considers pricing pressure and the growth of home dialysis.
What does the Hemodialysis Concentrates & Powders Market cover?
The Hemodialysis Concentrates & Powders Market encompasses the chemical formulations used to prepare dialysate for hemodialysis. This includes bicarbonate concentrates, acid concentrates and powders, supplied in both liquid and dry formats.
The assessment spans in-center and home dialysis across dialysis centers, hospitals and home care settings. Demand is examined across the product type, application and end-user segments.
What is included in the scope?
The scope takes in liquid bicarbonate and acid concentrates, as well as dry bicarbonate and acid powders, supplied in jugs, bags, cartridges and bulk formats for dialysis use.
It also covers products used in in-center and home hemodialysis that are purchased by dialysis centers, hospitals and home care providers.
What is excluded from the scope?
Dialysis machines, dialyzers, bloodlines, water treatment systems and peritoneal dialysis solutions are left out when sold separately from hemodialysis concentrates and powders.
Renal medicines and nutritional products for dialysis patients are likewise outside the scope, as they are not used to prepare dialysate.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Insights were gathered through discussions with manufacturers, service providers, technology developers, distributors, end users and subject-matter experts. These conversations explored purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning and the factors shaping broader market acceptance.
- Desk Research: This stage draws on government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy and other authoritative sources. All sources used in the analysis are listed in the bibliography.
- Market Sizing and Forecasting: Market valuations draw together historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity and barriers to market expansion.
- Data Validation and Update Cycle: Findings are corroborated by cross-referencing primary interviews with public data, company activity, regulatory changes, trade patterns and industry developments. Periodic updates track new product launches, capacity changes, partnerships, approvals and shifts in commercial adoption.
What is the report’s scope and coverage?
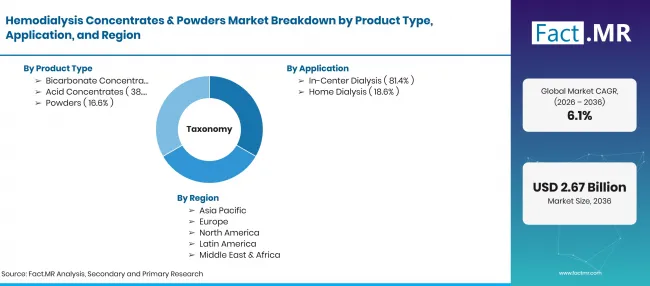
Hemodialysis Concentrates And Powders Market Breakdown End User (16) | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD Billion |
| Market Definition | Electrolyte and buffer formulations mixed with purified water to produce dialysate for hemodialysis, including bicarbonate concentrates, acid concentrates and powders. |
| Product Type | Bicarbonate Concentrates; Acid Concentrates; Powders |
| Application | In-Center Dialysis; Home Dialysis |
| End-User | Dialysis Centers; Hospitals; Home Care Settings |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | United States; Belgium; Thailand; France; Turkey; Japan |
| Key Companies Profiled | Fresenius Medical Care AG & Co. KGaA; Baxter International Inc.; B. Braun Melsungen AG; Nipro Corporation; Rockwell Medical Inc.; Dialife SA; Renacon Pharma Limited; Farmasol; Unipharm JSC |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using dialysis patient volumes; treatment sessions; concentrate consumption per session; product type mix; country adoption; and provider portfolio review. |
How is the market segmented?
-
By Product Type:
- Bicarbonate Concentrates
- Acid Concentrates
- Powders
-
By Application:
- In-Center Dialysis
- Home Dialysis
-
By End-User:
- Dialysis Centers
- Hospitals
- Home Care Settings
-
By Region:
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa