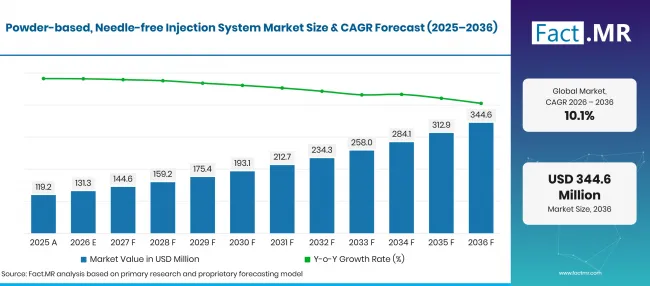
- Market Value (2025): USD 119.2 Mn
- Estimated Value (2026): USD 131.3 Mn
- Forecast Value (2036): USD 344.6 Mn
- CAGR (2026-2036): 10.1%
What is the Powder-based, Needle-free Injection System Market forecast to be worth by 2036?
USD 131.3 million in 2026 to USD 344.6 million by 2036 at a 10.1% CAGR.
- The Powder-based, Needle-free Injection System Market is estimated at USD 119.2 million in 2025.
- Demand is projected to increase from USD 131.3 million in 2026 to USD 344.6 million by 2036.
- The market is forecast to record 10.1% CAGR from 2026 to 2036.
Powder Based, Needle Free Injection System Market Company Share (6) | Source: Fact.MR
What are the defining numbers behind Powder-based, Needle-free Injection System Market growth?
A total prospect of USD 213.3 million is expected between 2026 and 2036.
- Demand Drivers in the Market
- Large-scale vaccination initiatives are driving demand for faster, simpler administration. Needle-free systems reduce training requirements and enable high-throughput campaigns, while governments are placing greater emphasis on readiness for future outbreaks.
- Dry powder formats ease storage and handling. Because they depend less on refrigeration than liquid products, they suit regions with limited cold-chain infrastructure and help curb product wastage.
- Rising treatment volumes for conditions such as diabetes, which require frequent injections, are broadening the addressable market. Patients and providers alike are showing growing interest in needle-free options for self-administration and home use.
- Key Segments Analyzed
- Powder-based injectors are set to command a 38.6% share in 2026, as dry formulations offer greater stability and enable needle-free delivery through the skin without reconstitution.
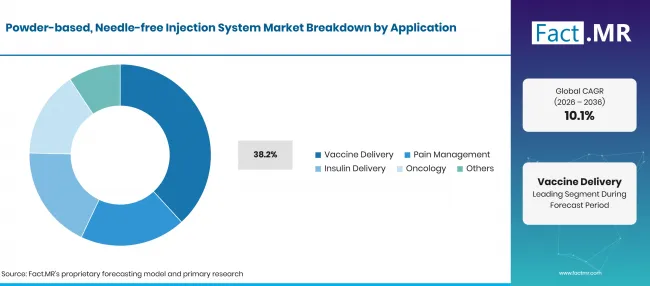
- Vaccine delivery is poised to represent a 38.2% share in 2026, driven by immunization programs that prioritize rapid administration, reduced sharps risk, and dose-sparing delivery to the skin.
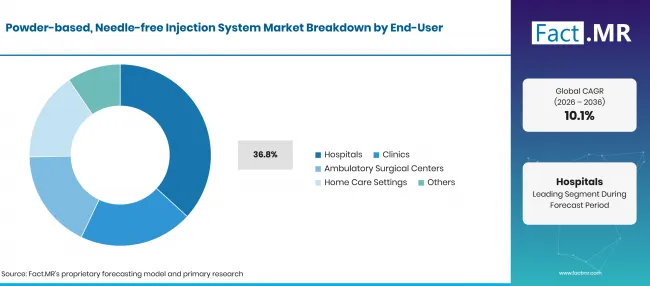
- Hospitals are positioned to secure a 36.8% share in 2026, reflecting their large-scale vaccination and treatment programs and their reliance on formal evaluation and purchasing processes when adopting new delivery technology.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, notes, "Needle-free injection is on course to evolve from a niche alternative into a mainstream option for mass immunization and self-administration. Going forward, buyers will increasingly look for evidence of dose accuracy, safety, and cost per administration, and will favor systems that integrate seamlessly into existing workflows. Powder-based delivery is well placed to lead this transition, as dry formulations offer stability advantages that liquid systems will find difficult to match."
- Strategic Implications
- Device manufacturers are advised to engage vaccine and drug developers at an early stage, as powder-based delivery relies on formulations that are co-developed and approved alongside the device.
- Suppliers need to publish clinical data on dose accuracy, immune response, and tolerability, since regulators and buyers benchmark needle-free systems directly against conventional syringes.
- Companies are encouraged to build robust health-economic evidence covering needle-stick injuries avoided, sharps disposal savings, and training time, as this strengthens the case for reimbursement and procurement.
- Manufacturers targeting self-administration must prioritize simple, reliable device design with clear instructions, as home users require ease of use and consistent dosing without clinical supervision.
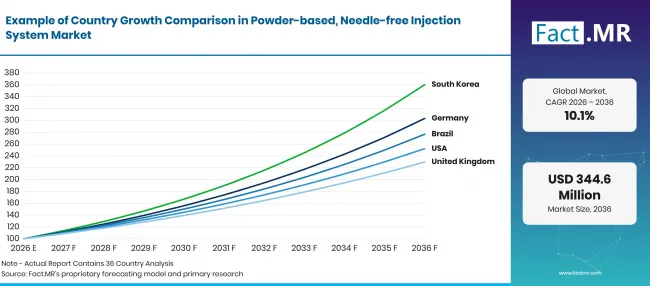
The USA takes the lead at a 12.5% CAGR, supported by large-scale immunization programs and a deep drug-delivery development base. South Korea trails closely at 12.1%, as its biotechnology and vaccine sector continues to expand. The Netherlands advances at 11.2%, underpinned by its life-science cluster, while the UK registers 10.2% on the strength of public immunization programs. Germany logs 8.9%, France reaches 8.3%, and Belgium stands at 7.5%, reflecting markets with strong vaccine activity but slower device adoption.
How does the Powder-based, Needle-free Injection System Market break down by segment?
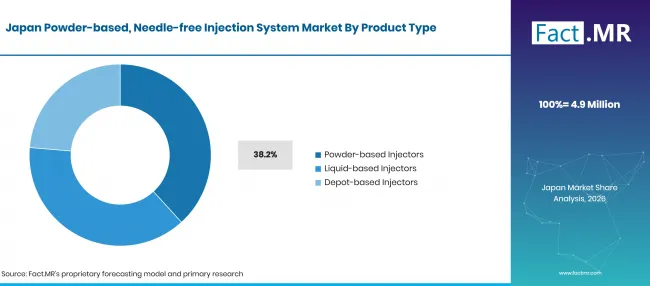
Powder-based Injectors are projected to lead Product Type at 38.2% share in 2026; Vaccine Delivery leads Application at 38.2% share, while Hospitals lead End-User at 36.8% share.
Which Product Type dominates?
Powder-based Injectors are expected to hold 38.2% share in 2026.
Powder Based, Needle Free Injection System Market Company Share (9) | Source: Fact.MR
Powder-based injectors hold the leading position because they deliver a dry drug or vaccine through the skin using gas- or spring-driven force, eliminating both the needle and the liquid reconstitution step. This removes the sharps hazard and simplifies preparation for the user.
Dry formulations can also offer greater stability than liquids and may reduce reliance on cold storage. These advantages are particularly valuable for vaccines, giving powder-based injectors a stronger competitive position than liquid-based and depot-based systems.
What leads the Application segment?
Vaccine Delivery is projected to account for 38.2% share in 2026.
Powder Based, Needle Free Injection System Market Company Share (14) | Source: Fact.MR
Vaccine delivery occupies the leading position, as immunization represents the largest repeated-use setting for needle-free systems. Vaccination campaigns require rapid administration, reduced sharps risk, and minimal waste, while delivery to the skin can support dose-sparing approaches.
Pain management, insulin delivery, and oncology rank next, as patients and providers seek needle-free options for repeated or long-term treatment. These applications remain smaller today, but their relevance is growing as drug developers increasingly pair new formulations with needle-free devices
How does End-User shape demand?
Hospitals are anticipated to lead with 36.8% share in 2026.
Powder Based, Needle Free Injection System Market Company Share (15) | Source: Fact.MR
Hospitals represent the leading end-user segment, as they operate the largest vaccination and treatment programs and maintain formal processes for evaluating new devices. Their purchasing decisions weigh clinical evidence, staff safety, and total cost, which favors suppliers with robust supporting data.
Clinics, ambulatory surgical centers, and home care settings make up the remainder of the end-user base. Clinics and home care are poised to expand as simpler devices enable administration outside the hospital setting, although hospitals are expected to remain the largest single channel through 2036.
What is driving adoption of the powder-based needle-free injection system market, and what is constraining it?
Demand is anticipated to strengthen on the back of needle-stick safety priorities and expanding immunization programs. Growth may be tempered by high device costs, the complexity of formulation development, and a slow pace of clinical adoption.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Heightened focus on needle-stick injury prevention and sharps waste reduction | +2.6% | Global | Medium term (2-4 years) |
| Expansion of mass immunization programs and outbreak preparedness initiatives | +2.1% | Global | Medium term (2-4 years) |
| Growing patient preference for needle-free options, driven by needle fear | +1.6% | North America, Europe, East Asia | Short term (<= 2 years) |
| Superior stability profile of dry powder formulations | +1.1% | Global | Long term (>= 4 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Shift of chronic therapy administration to the home setting | +1.8% | North America, Europe, East Asia | Long term (>= 4 years) |
| Intradermal vaccination that extends vaccine supply through dose sparing | +1.3% | Global | Medium term (2-4 years) |
| Joint development programs between device makers and drug developers | +0.9% | North America, Europe, East Asia | Medium term (2-4 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Higher device cost and cost per administration relative to conventional syringes | -1.2% | Global | Short term (<= 2 years) |
| Formulation development complexity and stringent drug-device combination approval requirements | -0.8% | North America, Europe | Medium term (2-4 years) |
| Gradual uptake of new injection methods among clinicians and patients | -0.5% | Global | Long term (>= 4 years) |
Which countries are scaling the Powder-based, Needle-free Injection System Market through 2036?
- The country comparison covers a 5.0 percentage point spread, which sorts into three growth bands over the forecast period.
- The USA edges out South Korea by 0.4 percentage point, helped by large immunization programs and a deep drug-delivery development base.
- South Korea tops the Netherlands by 0.9 percentage point as its biotechnology and vaccine sector continues to grow.
- The Netherlands exceeds the UK by 1.0 percentage point, drawing on its life-science cluster and vaccine research base.
- The UK outpaces Germany by 1.3 percentage points, reflecting public immunization programs and a strong research base.
- Germany stays 0.6 percentage point above France, as a large healthcare market that adopts new devices with caution.
- France finishes 0.8 percentage point clear of Belgium, owing to national immunization policy and a domestic needle-free device developer.
- Belgium sits at the bottom of the range as a smaller market with strong vaccine production but slower device adoption.
Comparable CAGRs can create different entry conditions due to immunization policy, reimbursement models, regulatory requirements and procurement structures. Full report coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Middle East & Africa.
Powder Based, Needle Free Injection System Market Company Share (8) | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| United States | 12.5% |
| South Korea | 12.1% |
| United Kingdom | 10.2% |
| Germany | 8.9% |
| France | 8.3% |
| Belgium | 7.5% |
| Netherlands | 11.2% |
What is behind the USA's strong uptake?
Growing at a 12.5% CAGR on the strength of large immunization programs and a deep drug-delivery development base.
The USA runs some of the biggest immunization programs worldwide and counts a dense mix of device developers, drug companies, and research funders. Well-established regulatory pathways for needle-free devices smooth clinical adoption and give the country the fastest growth in the set.
What is fueling demand in South Korea?
Expanding at a 12.1% CAGR, propelled by a growing biotechnology and vaccine sector.
South Korea has a quickly expanding biotechnology industry, modern hospital infrastructure, and government support for vaccine and drug-delivery development. Active research and a willingness to try new medical technology early keep demand for needle-free systems rising.
What is behind the UK's growth?
Advancing at a 10.2% CAGR, helped by public immunization programs and a strong research base.
The UK carries out national immunization programs through its public health system and has a deep life-science research community. Central procurement can speed adoption once a system proves its clinical and cost benefits, though buyers hold suppliers to strict value tests.
What shapes demand in Germany?
Progressing at an 8.9% CAGR, tempered by a large healthcare market that adopts new devices with caution.
Germany's sizable healthcare system and high vaccination activity provide a broad base for needle-free systems. Growth runs slower because of strict device regulation, cost-containment measures, and a conservative view of new technology.
What is driving adoption in France?
Rising at an 8.3% CAGR, lifted by national immunization policy and a domestic device developer.
France pairs a national vaccination policy with a home-grown developer of needle-free injection systems. Both raise awareness and secure local supply, but reimbursement and procurement rules hold adoption to a gradual pace.
Where does Belgium stand?
Moving at a 7.5% CAGR, shaped by strong vaccine production and slower device adoption.
Belgium is a major European site for vaccine manufacturing and clinical research. Its small population caps domestic volume, and clinics are slow to take up new injection devices, which leaves Belgium with the lowest growth in the country set.
What is powering the Netherlands?
Climbing at an 11.2% CAGR, fueled by a strong life-science cluster and vaccine research base.
The Netherlands has a tightly knit life-science cluster, busy vaccine research, and a high-quality healthcare system. Close ties between research centers, hospitals, and device developers help new delivery technologies move from testing to routine use.
Which company holds the top position in the powder-based, needle-free injection system market?
PharmaJet, Inc. sits at the front with an estimated 5% share. That modest figure signals a fragmented market where no supplier has reached scale. The company is best known for needle-free injection systems used in vaccination programs.
Inovio Pharmaceuticals, Inc. develops DNA medicines and the devices that deliver them, while Halozyme Therapeutics offers drug-delivery technology and injection device expertise. Crossject SA builds needle-free injectors for emergency treatments.
Portal Instruments, Inc. designs needle-free injection devices for biologic drugs, and Medical International Technologies supplies needle-free jet injectors across a range of uses.
Competition therefore turns on clinical evidence and partnerships with drug and vaccine developers. Regulatory approval, device reliability, and cost per administration also weigh heavily, as does the ability to handle a broad range of formulations.
Which companies are the key providers?
Key companies include PharmaJet, Inc.; Inovio Pharmaceuticals, Inc.; Halozyme Therapeutics; Crossject SA; Portal Instruments, Inc.; and Medical International Technologies.
- PharmaJet, Inc.
- Inovio Pharmaceuticals, Inc.
- Halozyme Therapeutics
- Crossject SA
- Portal Instruments, Inc.
- Medical International Technologies
Bibliography
- PharmaJet, Inc. (2011, March 22). FDA grants PharmaJet 510(k) clearance on intradermal needle-free injection device.
- U.S. Food and Drug Administration. (2013, June). Technical considerations for pen, jet, and related injectors intended for use with drugs and biological products: Guidance for industry and FDA staff.
- Food and Drug Administration. (2013, June 7). Guidance for industry and FDA staff: Technical considerations for pen, jet, and related injectors intended for use with drugs and biological products; Availability. Federal Register.
- Malvolti, S., Ko, M., Menozzi-Arnaud, M., Mantel, C., Jarrahian, C., Amorij, J.-P., Giersing, B., & Hasso-Agopsowicz, M. (2023, June). Exploring potential applications of measles and rubella microarray patches (MR-MAPs): Use case identification. Frontiers in Public Health, 11.
- PharmaJet, Inc. (2022, April 27). PharmaJet presents partner data demonstrating superior immunogenicity with their needle-free systems at World Vaccine Congress. Business Wire.
This Report Answers
- The report explains where needle-free injection systems are used across product type and application. It also covers end-user and country demand.
- Segment analysis identifies the leading subsegments and the clinical and purchasing reasons providers prioritize them.
- Country analysis examines the listed markets and the immunization, reimbursement or research factors supporting device demand.
- Competitive analysis reviews current providers across powder-based, liquid-based and depot-based injectors. It also covers partnerships with drug and vaccine developers.
- Application analysis assesses how vaccination, chronic therapy and home use influence purchase decisions. It also considers device cost and regulatory requirements.
What does the powder-based, needle-free injection system market cover?
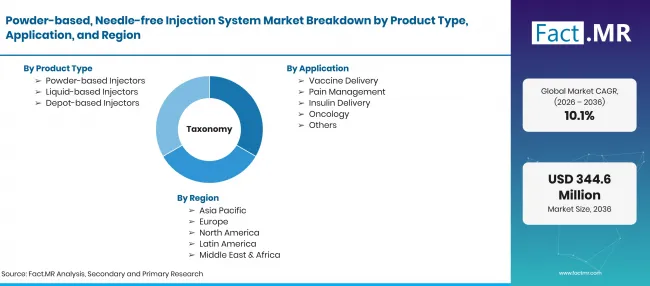
The market encompasses devices that deliver vaccines and drugs through the skin without a needle, spanning powder-based, liquid-based, and depot-based injectors.
The assessment examines vaccine delivery, pain management, insulin delivery, and oncology applications across hospitals, clinics, ambulatory surgical centers, and home care settings. Demand is analyzed by product type, application, and end user.
What falls within the scope?
The scope covers needle-free injection devices, together with their reusable and single-use components, supplied for powder, liquid, and depot formulations.
It also covers devices used in vaccine delivery, pain management, insulin delivery, and oncology that are purchased by hospitals, clinics, ambulatory surgical centers, and home care users.
What falls outside the scope?
The scope omits conventional needle syringes, pen injectors, and infusion pumps, as well as oral and inhaled drug delivery systems.
Vaccines and drugs themselves are likewise excluded, unless they are supplied as part of a combined drug-device product.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research involves discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations explore purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that shape broader market acceptance.
- Desk Research: Desk research draws on government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates are built from historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by cross-checking primary interviews against public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates track new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report’s scope and coverage?
Powder Based, Needle Free Injection System Market Company Share (13) | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD million in 2026 to USD million by 2036 at a CAGR |
| Market Definition | Needle-free injection systems that deliver vaccines and drugs through the skin using a pressure source such as gas or a spring, including powder-based, liquid-based and depot-based injectors. |
| Product Type | Powder-based Injectors; Liquid-based Injectors; Depot-based Injectors |
| Application | Vaccine Delivery; Pain Management; Insulin Delivery; Oncology |
| End-User | Hospitals; Clinics; Ambulatory Surgical Centers; Home Care Settings |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | United States; South Korea; United Kingdom; Germany; France; Belgium; Netherlands |
| Key Companies Profiled | PharmaJet, Inc.; Inovio Pharmaceuticals, Inc.; Halozyme Therapeutics; Crossject SA; Portal Instruments, Inc.; Medical International Technologies |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using immunization and treatment volumes; device shipments; product type mix; application demand; country adoption; and provider portfolio review. |
How is the market segmented?
-
By Product Type
- Powder-based Injectors
- Liquid-based Injectors
- Depot-based Injectors
-
By Application
- Vaccine Delivery
- Pain Management
- Insulin Delivery
- Oncology
-
By End-User
- Hospitals
- Clinics
- Ambulatory Surgical Centers
- Home Care Settings
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa