- Market Value (2025): USD 3.9 Bn
- Estimated Value (2026): USD 4.2 Bn
- Forecast Value (2036): USD 7.9 Bn
- CAGR (2026-2036): 6.6%
What is the Pharmaceutical Tube Non-BPA Coatings Market forecast to be worth by 2036?
USD 4.2 billion in 2026 to USD 7.9 billion by 2036 at a 6.6% CAGR.
- As per Fact.MR analysis, the pharmaceutical tube non-BPA coatings market reached USD 3.9 billion in 2025.
- Demand is projected to rise from USD 4.2 billion in 2026 to USD 7.9 billion by 2036.
- The market is forecast to record a 6.6% CAGR from 2026 to 2036 as tube makers qualify non-BPA internal coatings for drug-contact packaging.
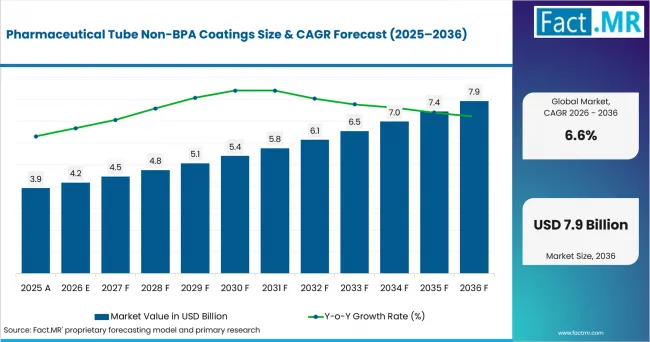
Pharmaceutical Tube Non Bpa Coatings Value Analysis | Source: Fact.MR
What are the defining numbers behind Pharmaceutical Tube Non-BPA Coatings Market growth?
An absolute opportunity of USD 3.7 billion is expected between 2026 and 2036.
- Demand Drivers in the Market
- Pharmaceutical tube coatings must stay firmly attached during tube shaping and sealing. Fact.MR finds similar requirements in metal packaging coatings, where strong bonding and product protection affect coating choice.
- New medicines increase packaging testing and approval work. In January 2026, the U.S. Food and Drug Administration reported that it approved 46 novel drugs in 2025 [1].
- Metal packaging companies use non-BPA coatings that work with existing coating and drying equipment without major changes to production settings.
- Corrosion resistance and product compatibility help the coating protect filled tubes during storage and regular handling.
- Key Segments Analyzed
- By Coating Chemistry: Polyester is expected to hold 34.0% share in 2026 because it stays flexible and sticks well to shaped metal packaging.
- By Package Type: Beverage cans are anticipated to account for 31.0% share in 2026 because non-BPA inner coatings are already widely used in can production.
- By Coating Position: Internal lining is forecast for represent 36.0% share in 2026 because it forms the main protective layer between the product and the metal.
- By Performance: Corrosion resistance is estimated to capture 29.0% share in 2026 because a damaged coating can leave the metal exposed to the product.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Demand for pharmaceutical tube non-BPA coatings is higher for products that limit migration and stick firmly to metal during production. Clear test results and production support also help suppliers make the approval process faster.”
- Strategic Implications
- Testing the coating with the actual product before changing the production line helps tube makers check whether it works properly.
- In January 2026, the European Medicines Agency reported that it recommended 104 medicines for marketing authorisation in 2025 [2]. New medicine approvals keep packaging reviews active, while coating makers provide migration, corrosion, and shaping test results for quality checks.
- Pharmaceutical packaging companies review coating changes along with the container and closure system. This keeps material changes controlled and easy to track. Fact.MR finds that product protection and regulatory requirements are also important across the wider pharmaceutical packaging market.
- During larger production runs, testing drying settings and coating thickness helps keep the coating even across the tube surface.
China is expected to grow at 7.8% CAGR through 2036 as pharmaceutical production increases packaging approval work. Japan follows at 6.7% as tube makers focus on consistent quality. The USA and France each record 6.3%, while Germany reaches 6.1% as pharmaceutical production supports coating changes and production testing.
How does the Pharmaceutical Tube Non-BPA Coatings Market break down by segment?
Polyester leads Coating Chemistry at 34.0%, while Beverage cans lead Package Type at 31.0%. Internal lining leads Coating Position at 36.0%, and Corrosion resistance leads Performance at 29.0%.
Which Coating Chemistry dominates?
Polyester is projected to hold 34.0% share in 2026.
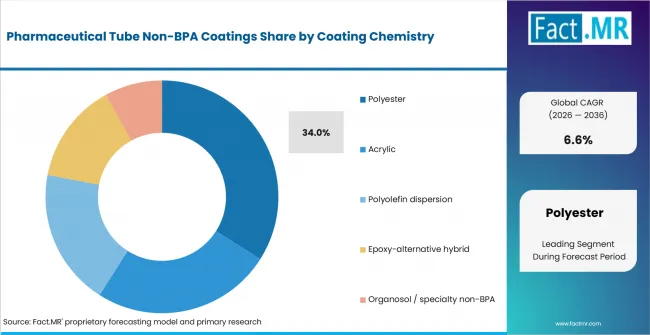
Pharmaceutical Tube Non Bpa Coatings Analysis By Coating Chemistry | Source: Fact.MR
Polyester is expected to lead because it stays flexible and sticks well to shaped metal packaging. Acrylic and polyolefin coatings are used for other packaging needs. As per Fact.MR analysis, good adhesion, chemical protection, and steady performance during production are also important when choosing packaging coatings.
What leads the Package Type segment?
Beverage cans are anticipated to account for 31.0% share in 2026.
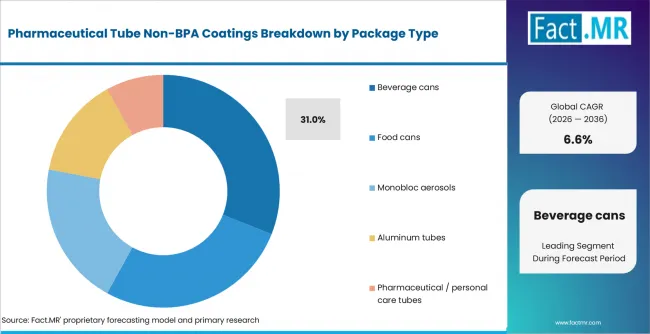
Pharmaceutical Tube Non Bpa Coatings Analysis By Package Type | Source: Fact.MR
Beverage cans are anticipated to hold 31.0% share because non-BPA inner coatings are already widely used in metal can production. Food cans and aerosols use similar protective coatings. Fact.MR finds that can coating systems include polyester, acrylic, polyolefin, and other coating types for metal containers.
How does Coating Position shape demand?
Internal lining is forecast to represent 36.0% share in 2026.
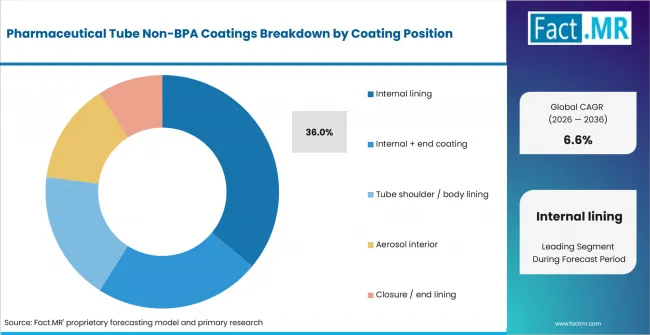
Pharmaceutical Tube Non Bpa Coatings Analysis By Coating Position | Source: Fact.MR
Internal linings are expected to lead because they form the main protective layer between the product and the metal. The coating also has to protect the tube body and shoulder after shaping. According to Fact.MR, tube packaging includes aluminum tubes for pharmaceutical products, making coating strength during shaping an important factor.
What supports Corrosion Resistance within Performance?
Corrosion resistance is estimated to capture 29.0% share in 2026.
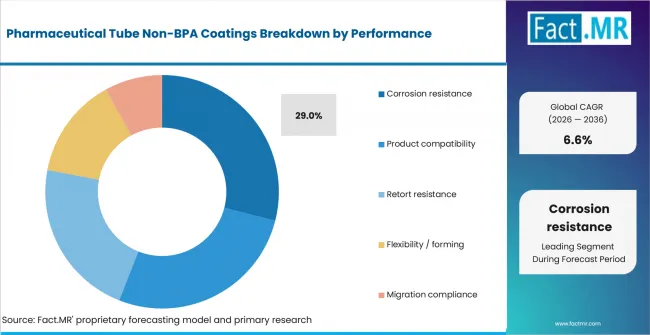
Pharmaceutical Tube Non Bpa Coatings Analysis By Performance | Source: Fact.MR
Corrosion resistance is expected to lead because a damaged coating can expose the metal to the product inside. Product compatibility and migration are also checked separately. Fact.MR finds that coating material and resistance are important when choosing protective coatings.
What is accelerating Pharmaceutical Tube Non-BPA Coatings Market adoption, and what is holding it back?
Demand is growing as companies move to non-BPA materials, approve new drug packaging, and use inner coatings to protect the product. Long testing periods, production line costs, and strict requirements for drug-contact packaging can slow growth.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Non-BPA chemistry substitution | +1.4% | North America, Europe, East Asia | Short term (<= 2 years) |
| Pharmaceutical manufacturing activity | +1.2% | Global | Medium term (2-4 years) |
| Internal barrier and corrosion requirements | +1.0% | Global | Short term (<= 2 years) |
| New drug and formulation introductions | +0.8% | USA, China, Europe, Japan | Medium term (2-4 years) |
| Tube and metal-packaging line upgrades | +0.6% | Global | Long term (>= 4 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Low-migration pharmaceutical tube coatings | +0.9% | North America, Europe, Japan | Medium term (2-4 years) |
| BPA-NI coating conversion on existing lines | +0.8% | Global | Short term (<= 2 years) |
| High-corrosion-resistance specialty formulations | +0.6% | Global | Medium term (2-4 years) |
| Regional technical-service approval support | +0.4% | East Asia, Europe, North America | Long term (>= 4 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Long approval and change-control cycles | -0.8% | Global | Medium term (2-4 years) |
| Performance trade-offs during chemistry substitution | -0.6% | Global | Short term (<= 2 years) |
| Inspection and records burden | -0.5% | USA, Europe, Japan | Short term (<= 2 years) |
| Price pressure in mature metal-packaging lines | -0.3% | Global | Long term (>= 4 years) |
Which countries are scaling the Pharmaceutical Tube Non-BPA Coatings Market through 2036?
- China will keep a 1.1-point lead over Japan, supported by pharmaceutical manufacturing and regular packaging approval work.
- Japan will remain 0.4 points ahead of the United States as controlled quality systems and pharmaceutical production support coating qualification.
- The United States and France will each record 6.3% CAGR, with U.S. growth supported by drug manufacturing and France supported by active pharmaceutical production and packaging quality requirements.
- France will remain 0.2 points ahead of Germany, where pharmaceutical production and strict process control support demand for stable coating performance.
- Germany will close the range at 6.1% CAGR, supported by pharmaceutical production and careful control of coating quality during tube forming.
Comparable CAGRs create different entry conditions because pharmaceutical production, packaging approval, product-contact requirements, and coating qualification vary by country. Full report coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, and Middle East & Africa.
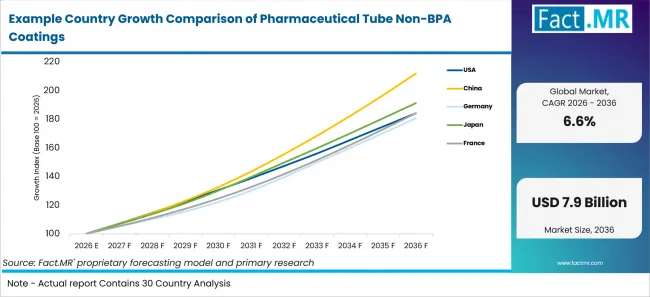
Example Country Growth Comparison Of Pharmaceutical Tube Non Bpa Coatings | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| China | 7.8% |
| Japan | 6.7% |
| USA | 6.3% |
| France | 6.3% |
| Germany | 6.1% |
What supports China adoption?
7.8% CAGR, supported by drug manufacturing and new medicine activity.
China has a large pharmaceutical industry, which creates regular packaging testing and approval work. In January 2026, China’s National Bureau of Statistics reported that medicine manufacturing enterprises above the designated size recorded CNY 2,487.0 billion in operating revenue in 2025 [3]. The market is expected to grow at 7.8% CAGR through 2036 as tube makers test and approve non-BPA inner coatings for corrosion protection, product safety, and strength during shaping.
How is Japan scaling demand?
6.7% CAGR, supported by domestic pharmaceutical production and controlled quality systems.
Japanese pharmaceutical packaging companies focus on consistent coating quality and clear test results. In December 2025, the Ministry of Health, Labour and Welfare reported that domestic pharmaceutical production reached JPY 10.2485 trillion in 2024 [4]. The market is anticipated to grow at 6.7% CAGR through 2036 as tube makers check migration, adhesion, and coating strength during tube shaping before approval.
What supports USA adoption?
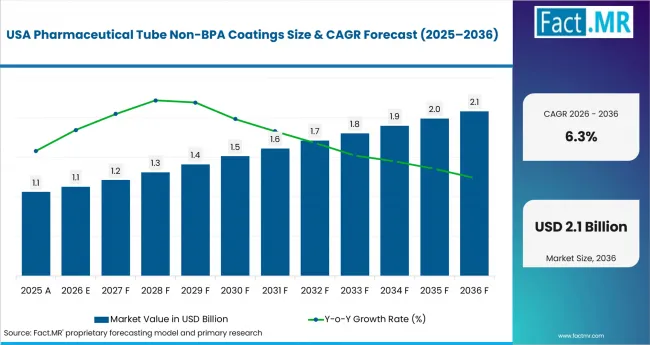
6.3% CAGR, supported by a large drug-manufacturing base and regular packaging approval.
Pharmaceutical Tube Non Bpa Coatings Country Value Analysis | Source: Fact.MR
The large U.S. drug manufacturing industry creates regular packaging testing and approval work. In June 2026, the FDA reported that its FY2025 CDER Site Catalog included 3,375 drug manufacturing sites in the United States [5]. The market is anticipated to capture 6.3% CAGR through 2036 as packaging companies test non-BPA inner coatings for aluminum tubes and safe product contact.
How is France developing demand?
6.3% CAGR, supported by active pharmaceutical production and packaging quality requirements.
France has a large pharmaceutical industry that supports demand for approved packaging materials. In September 2026, Insee reported that the pharmaceutical preparations production index reached 123.38 in July 2025 [6]. The market is projected to account for 6.3% CAGR through 2036 as French packaging companies test inner coatings for production use, corrosion protection, and product compatibility.
What supports Germany adoption?
6.1% CAGR, supported by pharmaceutical production and disciplined process control.
German pharmaceutical and packaging companies follow strict production checks, making consistent coating quality important. In July 2025, Destatis reported that pharmaceutical production increased 10.0% in May 2025 from the previous month [7]. The market is expected to lead with 6.1% CAGR through 2036 as packaging companies choose coatings that dry evenly and stay strong after tube shaping.
Who leads the Pharmaceutical Tube Non-BPA Coatings Market?
PPG Industries, AkzoNobel, and Sherwin-Williams offer several non-BPA coatings for metal packaging and provide technical support. ACTEGA also supplies coatings and related products for metal packaging.
In April 2026, ACTEGA announced that it would present ACTNext® and ACTEcoat® coatings at METPACK 2026. The company focused on coating quality, regulatory requirements, sustainability, and production efficiency.
Buyers compare coating quality, ease of use, strength during shaping, regulatory requirements, and technical support before moving from testing to regular production.
Which companies are the key providers?
Key companies include PPG Industries; AkzoNobel; Sherwin-Williams, including Valspar heritage; and ACTEGA.
- PPG Industries
- AkzoNobel
- Sherwin-Williams (including Valspar heritage)
- ACTEGA
Bibliography
- [1] U.S. Food and Drug Administration. (2026, January). Advancing Health Through Innovation: New Drug Therapy Approvals 2025.
- [2] European Medicines Agency. (2026, January 15). Human medicines in 2025.
- [3] National Bureau of Statistics of China. (2026, January 28). Profit of Industrial Enterprises above the Designated Size in 2025.
- [4] Ministry of Health, Labour and Welfare, Japan. (2025, December 24). [Publication of the 2024 Pharmaceutical Industry Production Statistics Annual Report].
- [5] U.S. Food and Drug Administration. (2026). FY 2025 Report on the State of Pharmaceutical Quality.
- [6] Institut national de la statistique et des études économiques (Insee). (2026, September 9). Raw industrial production index (base 100 in 2021) – Manufacture of pharmaceutical preparations (NAF rev. 2, level Group, item 21.2).
- [7] Statistisches Bundesamt (Destatis). (2025, July 7). Production in May 2025: +1.2% on the previous month.
- [8] ACTEGA. (2026, April 2). ACTEGA to Showcase Next-Generation Metal Packaging Solutions at METPACK 2026.
This Report Answers
- The report explains how non-BPA coatings are assessed by chemistry, package type, coating position and performance.
- Segment analysis identifies the leading subsegment and 2026 share within each parent segment.
- Country analysis compares China, Japan, USA, France and Germany using the listed CAGR values and official evidence.
- Competitive analysis reviews active coating suppliers serving metal packaging, tubes or related regulated packaging uses.
- Technical analysis explains why corrosion resistance, forming flexibility, product fit and migration control shape coating approval.
What does the Pharmaceutical Tube Non-BPA Coatings Market cover?
The market covers non-BPA coatings applied to pharmaceutical tubes and related metal-packaging structures where an internal film protects the packed product from the metal. According to Fact.MR analysis, adjacent medical packaging uses the same focus on product protection and controlled material performance. The core boundary remains the coating layer itself, including the way it bonds to the tube and keeps the packed formulation away from direct contact with the metal surface.
What is included in the scope?
The scope includes non-BPA coating systems used on metal tubes and the listed adjacent package formats. It covers chemistry, coating position and performance. According to Fact.MR analysis, non-contact barrier coating systems provide useful adjacent context for coating control across different substrates and application methods. Within this report, the main focus stays on the internal protective film used on pharmaceutical tubes and on the line conditions that shape its final performance.
What is excluded from the scope?
The scope excludes uncoated tubes, stand-alone adhesives and decorative-only printing inks. Raw materials sold without a protective coating function fall outside the revenue boundary. These items belong to separate packaging material groups and are reviewed only when they affect coating use on pharmaceutical tubes.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report’s scope and coverage?
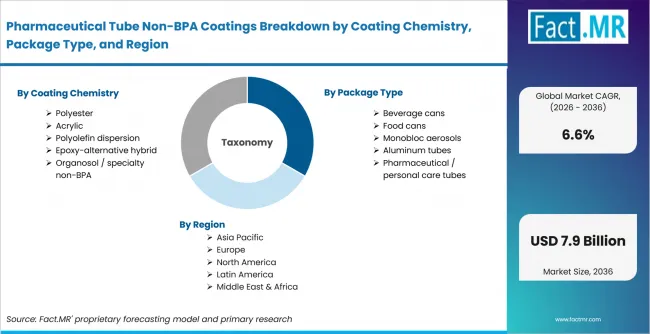
Pharmaceutical Tube Non Bpa Coatings Breakdown By Coating Chemistry, Package Type, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Non-BPA coatings used as protective and functional layers in pharmaceutical tubes and related metal-packaging formats where the coating separates the packed product from the metal substrate. |
| Coating Chemistry | Polyester; Acrylic; Polyolefin dispersion; Epoxy-alternative hybrid; Organosol / specialty non-BPA |
| Package Type | Beverage cans; Food cans; Monobloc aerosols; Aluminum tubes; Pharmaceutical / personal care tubes |
| Coating Position | Internal lining; Internal + end coating; Tube shoulder / body lining; Aerosol interior; Closure / end lining |
| Performance | Corrosion resistance; Product compatibility; Retort resistance; Flexibility / forming; Migration compliance |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | China; Japan; USA; France; Germany |
| Key Companies Profiled | PPG Industries; AkzoNobel; Sherwin-Williams (including Valspar heritage); ACTEGA |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using market values and shares, drug manufacturing activity, coating approval logic, company portfolio validation, country growth, and first-hand regulatory or statistical evidence. |
How is the market segmented?
-
By Coating Chemistry:
- Polyester
- Acrylic
- Polyolefin dispersion
- Epoxy-alternative hybrid
- Organosol / specialty non-BPA
-
By Package Type:
- Beverage cans
- Food cans
- Monobloc aerosols
- Aluminum tubes
- Pharmaceutical / personal care tubes
-
By Coating Position:
- Internal lining
- Internal + end coating
- Tube shoulder / body lining
- Aerosol interior
- Closure / end lining
-
By Performance:
- Corrosion resistance
- Product fit
- Retort resistance
- Flexibility / forming
- Migration compliance
-
By Region:
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa