- Market Value (2025): USD 1.1 Bn
- Estimated Value (2026): USD 1.2 Bn
- Forecast Value (2036): USD 2.4 Bn
- CAGR (2026-2036): 7.2%
What is the Radiochemical Synthesizers Market forecast to be worth by 2036?
USD 2.4 billion by 2036, at a 7.2% CAGR.
- The Radiochemical Synthesizers Market reached approximately USD 1.1 billion in 2025.
- Demand is projected to increase from USD 1.2 billion in 2026 to USD 2.4 billion by 2036.
- The market is forecast to expand at a 7.2% CAGR from 2026 to 2036.
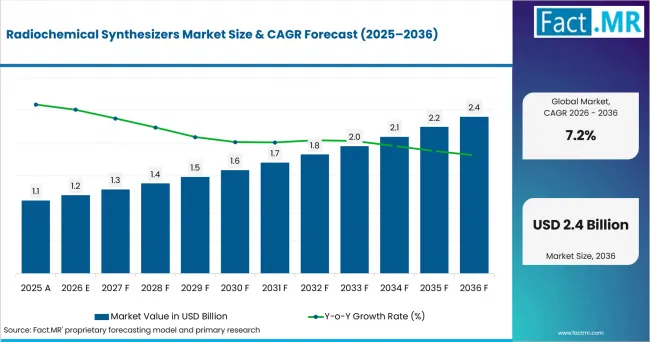
Radiochemical Synthesizers Market Value Analysis | Source: Fact.MR
What are the defining numbers behind Radiochemical Synthesizers Market growth?
An absolute opportunity of USD 1.2 billion is expected between 2026 and 2036.
- Demand Drivers in the Market
- Growth in PET radiopharmaceutical production is increasing demand for automated synthesis systems that control reagent addition, heating, purification and formulation within short radionuclide half-lives. IAEA guidance identifies automated and cassette-based modules as established tools for PET tracer production.
- Expansion of PSMA imaging and theranostic treatment is widening the range of radiochemistry performed by hospitals and radiopharmacies. Facilities increasingly require systems that can support different radionuclides and synthesis sequences without rebuilding the complete production workflow.
- GMP requirements support closed and reproducible synthesis processes. FDA, EMA and MHRA guidance places emphasis on controlled manufacturing, documentation and quality systems for radiopharmaceutical production, increasing demand for platforms that support standardized recipes and traceable production.
- Growing use of targeted radionuclide therapy is extending demand beyond conventional FDG production. Diagnostic and therapeutic programs increasingly require flexible synthesis capability for gallium, lutetium and other radiolabelled compounds.
- Radiopharmacy networks also create recurring demand for cassettes, reagent kits, maintenance and software support after equipment installation, increasing the commercial importance of lifecycle services.
- Key Segments Analyzed
- Automated Radiochemical Synthesizers account for 63.5% of Product in 2026, supported by reproducible synthesis, reduced operator handling and compatibility with validated production workflows.
- Fluorine Based Isotopes hold 41.8% of Radioisotope in 2026, reflecting the established production base for F-18 tracers and continued use of FDG across PET imaging.
- Positron Emission Tomography accounts for 44.6% of Application in 2026 because routine oncology imaging and expanding targeted tracer use require frequent radiopharmaceutical synthesis.
- Hospitals represent 33.7% of End Use in 2026 because nuclear medicine, oncology and radiopharmacy activities are frequently coordinated within hospital-based treatment networks.
- Equipment Sales account for 48.2% of Service Model in 2026 as new radiopharmacy installations and replacement cycles continue to create direct capital-equipment demand.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Radiochemical synthesizers are increasingly being evaluated as production platforms rather than stand-alone laboratory instruments. Buyers require reproducible chemistry, dependable uptime and documented workflows that can support both routine tracer production and expansion into new radiopharmaceutical programs.”
- Strategic Implications
- Radiochemical synthesizer manufacturers should design platforms around defined production environments. Routine PET centers prioritize repeatability and rapid setup, while research institutions require greater chemistry flexibility.
- Consumable availability should be treated as part of the equipment proposition. Cassette, reagent and fluid-path continuity directly affects whether installed systems can remain operational.
- Suppliers serving theranostic programs should support multiple isotope families and validated method transfer as diagnostic and therapeutic radiopharmaceutical workflows become more closely linked.
- Service coverage can influence purchasing decisions because radiopharmaceutical production is time-sensitive. Preventive maintenance and rapid technical support reduce the risk of cancelled production runs.
How does the Radiochemical Synthesizers Market break down by segment?
The market is segmented by Product, Radioisotope, Application, End Use and Service Model.
Why do Automated Radiochemical Synthesizers lead Product?
Automated Radiochemical Synthesizers are projected to account for a 63.5% share in 2026.
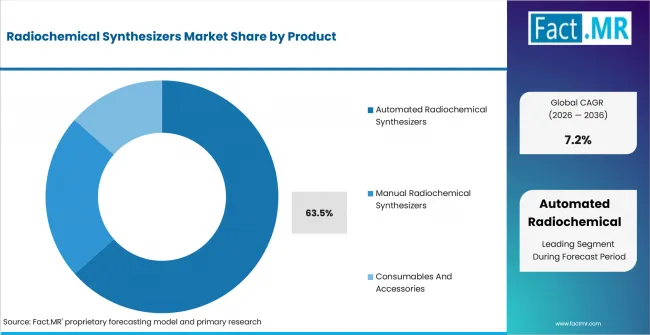
Radiochemical Synthesizers Market Analysis By Product | Source: Fact.MR
Automated platforms reduce manual handling during time-sensitive radiochemical synthesis while improving consistency between production batches. Their controlled sequences also help facilities standardize reagent addition, heating, purification and transfer.
Cassette-based systems are particularly suited to routine production because disposable fluid paths can simplify setup and reduce carryover between batches. Research laboratories may continue using more configurable systems when chemistry flexibility takes priority over standardized throughput.
IAEA technical material describes automated PET radiochemistry modules across cassette-based and other system architectures, supporting their role in routine radiopharmaceutical production.
Why do Fluorine Based Isotopes lead Radioisotope?
Fluorine Based Isotopes are projected to account for a 41.8% share in 2026.
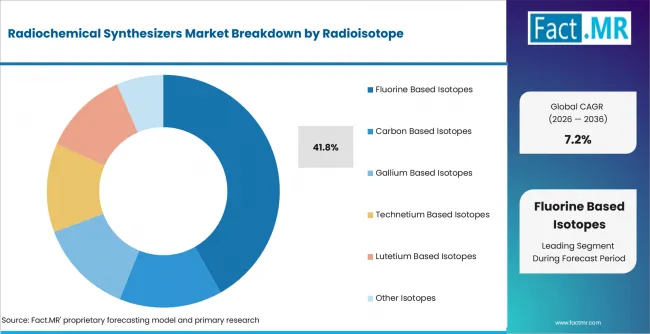
Radiochemical Synthesizers Market Analysis By Radioisotope | Source: Fact.MR
The segment benefits from the established production infrastructure surrounding F-18 radiopharmaceuticals. FDG remains widely used for PET imaging, while newer F-18-labelled tracers are extending fluorine chemistry into additional oncology and molecular-imaging applications.
F-18 also offers a practical production and distribution window compared with radionuclides having much shorter half-lives. This supports both hospital radiopharmacies and regional production facilities serving several imaging locations.
Why does Positron Emission Tomography lead Application?
Positron Emission Tomography is projected to account for a 44.6% share in 2026.
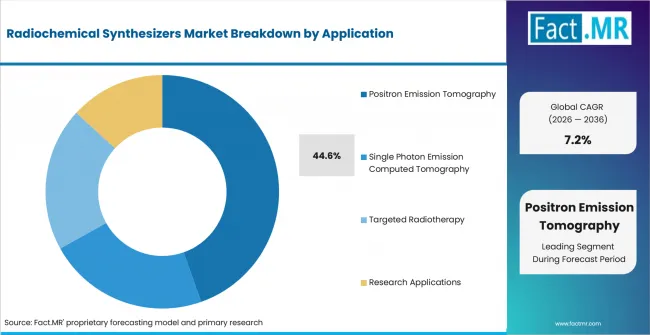
Radiochemical Synthesizers Market Analysis By Application | Source: Fact.MR
PET leads because radiotracers are routinely produced for oncology imaging and selected cardiology and neurological applications. Expanding use of target-specific tracers adds further synthesis requirements beyond conventional FDG.
CMS recognizes PET with approved radiopharmaceuticals across specified clinical indications. Growth in PSMA-linked diagnostic pathways also increases demand for reliable production of targeted PET tracers.
Why do Hospitals lead End Use?
Hospitals are projected to account for a 33.7% share in 2026.
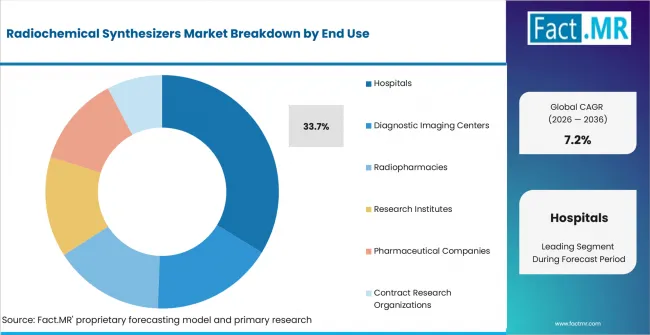
Radiochemical Synthesizers Market Analysis By End Use | Source: Fact.MR
Hospitals combine nuclear medicine with oncology services and specialist pharmacy infrastructure, allowing radiopharmaceutical production to be coordinated closely with patient scheduling.
Academic medical centers may also operate radiochemistry facilities for clinical trials and new tracer programs. This makes synthesizer flexibility valuable alongside routine production capacity.
Why do Equipment Sales lead Service Model?
Equipment Sales are projected to account for a 48.2% share in 2026.
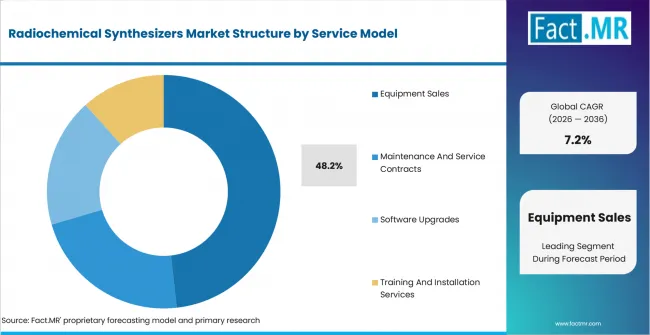
Radiochemical Synthesizers Market Analysis By Service Model | Source: Fact.MR
Equipment purchases remain central because radiopharmacy expansion and replacement cycles require new synthesis hardware. Facilities adding tracer capacity may also need dedicated systems where chemistries or production schedules cannot be accommodated on existing modules.
The installed base subsequently generates demand for maintenance, training, software upgrades and consumables. Equipment sales therefore often establish a longer service relationship between the supplier and radiopharmacy.
What is accelerating Radiochemical Synthesizers Market adoption, and what is holding it back?
Adoption is being supported by expanding PET and theranostic radiopharmaceutical production together with the need for controlled GMP workflows. Growth can be constrained by radiopharmacy infrastructure costs, radionuclide availability and the validation burden associated with new chemistry.
Drivers Impact Analysis
| Factor | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of PET radiopharmaceutical production | +1.6% | Global | Short term (≤ 2 years) |
| Growth in PSMA imaging and theranostic applications | +1.4% | USA, Germany, UK and Japan | Short term (≤ 2 years) |
| GMP-driven shift toward automated synthesis workflows | +1.1% | USA, Europe and Japan | Medium term (2–4 years) |
| Expansion of targeted radionuclide therapy | +0.9% | Global | Medium term (2–4 years) |
| Recurring demand for cassettes and lifecycle services | +0.6% | Global | Long term (≥ 4 years) |
Opportunity Impact Analysis
| Factor | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Multi-tracer synthesis platforms | +1.0% | Global | Medium term (2–4 years) |
| Theranostic radiochemistry expansion | +0.8% | USA, Germany, UK and Japan | Medium term (2–4 years) |
| Research-to-GMP method transfer | +0.7% | USA, Germany and Japan | Long term (≥ 4 years) |
| Maintenance, software and consumables revenue | +0.5% | Global | Long term (≥ 4 years) |
Restraints Impact Analysis
| Factor | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High radiopharmacy infrastructure requirements | -1.1% | Global | Short term (≤ 2 years) |
| Validation and regulatory complexity | -0.9% | USA, Europe and Japan | Short term (≤ 2 years) |
| Radionuclide and generator supply interruptions | -0.7% | Global | Medium term (2–4 years) |
| Platform limitations across different radiochemistry workflows | -0.5% | Global | Long term (≥ 4 years) |
Which countries are scaling the Radiochemical Synthesizers Market through 2036?
- Germany: Demand is supported by an established nuclear-medicine research environment and development of automated GMP-compatible radiopharmaceutical production. DKFZ activities in PET tracers and theranostics support demand for flexible synthesis platforms.
- Brazil: Domestic radiopharmaceutical production and nuclear-medicine infrastructure create demand for regional synthesis capacity, particularly where short radionuclide half-lives require production close to clinical sites.
- USA: A mature PET network and continuing introduction of targeted imaging and therapeutic radiopharmaceuticals support equipment used across academic centers and commercial radiopharmacies.
- UK: NHS PET-CT services and formal radiopharmacy manufacturing requirements create ongoing demand for synthesis systems that operate within pharmaceutical quality frameworks.
- Japan: Development of PSMA-PET and other radiopharmaceutical applications supports demand for documented synthesis platforms compatible with the country's medical-device and pharmaceutical requirements.
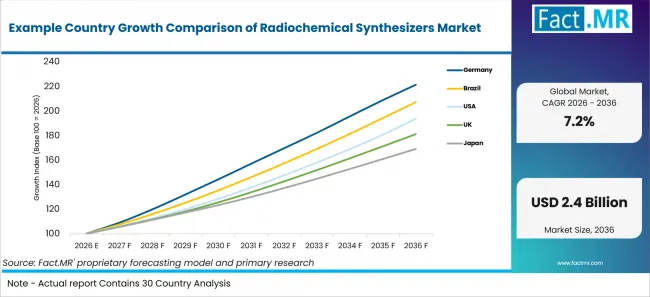
Example Country Growth Comparison Of Radiochemical Synthesizers Market | Source: Fact.MR
| Country | CAGR |
|---|---|
| Germany | 8.3% |
| Brazil | 7.6% |
| USA | 6.8% |
| UK | 6.1% |
| Japan | 5.4% |
What is driving Germany’s growth through 2036?
Germany is forecast to expand at an 8.3% CAGR from 2026 to 2036.
Growth is supported by the country's nuclear-medicine research infrastructure and its capacity to translate new radiotracers into controlled production workflows.
The German Cancer Research Center describes work involving GMP-compliant automated radiopharmaceutical production and suitable synthesis modules. Research activity in PET tracers and theranostic radiopharmaceuticals increases demand for platforms capable of supporting method development followed by repeatable clinical production.
What is driving Brazil’s growth through 2036?
Brazil is forecast to expand at a 7.6% CAGR from 2026 to 2036.
Brazil has an established base of nuclear-medicine services and domestic radiopharmaceutical production. CNEN information identifies multiple facilities involved in radioisotope and radiopharmaceutical activity.
The country's geographic scale also increases the importance of regional production for short-lived radiopharmaceuticals. This supports equipment installations together with demand for maintenance and consumables.
What is driving USA’s growth through 2036?
The USA is forecast to expand at a 6.8% CAGR from 2026 to 2036.
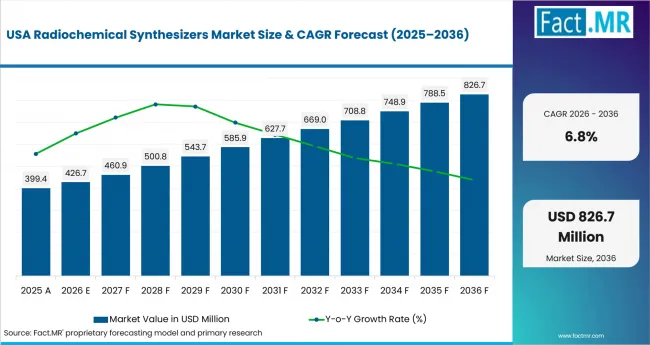
Radiochemical Synthesizers Market Country Value Analysis | Source: Fact.MR
Growth is supported by established PET infrastructure and continuing development of targeted radiopharmaceuticals. FDA approvals associated with PSMA imaging and radionuclide therapy are broadening clinical workflows linked to radiochemistry.
Academic institutions require synthesis flexibility for research, while commercial radiopharmacies place greater emphasis on throughput and repeatability. This creates demand for different platform configurations within the same national market.
What is driving the UK’s growth through 2036?
The UK is forecast to expand at a 6.1% CAGR from 2026 to 2036.
NHS England commissions PET-CT as a specialized service, while UK radiopharmacy production operates within formal pharmaceutical manufacturing requirements.
This environment supports demand for systems that provide repeatable synthesis and documentation while fitting established GMP procedures. Equipment uptime is particularly important where short-lived radiopharmaceutical batches are linked to scheduled patient scans.
What is driving Japan’s growth through 2036?
Japan is forecast to expand at a 5.4% CAGR from 2026 to 2036.
Japan's regulatory framework recognizes radiopharmaceutical synthesizers within its medical-device system, while development pathways for new radiopharmaceuticals continue to evolve.
Expansion of PSMA-PET and other targeted imaging applications can increase demand for compact and well-documented synthesis systems capable of supporting additional radiochemical methods.
Who Leads the Radiochemical Synthesizers Market?
Key players in the Radiochemical Synthesizers Market include GE HealthCare, Eckert & Ziegler, IBA Radiopharma Solutions, Siemens Healthineers, Comecer, Sumitomo Heavy Industries and Advion.
Competition depends on synthesis flexibility, installed equipment base and the ability to support regulated production environments. Buyers also assess cassette availability, software controls and service response when selecting a platform.
Integrated healthcare technology suppliers can connect synthesis equipment with broader nuclear-medicine workflows, while specialist radiopharmacy-equipment companies compete through application-specific system design and hot-cell compatibility.
Consumables and lifecycle support are important because an installed synthesizer depends on continuing access to cassettes and compatible reagents. Method-transfer capability can also influence supplier selection when a radiopharmacy adds a new tracer.
Which companies are the key providers?
Key players in the Radiochemical Synthesizers Market include GE HealthCare, Eckert & Ziegler, IBA Radiopharma Solutions, Siemens Healthineers, Comecer, Sumitomo Heavy Industries and Advion.
- GE HealthCare
- Eckert & Ziegler
- IBA Radiopharma Solutions
- Siemens Healthineers
- Comecer
- Sumitomo Heavy Industries
- Advion
Bibliography
- International Atomic Energy Agency. Automated Radiochemistry and Radiopharmaceutical Production Guidance. IAEA.
- U.S. Food and Drug Administration. PET Drug Products: Current Good Manufacturing Practice. U.S. Department of Health and Human Services.
- U.S. Food and Drug Administration. Regulatory Updates for PSMA-Targeted PET and Radiopharmaceutical Therapy. U.S. Department of Health and Human Services.
- Centers for Medicare & Medicaid Services. Positron Emission Tomography Coverage Materials. U.S. Department of Health and Human Services.
- European Medicines Agency. Guideline on Radiopharmaceuticals. European Medicines Agency.
- UK Medicines and Healthcare products Regulatory Agency. Guidance on Diagnostic Radiopharmaceutical Investigational Products and GMP Requirements. Government of the United Kingdom.
- NHS England. PET-CT Specialised Commissioning Information. NHS England.
- Comissão Nacional de Energia Nuclear. Radiopharmaceutical Production and Nuclear Medicine Services. Government of Brazil.
- Pharmaceuticals and Medical Devices Agency. Radiopharmaceutical and Radiopharmaceutical Synthesizer Regulatory Information. Government of Japan.
- German Cancer Research Center. Radiotracer and Theranostic Radiopharmaceutical Research. DKFZ.
This Report Answers
- What factors are increasing demand for automated radiochemical synthesis?
- How are PET and theranostic applications affecting equipment requirements?
- Why are closed production workflows gaining use in regulated radiopharmacies?
- How does radionuclide availability influence synthesizer utilization?
- What factors influence equipment selection by hospitals and radiopharmacies?
- How do requirements differ between routine production and research environments?
- What competitive capabilities influence supplier selection?
What does the Radiochemical Synthesizers Market cover?
The Radiochemical Synthesizers Market covers commercial revenue from equipment and associated components used to prepare radiopharmaceuticals through controlled radiochemical synthesis.
Revenue includes automated and manual synthesis platforms, associated consumables and the defined service models used across PET, SPECT, targeted radiotherapy and research applications.
What is included in the scope?
Product includes Automated Radiochemical Synthesizers, Manual Radiochemical Synthesizers and Consumables And Accessories together with their applicable subcategories.
Radioisotope coverage includes Fluorine Based Isotopes, Carbon Based Isotopes, Gallium Based Isotopes, Technetium Based Isotopes, Lutetium Based Isotopes and Other Isotopes.
Application includes Positron Emission Tomography, Single Photon Emission Computed Tomography, Targeted Radiotherapy and Research Applications.
End Use includes Hospitals, Diagnostic Imaging Centers, Radiopharmacies, Research Institutes, Pharmaceutical Companies and Contract Research Organizations.
Service Model includes Equipment Sales, Maintenance And Service Contracts, Software Upgrades and Training And Installation Services.
What is excluded from the scope?
The scope excludes diagnostic imaging scanners when sold independently of radiochemical synthesis equipment.
Cyclotrons and standalone radionuclide-production systems are excluded unless their commercial value forms part of the defined synthesizer transaction.
Finished radiopharmaceutical sales are outside the market because the assessment measures synthesis equipment, associated consumables and the specified service models rather than downstream drug revenue.
General laboratory equipment without a defined radiochemical synthesis function is also excluded.
How Was the Analysis Built?
The analysis draws on public and technical evidence together with company and industry inputs relevant to radiopharmaceutical synthesis.
- Primary Research: Interviews cover radiopharmacy managers, nuclear-medicine departments, radiochemists, equipment suppliers, hospital procurement teams, pharmaceutical developers and research institutions. Discussions examine synthesis throughput, tracer mix, validation requirements, equipment utilization and service needs.
- Desk Research: The review includes material from nuclear and pharmaceutical regulators, public health systems, nuclear-medicine organizations, research institutions and company technical documentation.
- Market Sizing and Forecasting: The assessment considers synthesizer installations, replacement requirements, tracer-production activity, equipment pricing, isotope mix, consumable use and service requirements across the defined customer base.
- Data Validation and Update Cycle: Findings are cross-checked against regulatory developments, radiopharmaceutical approvals, nuclear-medicine infrastructure and current supplier activity. Updates account for changes in tracer adoption, isotope availability and production technology.
What is the report's scope and coverage?
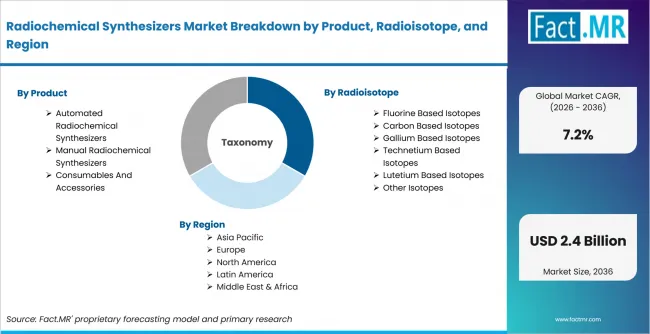
Radiochemical Synthesizers Market Breakdown By Product, Radioisotope, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Radiochemical synthesis equipment, associated consumables and defined services used in radiopharmaceutical production |
| Segments Covered | Product; Radioisotope; Application; End Use; Service Model |
| Regions Covered | Asia Pacific; Europe; North America; Latin America; Middle East & Africa |
| Countries Covered | Germany; Brazil; USA; UK; Japan |
| Key Companies Profiled | GE HealthCare; Eckert & Ziegler; IBA Radiopharma Solutions; Siemens Healthineers; Comecer; Sumitomo Heavy Industries; Advion |
| Forecast Period | 2026 to 2036 |
| Base Year | 2025 |
| Market Value, 2026 | USD 1.2 billion |
| Market Value, 2036 | USD 2.4 billion |
| CAGR, 2026-2036 | 7.2% |
| Absolute Opportunity | USD 1.2 billion |
| Approach | Hybrid top-down and bottom-up assessment using synthesizer installations, tracer-production activity, isotope mix, equipment pricing, replacement demand, consumable use and service requirements |
How is the market segmented?
-
By Product
- Automated Radiochemical Synthesizers
- Cassette Based Synthesizers
- Modular Synthesizers
- Compact Bench Top Synthesizers
- High Throughput Synthesizers
- Manual Radiochemical Synthesizers
- Semi Automated Systems
- Conventional Synthesis Systems
- Consumables And Accessories
- Synthesis Cassettes
- Reaction Vials
- Reagent Kits
- Fluid Transfer Components
- Automated Radiochemical Synthesizers
-
By Radioisotope
- Fluorine Based Isotopes
- FDG Synthesis
- PSMA Synthesis
- Carbon Based Isotopes
- Methionine Labeling
- Acetate Labeling
- Gallium Based Isotopes
- PSMA Applications
- DOTATATE Applications
- Technetium Based Isotopes
- Cardiology Imaging
- Bone Imaging
- Lutetium Based Isotopes
- Targeted Radiotherapy
- Theranostic Applications
- Other Isotopes
- Iodine 123
- Copper 64
- Fluorine Based Isotopes
-
By Application
- Positron Emission Tomography
- Oncology Imaging
- Neurology Imaging
- Cardiology Imaging
- Single Photon Emission Computed Tomography
- Cardiac Imaging
- Bone Imaging
- Targeted Radiotherapy
- Cancer Therapy
- Precision Medicine
- Research Applications
- Preclinical Research
- Clinical Research
- Positron Emission Tomography
-
By End Use
- Hospitals
- Diagnostic Imaging Centers
- Radiopharmacies
- Research Institutes
- Pharmaceutical Companies
- Contract Research Organizations
-
By Service Model
- Equipment Sales
- Maintenance And Service Contracts
- Software Upgrades
- Training And Installation Services