- Market Value (2025): USD 2.2 Bn
- Estimated Value (2026): USD 2.4 Bn
- Forecast Value (2036): USD 5.9 Bn
- CAGR (2026-2036): 9.5%
What is the Sugar-Free Gummy Bases Market forecast to be worth by 2036?
USD 2.4 billion in 2026 to USD 5.9 billion by 2036 at a 9.5% CAGR.
- The Sugar-Free Gummy Bases Market reached USD 2.2 billion in 2025.
- Demand is projected to increase from USD 2.4 billion in 2026 to USD 5.9 billion by 2036.
- The market is forecast to record 9.5% CAGR from 2026 to 2036 as nutraceutical gummy brands and confectionery manufacturers reformulate sweet, chewy formats around lower sugar claims.
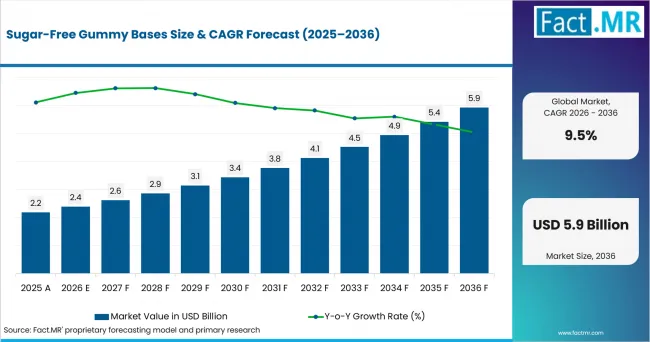
Sugar Free Gummy Bases Value Analysis | Source: Fact.MR
What are the defining numbers behind Sugar-Free Gummy Bases Market growth?
An absolute opportunity of USD 3.5 billion is expected between 2026 and 2036.
- Demand Drivers in the Market
- Nutraceutical gummy brands need bases that carry vitamins and botanicals while keeping the finished product aligned with sugar-free positioning.
- Confectionery manufacturers need texture systems that rebuild chew after sugar removal changes water activity and gel strength.
- USDA ERS reported in June 2026 that total U.S. food spending reached USD 2.51 trillion in 2025. Reduced-sugar snack reformulation can draw from that large packaged-food base.
- Private-label manufacturers need stable demolding and fast-setting textures so sugar-free recipes can move across existing gummy lines with fewer process changes.
- Key Segments Analyzed
- By Gelling Base: Pectin is projected to hold 37.0% share in 2026 because fruit-positioned and vegetarian gummies need plant-derived gel formation.
- By Sweetener System: Polyols are anticipated to account for 33.0% share in 2026 due to their role in replacing sucrose bulk and sweetness.
- By Application: Nutraceutical gummies are estimated to capture 34.0% share in 2026 owing to daily supplement formats that need measured active loading.
- By Texture Target: Soft chew is forecast to represent 31.0% share in 2026 since adult wellness and children's nutrition gummies need easy bite quality.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, "Sugar-free gummy bases are no longer a simple sweetener swap. The hard work is texture, water control and claim-safe labeling in one formula. Suppliers that combine pectin, polyol balance and process support are expected to win repeat briefs from supplement and confectionery formulators."
- Strategic Implications
- Ingredient suppliers should document gel strength, set time and storage behavior for each pectin and multi-hydrocolloid sugar-free base system.
- Contract manufacturers should test polyol tolerance and serving size before moving children's nutrition gummies into commercial batches.
- Confectionery teams should protect taste and demolding performance before lowering sugar further in mass-market gummy products.
China is projected to post 10.9% CAGR through 2036, supported by online food retail and national nutrition guidance. The USA is forecast to record 10.4% CAGR because supplement use sustains sugar-free nutraceutical formats. Germany is anticipated to advance at 10.2% CAGR through reduced-sugar taste familiarity. Japan is estimated to grow at 9.3% CAGR as ageing consumers favor easy-chew wellness formats. France is expected to post 8.9% CAGR while pharmacy-led supplement use supports measured expansion.
How does the Sugar-Free Gummy Bases Market break down by segment?
Pectin leads Gelling Base at 37.0%; polyols lead Sweetener System at 33.0%.
Which Gelling Base dominates?
Pectin holds 37.0% share in 2026.
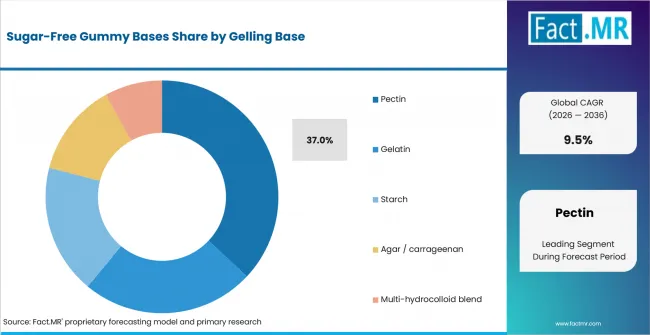
Sugar Free Gummy Bases Analysis By Gelling Base | Source: Fact.MR
Pectin is expected to lead gelling base demand because it gives formulators a plant-derived structure for fruit-positioned and vegetarian gummies. It helps manage clarity and bite when sugar removal weakens the gel network normally created by sucrose. IFF announced in April 2025 that GRINDSTED Pectin Premium supports plant-based dietary supplement gummies at Vitafoods Europe 2025. That product focus matches sugar-free bases that need clean chew and stable container behavior.
What leads the Sweetener System segment?
Polyols account for 33.0% share in 2026.
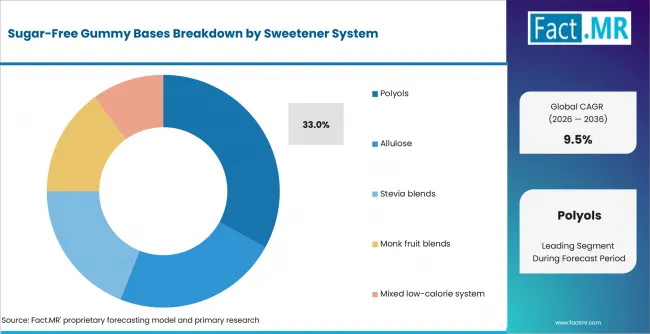
Sugar Free Gummy Bases Analysis By Sweetener System | Source: Fact.MR
Polyols are projected to account for the lead share because sugar-free gummies still need bulk and chew after sucrose reduction. High-intensity sweeteners lift sweetness, yet they cannot replace body on their own. Ingredion showed coffee-inspired gummies with sugar reduction at IFT FIRST 2025. The application example shows why brands often evaluate sweetener systems beside texture, flavor release and aftertaste control.
How does Application shape demand?
Nutraceutical gummies capture 34.0% share in 2026.
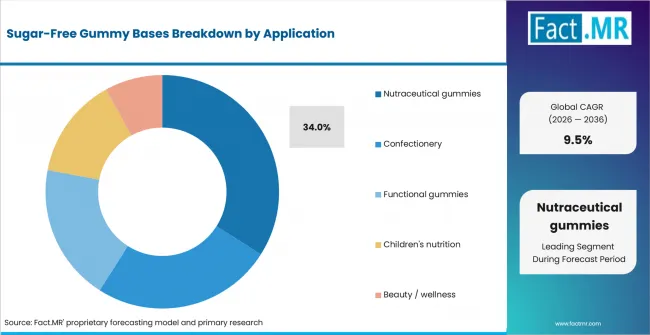
Sugar Free Gummy Bases Analysis By Application | Source: Fact.MR
Nutraceutical gummies are anticipated to lead application demand because vitamins and wellness actives are moving into formats that feel less medical. The base must carry active ingredients while keeping the bite soft enough for daily use. CDC NCHS reported in May 2026 that 60.2% of U.S. adults used any dietary supplement during August 2021 to August 2023. That usage base supports sugar-free gummy formats with clearer calorie positioning.
What supports Soft Chew within Texture Target?
Soft chew represents 31.0% share in 2026.
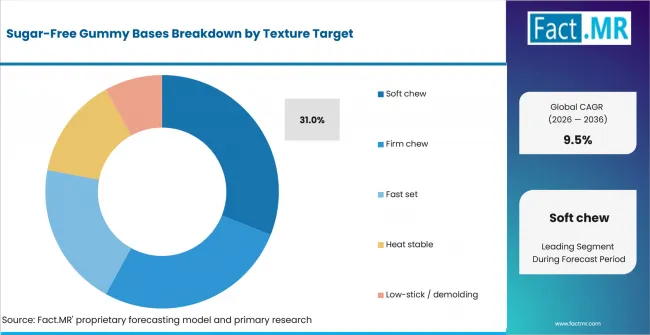
Sugar Free Gummy Bases Analysis By Texture Target | Source: Fact.MR
Soft chew is forecast to represent the main texture target because daily-use gummies must remain easy to bite. Rubbery texture reduces repeat purchase even when the nutrition claim is clear. GELITA positioned CONFIXX in 2025 for fortified gummy production and starch-free processing. The product direction reflects a wider need for clean manufacturing and consistent chew in functional formats.
What is accelerating Sugar-Free Gummy Bases Market adoption, and what is holding it back?
Sugar reduction drives it; taste, tolerance and label review restrain it.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Sugar-reduction reformulation in gummies | +1.5% | Global | Short term (<= 2 years) |
| Nutraceutical gummies moving beyond tablets | +1.3% | North America, East Asia | Medium term (2-4 years) |
| Plant-based pectin and hydrocolloid demand | +0.9% | Europe, North America | Medium term (2-4 years) |
| Online food and supplement channels | +0.7% | China, USA | Short term (<= 2 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Pectin blends for vegan gummy bases | +1.0% | Europe, North America | Medium term (2-4 years) |
| Polyol and allulose balancing systems | +0.8% | USA, East Asia | Short term (<= 2 years) |
| Low-stick demolding support | +0.6% | Global | Medium term (2-4 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Polyol tolerance and taste limits | -0.6% | Global | Short term (<= 2 years) |
| Sugar-free label review | -0.4% | USA, Europe, China | Medium term (2-4 years) |
| Ingredient cost and recipe complexity | -0.3% | Global | Medium term (2-4 years) |
Which countries are scaling the Sugar-Free Gummy Bases Market through 2036?
- The country comparison spans 2.0 percentage points and forms three practical growth bands across the forecast period.
- China remains 0.5 percentage point above the USA through online food retail and national nutrition guidance.
- The USA remains 0.2 percentage point above Germany as supplement use supports sugar-free nutraceutical gummies.
- Germany remains 0.9 percentage point above Japan through reduced-sugar taste familiarity and plant-based base demand.
- Japan remains 0.4 percentage point above France as ageing consumers support easy-chew wellness formats.
- France closes the displayed range through pharmacy-led supplement use and measured confectionery launches.
Comparable CAGRs create different entry conditions due to sugar rules, supplement habits, retail channel structure and texture expectations. Full report coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Middle East & Africa.
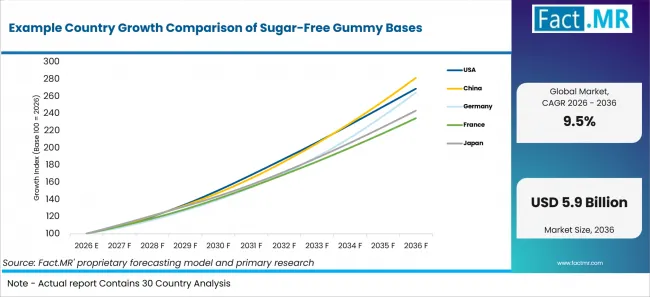
Example Country Growth Comparison Of Sugar Free Gummy Bases | Source: Fact.MR
| Country | CAGR |
|---|---|
| China | 10.9% |
| United States | 10.4% |
| Germany | 10.2% |
| Japan | 9.3% |
| France | 8.9% |
How is China scaling demand?
10.9% CAGR, supported by online food retail and nutrition-policy pressure.
China's online food channel gives sugar-free gummy bases a fast testing route for wellness and confectionery launches. The country is projected to post 10.9% CAGR through 2036. The National Bureau of Statistics reported in January 2026 that online retail sales of food increased by 14.5% in 2025, providing a favorable digital retail environment for direct-to-consumer trials of products such as sugar-free gummies.
What supports USA adoption?
10.4% CAGR, supported by supplement use and mature food spending.
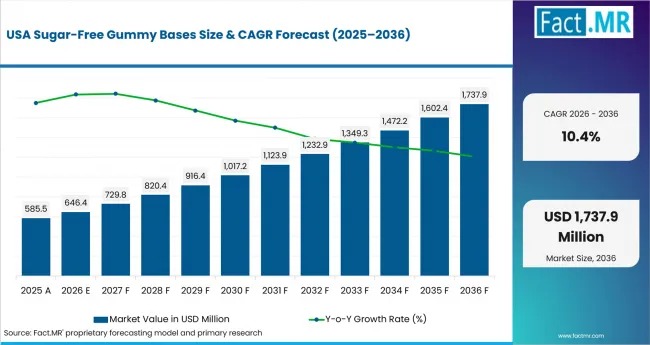
Sugar Free Gummy Bases Country Value Analysis | Source: Fact.MR
The USA has a large supplement base that fits sugar-free nutraceutical gummy formats. The country is forecast to record 10.4% CAGR through 2036. CDC NCHS reported in May 2026 that 60.2% of U.S. adults used any dietary supplement during August 2021 to August 2023.
What is supporting Germany's adoption?
10.2% CAGR, supported by reduced-sugar habits and plant-based texture demand.
Germany has visible consumer familiarity with reduced-calorie sweet products and plant-based ingredient positioning. The country is anticipated to advance at 10.2% CAGR through 2036. Destatis reported in February 2026 that Germany produced 1.5 billion liters of reduced-calorie cola and lemonade in 2024.
How does Japan perform?
9.3% CAGR, led by ageing consumers and easy-chew wellness formats.
Japan's older consumer base supports wellness gummies that are easy to chew and portion. The country is estimated to grow at 9.3% CAGR through 2036. The Statistics Bureau of Japan reported that the final population estimate for February 1, 2026 included 36.198 million residents aged 65 and over.
What supports France's growth?
8.9% CAGR, backed by ageing demographics and pharmacy-led supplement use.
France gives sugar-free gummy bases a route through pharmacy and parapharmacy supplement formats. The country is expected to post 8.9% CAGR through 2036. INSEE estimated in January 2026 that people aged 65 and over represented 22.2% of the French population.
Who leads the Sugar-Free Gummy Bases Market?
Cargill and Tate & Lyle lead direct pectin and sweetener coverage, while Ingredion, IFF and GELITA strengthen adjacent formulation capabilities.
Cargill supports gummy formulation through pectin, sweeteners, texturizers and confectionery application expertise, including solutions for reduced-sugar formulations. Tate & Lyle strengthened its pectin and specialty-gum capabilities through its combination with CP Kelco, and its July 2025 IFT FIRST showcase highlighted expanded mouthfeel capabilities, including a no-sugar-added dual-texture gummy concept. These capabilities are relevant because reduced- and no-sugar gummy formulations often require texture, mouthfeel and other functional properties to be rebuilt as sugar is reduced.
Ingredion supports sugar reduction through sweetener and texturizing systems and showcased a sugar-reduced multitextural gummy at IFT FIRST 2025. IFF provides GRINDSTED® Pectin for plant-based and low-sugar supplement gummies, while GELITA supports fortified gummy production through its starch-free CONFIXX® gelatin system. Across these suppliers, important formulation capabilities include chew and texture control, sugar-reduction performance, processing flexibility and application support.
Which companies are the key providers?
CP Kelco and Cargill are key providers. Ingredion, IFF and Tate & Lyle are also profiled. GELITA completes the company set.
- CP Kelco (part of Tate & Lyle)
- Cargill
- Ingredion
- IFF
- Tate & Lyle
- GELITA
Bibliography
- Stierman, B., Couch, C. A., Gahche, J. J., & Mishra, S. (2026, May 21). Dietary supplement use: United States, August 2021–August 2023 (NCHS Data Brief No. 561). National Center for Health Statistics.
- Cargill. (2025, March 4). Cargill showcases full range of innovative food solutions at AAHAR 2025.
- Nutrient content claims for the calorie content of foods, 21 C.F.R. § 101.60 (2026).
- GELITA. (2025, March 28). CONFIXX®: Revolutionize your fortified gummy production [E-book].
- IFF. (2025, April 22). IFF Pharma Solutions to showcase plant-based dietary supplement ingredients and technical expertise at Vitafoods™ Europe 2025.
- Ingredion. (2025, July 22). Ingredion at IFT FIRST 2025 — Connecting texture, health and innovation.
- Thélot, H. (2026, January 13). Bilan démographique 2025 : En 2025, le solde naturel en France est négatif pour la première fois depuis la fin de la Seconde Guerre mondiale (Insee Première No. 2087). Institut national de la statistique et des études économiques.
- National Bureau of Statistics of China. (2026, January 20). Total retail sales of consumer goods in December 2025.
- Statistics Bureau of Japan. (2026, July 21). Population estimates: July 2026 [Monthly report].
- Statistisches Bundesamt. (2026, February 12). 93 Liter zuckerhaltige Erfrischungsgetränke 2024 pro Kopf produziert [93 litres of sugary soft drinks produced per capita in 2024].
- Tate & Lyle. (2025a, April 1). Tate & Lyle welcomes government officials to Lille Skensved, formerly of CP Kelco, to celebrate completion of carbon reduction and energy efficiency project.
- Tate & Lyle. (2025b, July 7). Tate & Lyle debuts expanded portfolio and mouthfeel leadership at IFT FIRST 2025.
- Zeballos, E., & Sinclair, W. (2026, June 11). Total U.S. food spending reached $2.51 trillion in 2025. U.S. Department of Agriculture, Economic Research Service.
This Report Answers
- The report explains where sugar-free gummy bases are used across gelling base and sweetener system. It also connects the category with adjacent sugar-free confectionery applications.
- Segment analysis identifies pectin and polyols as the leading subsegments. It also links texture selection with gummy texture stabilizers used in chew control.
- Country analysis examines China, the USA, Germany, Japan and France, with plant-derived texture demand compared with plant-based gummy stabilizers.
- Competitive analysis reviews CP Kelco, Cargill, Ingredion, IFF, Tate & Lyle and GELITA across pectin, sweetener and hydrocolloid systems used near adult vitamin gummies.
- Application analysis assesses nutraceutical gummies and confectionery use cases. It places sugar-free bases beside nutraceutical confectionery where active delivery and taste both influence formulation.
What does the Sugar-Free Gummy Bases Market cover?
The Sugar-Free Gummy Bases Market covers ingredient systems that help brands produce sugar-free gummies with controlled chew, set time and sweetness balance. It sits near gummy vitamins because both categories depend on soft, portioned delivery.
The assessment covers pectin, gelatin, starch and multi-hydrocolloid blends across supplement and confectionery applications. Demand is compared with broader dietary supplements only where the gummy base is part of the final delivery format.
What is included in the scope?
The scope includes commercial gelling bases, sweetener systems and texture-supporting blends sold to gummy manufacturers. It includes pectin-led systems that overlap with citrus pectin when the ingredient is used for sugar-free gummy structure.
It includes bases for soft chew, firm chew, fast set and low-stick outcomes. The analysis also considers food stabilizers where stabilizer functionality directly supports reduced-sugar gummy processing.
What is excluded from the scope?
Finished branded gummies, conventional sugar-based gummy candy, tablets, capsules, syrups and beverage sweetener systems are outside the scope. Adjacent gelatin substitutes are covered only when sold as a gummy-base input.
Raw fruit flavors, colors, packaging materials and production equipment are also outside the scope when sold separately from the sugar-free gummy base formulation.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with ingredient suppliers, confectionery manufacturers, supplement brands, contract manufacturers and distributors. These conversations examine formulation priorities, processing challenges, approval requirements and market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, technical material, product pages and standards. Every evidence item used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing trends, segment shares, country growth, adoption patterns and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing interviews with public data, company activity, regulatory changes and product developments. Updates review launches, partnerships and shifts in commercial adoption.
What is the report's scope and coverage?
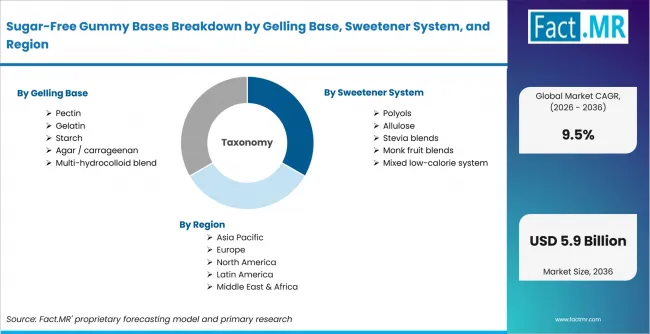
Sugar Free Gummy Bases Breakdown By Gelling Base, Sweetener System, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Ingredient base systems used to produce sugar-free gummies, including gelling bases, sweetener systems and texture targets for nutraceutical and confectionery applications. |
| Gelling Base | Pectin; Gelatin; Starch; Agar/carrageenan; Multi-hydrocolloid blend |
| Sweetener System | Polyols; Allulose; Stevia blends; Monk fruit blends; Mixed low-calorie system |
| Application | Nutraceutical gummies; Confectionery; Functional gummies; Children's nutrition; Beauty/wellness |
| Texture Target | Soft chew; Firm chew; Fast set; Heat stable; Low-stick/demolding |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | United States; China; Germany; France; Japan |
| Key Companies Profiled | CP Kelco; Cargill; Ingredion; IFF; Tate & Lyle; GELITA |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using demand signals, segmentation, country growth and provider review. |
How is the market segmented?
-
By Gelling Base
- Pectin
- Gelatin
- Starch
- Agar/carrageenan
- Multi-hydrocolloid blend
-
By Sweetener System
- Polyols
- Allulose
- Stevia blends
- Monk fruit blends
- Mixed low-calorie system
-
By Application
- Nutraceutical gummies
- Confectionery
- Functional gummies
- Children's nutrition
- Beauty/wellness
-
By Texture Target
- Soft chew
- Firm chew
- Fast set
- Heat stable
- Low-stick/demolding
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa