- Market Value (2025): USD 6.0 Bn
- Estimated Value (2026): USD 6.26 Bn
- Forecast Value (2036): USD 9.61 Bn
- CAGR (2026-2036): 4.4%
What is the Automotive Cooler Market forecast to be worth by 2036?
USD 6.3 billion in 2026 to USD 9.6 billion by 2036 at a 4.4% CAGR.
- As per Fact.MR analysis, the automotive cooler market reached USD 6.0 billion in 2025.
- Demand will increase from USD 6.26 billion in 2026 to USD 9.61 billion by 2036.
- The automotive cooler market will record 4.4% CAGR from 2026 to 2036.
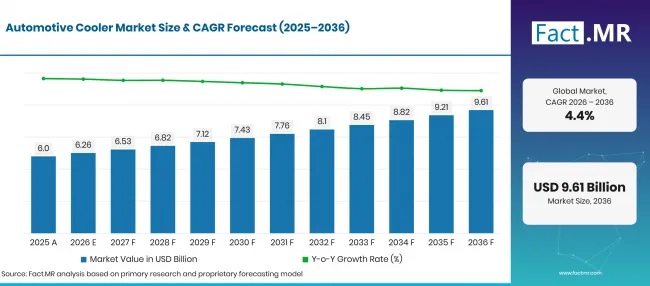
Automotive Cooler Market Country Growth (4) | Source: Fact.MR
| Year | Basis | Market value (USD million) |
|---|---|---|
| 2025 | Actual | 6.0 |
| 2026 | Estimate | 6.26 |
| 2036 | Forecast | 9.61 |
| CAGR, 2026 to 2036 | 4.4% | |
What are the defining numbers behind Automotive Cooler Market growth?
An absolute opportunity of USD 3.3 billion will be created between 2026 and 2036.
- Demand Drivers in the Market
- Electrification changes cooling needs without removing them. The International Energy Agency reported that electric car sales topped 20 million globally in 2025, lifting their share of the car market to 25% [1]. Plug-in cars need low-temperature radiators and chillers for battery packs and power electronics.
- Emission rules keep pressure on charge air and exhaust gas cooling. In July 2025, the European Commission adopted Implementing Regulation (EU) 2025/1706, which sets the test methods for Euro 7 emission approval of new cars and vans [2]. Engine makers will rely on intercoolers and EGR coolers to meet these limits.
- Engine downsizing raises cooler content per vehicle. Smaller turbocharged engines run hotter, so vehicle makers add charge air coolers and larger oil coolers.
- Older vehicles generate steady replacement demand. Radiators and condensers corrode or clog with age. Workshops replace them through distributor networks that do not depend on new vehicle build cycles.
- Key Segments Analyzed
- By Product Type: Radiator will hold 38.5% share in 2026 since every liquid-cooled engine needs one and electrified platforms add low-temperature radiators for battery circuits.
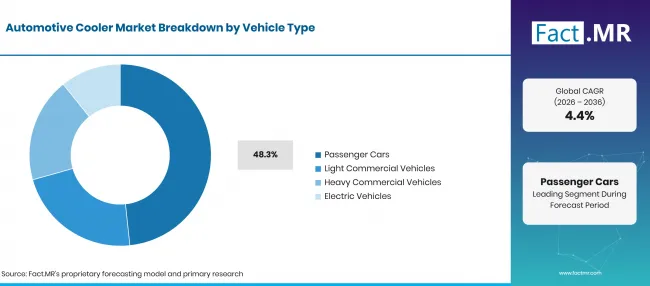
- By Vehicle Type: Passenger Cars will account for 48.3% share in 2026, supported by high build volumes and a large fleet in use.
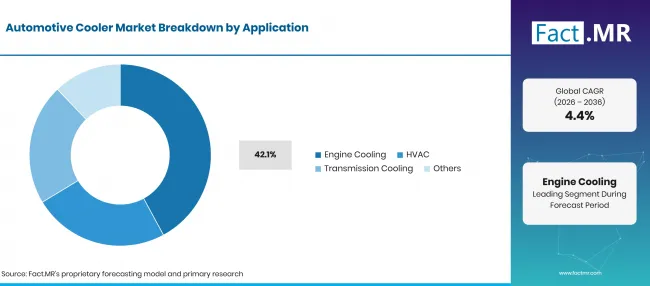
- By Application: Engine Cooling will capture 42.1% share in 2026 owing to the continuous heat load of combustion and hybrid engines.
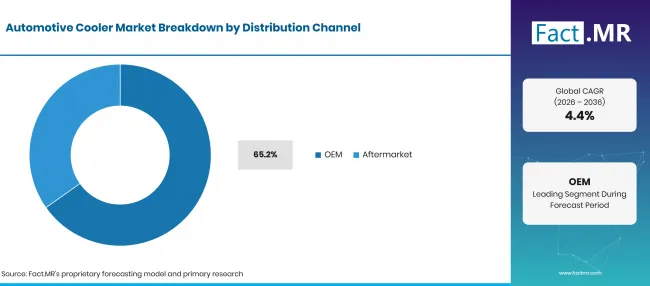
- By Distribution Channel: OEM will represent 65.2% share in 2026, reflecting multi-year supply contracts awarded for new vehicle platforms.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Electrification will change the mix of coolers that suppliers sell. Radiators will stay at the core of the system, while chillers and low-temperature radiators gain ground on hybrid and electric platforms. Suppliers that design light aluminum cores and win full module contracts will hold an edge in OEM sourcing.”
- Strategic Implications
- Cooler manufacturers should extend aluminum brazing lines to chillers and low-temperature radiators, given that battery circuits will add cooling content on electrified platforms.
- Vehicle makers should source radiators and condensers as one front-end module where packaging allows, since one supplier can tune airflow and cut assembly time.
- Aftermarket distributors should widen radiator and condenser coverage for vehicles older than ten years, where corrosion lifts replacement rates.
Thailand will lead at 5.5% CAGR, supported by investment in electric and hybrid vehicle assembly. The United States will follow at 5.1% with a large registered fleet and a high truck share. Poland will record 4.7% as an older car fleet sustains radiator replacement. South Korea will post 4.0% on rising electric car sales, while Germany will reach 3.5% with a growing car fleet. Japan will close at 3.2% where steady vehicle exports support cooler output.
How does the Automotive Cooler Market break down by segment?
Radiator will lead Product Type at 38.5%; Passenger Cars will lead Vehicle Type at 48.3%; Engine Cooling will lead Application at 42.1%; OEM will lead Distribution Channel at 65.2%.
Which Product Type dominates?
Radiator will hold 38.5% share in 2026.
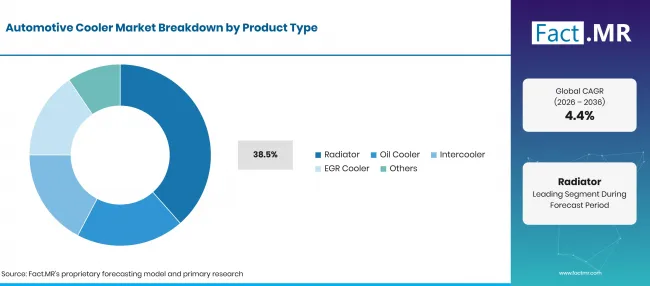
Automotive Cooler Market Country Growth (14) | Source: Fact.MR
Automotive Cooler Market Breakdown by Product Type
| Product Type | Share (2026) |
|---|---|
| Radiator (Leading Segment) | 38.5% |
| Other Segments Combined | 61.5% |
| Total | 100.0% |
Source: Fact.MR’s proprietary forecasting model and primary research.
Radiators will lead as every liquid-cooled engine rejects heat to the air through one. Electric platforms also use car radiators in low-temperature loops that cool batteries and inverters.
Oil coolers, intercoolers and EGR coolers serve duties tied to engine design. The EPA reported that gasoline turbocharged engines accounted for more than 44% of all U.S. vehicle production in model year 2024 [3]. Turbocharged engines use an automotive intercooler to cool charge air. MAHLE said in April 2026 that cooling modules and exhaust gas heat exchangers were among the main drivers of its 2025 order intake [4].
What leads the Vehicle Type segment?
Passenger Cars will account for 48.3% share in 2026.
Automotive Cooler Market Country Growth (15) | Source: Fact.MR
Automotive Cooler Market Breakdown by Vehicle Type
| Vehicle Type | Share (2026) |
|---|---|
| Passenger Cars (Leading Segment) | 48.3% |
| Other Segments Combined | 51.7% |
| Total | 100.0% |
Source: Fact.MR’s proprietary forecasting model and primary research.
Passenger cars will lead since they make up most vehicle production and most of the fleet in use. Eurostat reported that the number of registered passenger cars in the EU exceeded 260 million in 2025 [5].
Light and heavy commercial vehicles need larger cores for sustained loads and towing. Electric vehicles shift cooling demand toward battery chillers and battery cooling plates, although they still use radiators to reject that heat to the air.
How does Application shape demand?
Engine Cooling will capture 42.1% share in 2026.
Automotive Cooler Market Country Growth (12) | Source: Fact.MR
Automotive Cooler Market Breakdown by Application
| Application | Share (2026) |
|---|---|
| Engine Cooling (Leading Segment) | 42.1% |
| Other Segments Combined | 57.9% |
| Total | 100.0% |
Source: Fact.MR’s proprietary forecasting model and primary research.
Engine cooling will lead as combustion and hybrid engines must reject heat continuously. The engine circuit carries the heaviest thermal load in most vehicles, and radiators, oil coolers and intercoolers all serve it.
HVAC demand follows cabin comfort needs and ambient heat. The World Meteorological Organization reported that the global average surface temperature in 2025 was 1.44 °C above the 1850 to 1900 average [6]. Hotter summers raise the load on the automotive condenser and evaporator. Transmission cooling grows with automatic gearboxes and towing.
What supports OEM within Distribution Channel?
OEM will represent 65.2% share in 2026.
Automotive Cooler Market Country Growth (13) | Source: Fact.MR
Automotive Cooler Market Breakdown by Distribution Channel
| Distribution Channel | Share (2026) |
|---|---|
| OEM (Leading Segment) | 65.2% |
| Other Segments Combined | 34.8% |
| Total | 100.0% |
Source: Fact.MR’s proprietary forecasting model and primary research.
OEM will lead given that coolers are designed into each vehicle platform under multi-year contracts. Vehicle makers set size, weight and durability targets early.
The aftermarket tracks fleet age, repair frequency and distributor reach. Buyers weigh fitment coverage and price against lower-cost alternatives. In July 2025, DENSO added radiators and condensers to its European aftermarket thermal range [7].
What is accelerating Automotive Cooler Market adoption, and what is holding it back?
Demand will rise through electrified powertrains, tighter emission rules and an aging vehicle fleet. Growth is constrained by lower combustion cooler content in battery electric vehicles and by aluminum price swings.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Battery and power electronics cooling on electrified platforms | +1.1% | East Asia, Western Europe, North America | Medium term (2-4 years) |
| Engine downsizing and turbocharging that add charge air and oil coolers | +1.0% | North America, Western Europe, East Asia | Short term (<= 2 years) |
| Replacement demand from aging vehicle fleets | +0.8% | North America, Eastern Europe, Latin America | Short term (<= 2 years) |
| Euro 7 and other emission rules that raise EGR and charge air cooling needs | +0.6% | Western Europe, Eastern Europe | Long term (>= 4 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Chillers and low-temperature radiators for battery thermal loops | +0.9% | Global | Long term (>= 4 years) |
| Integrated front-end cooling modules for new platforms | +0.6% | East Asia, Western Europe | Medium term (2-4 years) |
| Localized cooler production near new assembly plants in Southeast Asia | +0.5% | South Asia & Pacific | Medium term (2-4 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Lower combustion cooler content in battery electric vehicles | -0.7% | Western Europe, East Asia | Long term (>= 4 years) |
| Aluminum and copper price swings | -0.5% | Global | Short term (<= 2 years) |
| Price pressure from vehicle makers in platform sourcing | -0.4% | Global | Medium term (2-4 years) |
Which countries are scaling the Automotive Cooler Market through 2036?
- The country comparison spans 2.3 percentage points between Thailand at 5.5% and Japan at 3.2%.
- Thailand will keep a 0.4-point lead over the United States, helped by new electric and hybrid vehicle assembly projects that need local cooler supply.
- A high truck and SUV share in new production will give the United States a 0.4-point edge over Poland.
- In Poland, a large stock of cars older than 20 years drives radiator replacement, leaving the country 0.7 points clear of South Korea.
- Fast growth in electric car sales will hold South Korea 0.5 points ahead of Germany.
- German growth will stay 0.3 points above Japan as the car fleet keeps expanding.
- Japan will close the range, where weak electric car sales keep hybrid and combustion cooling in demand.
Comparable CAGRs create different entry conditions, since fleet age and powertrain mix vary by country. Full report coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Middle East & Africa.
As per Fact.MR, global automotive cooler consumption is estimated at USD 0.76 per capita in 2026, compared with USD 0.73 per capita in 2025. It will grow to USD 1.08 per capita by 2036 as vehicle makers fit more charge air coolers, oil coolers and battery chillers to each new vehicle. Demand will rise across vehicle plants, repair workshops and parts distributors in both mature and emerging economies. As per Fact.MR, the growth of automotive coolers will come less from additional engine radiators and more from battery and power electronics cooling, charge air cooling on downsized engines and replacement parts for aging fleets.
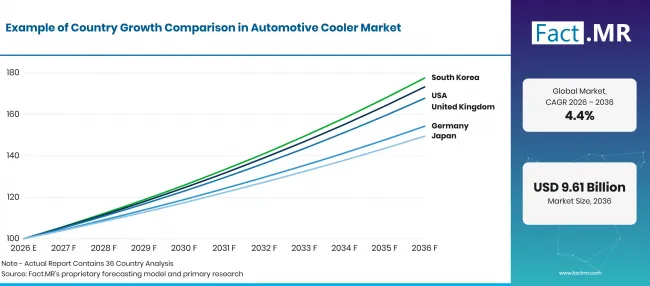
Automotive Cooler Market Country Growth (6) | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| Thailand | 5.5% |
| United States | 5.1% |
| Poland | 4.7% |
| South Korea | 4.0% |
| Germany | 3.5% |
| Japan | 3.2% |
What supports Thailand adoption?
5.5% CAGR, supported by investment in electric and hybrid vehicle assembly.
Thailand’s Board of Investment reported in July 2026 that 198 electric vehicle supply chain projects had drawn pledges of over USD 4.1 billion [8]. Hybrid vehicle projects accounted for about USD 1.18 billion of that total [8]. The International Energy Agency reported that electric car sales in Thailand rose by 70% in 2025 to roughly 140,000 [1].
How is the United States scaling demand?
5.1% CAGR, driven by a large registered fleet and a high truck share.
The Federal Highway Administration reported that the United States had 298 million registered motor vehicles in 2024 [9]. EPA data show that the truck class, which includes pickups and truck SUVs, reached an all-time high of 66% of production in model year 2024 [3].
What supports Poland’s growth?
4.7% CAGR, backed by an older car fleet and rising car ownership.
Polish workshops service a fleet with many older cars. Eurostat reported that 35.1% of passenger cars in Poland were 20 years old or older in 2024 [5]. The Polish car fleet grew by 11% between December 2020 and December 2025 [5].
How is South Korea developing demand?
4.0% CAGR, supported by rising electric car sales.
South Korean vehicle makers build electric, hybrid and combustion models for home and export markets. The International Energy Agency reported that electric car sales in Korea grew by around 65% in 2025 to more than 200,000 [1].
What is supporting Germany’s adoption?
3.5% CAGR, supported by a growing car fleet and electric car uptake.
Destatis reported that Germany had about 49.5 million registered passenger cars at the start of 2026, or 593 cars per 1,000 residents [10]. The International Energy Agency reported that German electric car sales rose by 50% in 2025 to a record 850,000 [1]. Euro 7 rules will keep charge air and EGR cooling in use on combustion and hybrid models.
How does Japan perform?
3.2% CAGR, shaped by vehicle exports and slow electric car uptake.
Export volumes support domestic cooler output in Japan. The Ministry of Finance reported that Japan exported 5,896,177 motor vehicles in 2025, up 1.7% in volume [11]. Electric car sales in Japan stayed just above 100,000 in 2025, according to the International Energy Agency [1]. T.RAD supplies radiators, oil coolers and EGR coolers from Japan.
Who leads the Automotive Cooler Market?
Competition runs across three groups. Global thermal system suppliers such as DENSO, Valeo, MAHLE and Hanon Systems compete on full cooling modules and heat pump know-how. They win platform awards on several continents. Hanon Systems became a subsidiary of Hankook & Company Group in January 2025, joining a group built around tires, batteries and thermal management [12]. Heat exchanger specialists such as T.RAD and Marelli compete on core design, aluminum brazing and cost per part. Marelli presented an eAxle oil cooler, a battery chiller and a full aluminum low-temperature radiator at Auto China in April 2026 [13]. Gentherm completed its combination with Modine’s Performance Technologies business on October 1, 2026, adding thermal products for commercial and light vehicles [14]. Sanden competes in HVAC through compressors and heat exchangers. Competition will be decided by cooling density per kilogram, electrified platform wins and service coverage in the aftermarket.
Which companies are the key providers?
Key companies include DENSO Corporation; Valeo SA; MAHLE GmbH; Hanon Systems (Hankook & Company Group); Marelli Holdings Co., Ltd.; Gentherm (including Modine’s former Performance Technologies business); Sanden Corporation (formerly Sanden Holdings Corporation); and T.RAD Co., Ltd.
- DENSO Corporation
- Valeo SA
- MAHLE GmbH
- Hanon Systems (Hankook & Company Group)
- Marelli Holdings Co., Ltd.
- Gentherm (including Modine’s former Performance Technologies business)
- Sanden Corporation (formerly Sanden Holdings Corporation)
- T.RAD Co., Ltd.
Bibliography
- [1] International Energy Agency. (2026, May 20). Global EV Outlook 2026: Trends in electric cars.
- [2] European Commission. (2025, July 25). Commission Implementing Regulation (EU) 2025/1706 laying down rules, procedures and testing methodologies for the application of Regulation (EU) 2024/1257 as regards exhaust and evaporative emission type-approval of vehicles of categories M1 and N1 and amending Implementing Regulation (EU) 2020/683.
- [3] U.S. Environmental Protection Agency. (2026, February). The EPA Automotive Trends Report 2025: Fuel Economy and Technology since 1975.
- [4] MAHLE GmbH. (2026, April 15). MAHLE improves operating result in 2025.
- [5] Eurostat. (2026, July). Passenger cars in the EU.
- [6] World Meteorological Organization. (2026, January 14). WMO confirms 2025 was one of warmest years on record.
- [7] DENSO Aftermarket Europe. (2025, July). Thermal / Engine Cooling: 23 new part numbers added to Thermal range.
- [8] Thailand Board of Investment. (2026, July 3). Thailand Secures $4.1 Billion in EV Chain Investments as Southeast Asia Auto Hub Pivots to Next-Gen Tech.
- [9] Federal Highway Administration. (2026, July 31). Our Nation’s Highways 2026: Vehicles.
- [10] Statistisches Bundesamt (Destatis). (2026, July 22). Pkw-Dichte 2026 erneut gestiegen [Car density rose again in 2026].
- [11] Ministry of Finance, Japan. (2026, March 12). Trade Statistics: Value of Exports and Imports 2025 (Calendar Year) (January-December) (Revised Data).
- [12] Hanon Systems. (2025, January 6). Hankook & Company Group Completes Acquisition of Hanon Systems.
- [13] Marelli. (2026, April 20). Marelli to showcase propulsion and thermal innovations supporting powertrain evolution at Auto China 2026.
- [14] Gentherm. (2026, October 1). Gentherm Completes Combination with Modine’s Performance Technologies Business.
This Report Answers
- The report explains how automotive coolers are sold by product type, vehicle type, application and channel.
- Segment analysis identifies the subsegment that leads each segment and the operating factors behind its 2026 share.
- Country analysis compares the six listed countries through fleet age, powertrain mix and vehicle assembly mechanisms.
- Competitive analysis reviews active cooler and thermal system suppliers.
- Technology analysis assesses how electrification and engine downsizing change cooler content per vehicle.
What does the Automotive Cooler Market cover?
The Automotive Cooler Market covers heat exchangers that remove heat from engine, transmission, charge air, exhaust gas and cabin climate circuits. It includes radiators, oil coolers, intercoolers and EGR coolers.
The assessment tracks all four vehicle types across engine cooling, HVAC and transmission cooling. Demand is measured across OEM and aftermarket channels.
What is included in the scope?
The scope includes new coolers sold to vehicle makers and replacement coolers sold through distributors and workshops. Low-temperature radiators and oil coolers used in battery, motor and inverter circuits of electric vehicles are included when sold as coolers.
Coolers delivered inside an automotive front-end module are counted at the value of the cooler content.
What is excluded from the scope?
The scope excludes water pumps, thermostats and compressors sold on their own, along with refrigerants and coolants. Each engine cooling fan is also excluded unless it forms part of an integrated cooler module.
Heat exchangers for industrial, marine and off-highway equipment fall outside the revenue boundary. Finished vehicles are also excluded.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report’s scope and coverage?
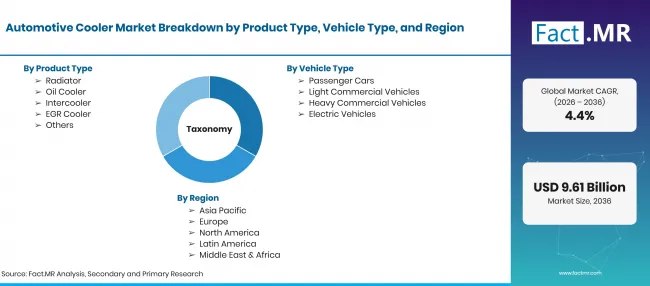
Automotive Cooler Market Country Growth (11) | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion in 2026 to USD billion by 2036 at a CAGR |
| Market Definition | Heat exchangers fitted to vehicles that remove heat from engines, transmissions, charge air, exhaust gas recirculation and cabin climate circuits. The scope covers radiators, oil coolers, intercoolers and EGR coolers sold to vehicle makers and through the aftermarket. |
| Product Type | Radiator; Oil Cooler; Intercooler; EGR Cooler |
| Vehicle Type | Passenger Cars; Light Commercial Vehicles; Heavy Commercial Vehicles; Electric Vehicles |
| Application | Engine Cooling; HVAC; Transmission Cooling |
| Distribution Channel | OEM; Aftermarket |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | Thailand; United States; Poland; South Korea; Germany; Japan |
| Key Companies Profiled | DENSO Corporation; Valeo SA; MAHLE GmbH; Hanon Systems (Hankook & Company Group); Marelli Holdings Co., Ltd.; Gentherm (including Modine’s former Performance Technologies business); Sanden Corporation (formerly Sanden Holdings Corporation); T.RAD Co., Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using vehicle production and fleet data; cooler content per vehicle; powertrain mix; OEM and aftermarket channel split; country growth; and supplier portfolio review. |
How is the market segmented?
-
By Product Type
- Radiator
- Oil Cooler
- Intercooler
- EGR Cooler
-
By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Electric Vehicles
-
By Application
- Engine Cooling
- HVAC
- Transmission Cooling
-
By Distribution Channel
- OEM
- Aftermarket
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa