- Market Value (2025): USD 3.45 Bn
- Estimated Value (2026): USD 3.74 Bn
- Forecast Value (2036): USD 8.42 Bn
- CAGR (2026-2036): 8.5%
What is the Automotive Power Tailgate System Market forecast to be worth by 2036?
USD 3.74 billion in 2026 to USD 8.42 billion by 2036 at an 8.5% CAGR.
- As per Fact.MR analysis, the automotive power tailgate system market reached USD 3.45 billion in 2025.
- Demand is projected to increase from USD 3.74 billion in 2026 to USD 8.42 billion by 2036.
- The market is forecast to record an 8.5% CAGR from 2026 to 2036 as vehicle makers add powered rear access to more passenger-vehicle programs.
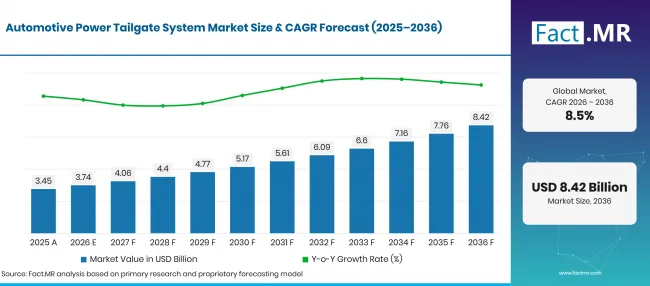
Automotive Power Tailgate System Market (11) | Source: Fact.MR
What are the defining numbers behind Automotive Power Tailgate System Market growth?
According to Fact.MR analysis, an absolute opportunity of USD 4.7 billion is projected between 2026 and 2036.
- Demand Drivers in the Market
- More passenger vehicles are adding powered tailgates as comfort features become common across new models. In April 2026, the UK Department for Transport reported that 2.617 million vehicles were first registered in 2025 [1].
- Smaller sensors are making hands-free tailgates easier to add to vehicles. In May 2025, Huf announced its first production order for a 79 GHz radar kick sensor from a European premium vehicle maker [2].
- Powered opening is useful for vehicles with large rear doors, especially when loading or unloading cargo. Electric motors control how fast and how far the tailgate opens, while sensors help detect objects in its path.
- Suppliers are combining the motor, latch, controller, and sensors into one compact system. This makes the system easier for vehicle makers to fit and connect during vehicle development.
- Key Segments Analyzed
- By Vehicle Type: Passenger Cars will hold 72.4% share in 2026 since SUVs and crossovers form a large fitment base, while hatchbacks and premium cars add further use.
- By Component: Motor/Actuator will account for 38.7% share in 2026 because the drive unit provides the controlled motion needed to raise and lower the tailgate.
- By Sales Channel: OEM will capture 78.6% share in 2026 as mounting points, wiring, safety sensing, and control calibration are planned during vehicle development.
- By Technology: Electric technology will represent 63.5% share in 2026 owing to its direct connection with vehicle electronics and sensor-based access functions.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha of Fact.MR states: “Demand for power tailgates is increasing as more vehicle models add powered rear doors. Suppliers have a stronger position when they offer compact motors that work smoothly with reliable sensors and control software.”
- Strategic Implications
- Early tailgate planning helps vehicle makers manage the space required for opening movement and hinge placement. In April 2025, Stabilus announced an order for more than 400,000 electromechanical door drive systems per year from 2026 [3].
- Combining the drive system, control software, and safety sensors in one package reduces connection work for major suppliers. It also makes system testing easier for vehicle makers.
- Smaller and quieter motors give component makers more room to work with while still providing enough power for larger tailgates. Their compact size also leaves more space for interior trim and cargo.
- Aftermarket parts work best when they are made for specific vehicle models and come with clear repair instructions. Factory-installed systems use set electronic controls and fixed mounting points, so replacement parts must closely match the original system.
Germany is expected to grow the fastest at a 9.2% CAGR through 2036, followed by Brazil at 8.4%. The USA records 7.6%, while the UK reaches 6.8% and Japan 6.0%. Growth differs across these countries based on the types of vehicles sold and the number of factory-installed features offered in new models.
How does the Automotive Power Tailgate System Market break down by segment?
Passenger Cars lead Vehicle Type at 72.4%; Motor/Actuator leads Component at 38.7%; OEM leads Sales Channel at 78.6%; Electric leads Technology at 63.5%.
Which Vehicle Type dominates?
Passenger Cars are projected to hold 72.4% share in 2026.
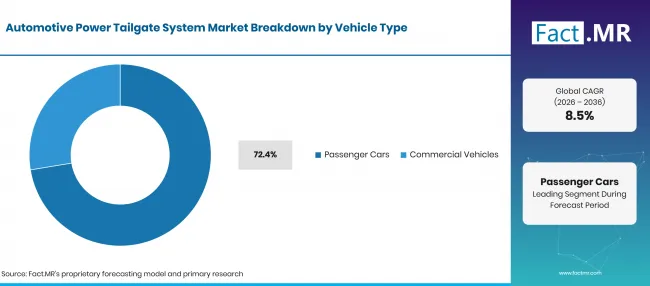
Automotive Power Tailgate System Market Breakdown Vehicle Type | Source: Fact.MR
Passenger cars account for most power tailgate installations, mainly because these systems are widely used in SUVs and crossovers. Hatchbacks and premium cars also support demand. In July 2025, Destatis reported that Germany exported about 1.5 million new passenger cars between January and May 2025 [4].
What leads the Component segment?
Motor/Actuator is estimated to account for 38.7% share in 2026.
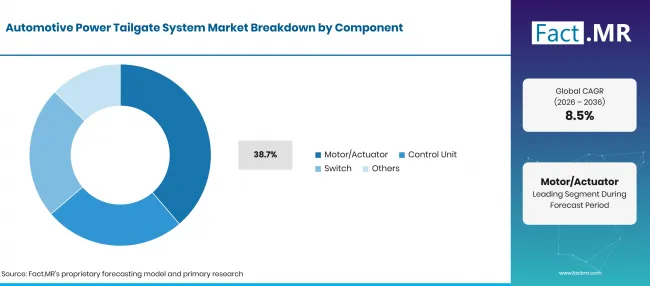
Automotive Power Tailgate System Market Breakdown Component | Source: Fact.MR
The motor provides the power needed to open and close the tailgate in a controlled way. The control unit manages its speed and position, while switches allow the driver to operate the system. The motor size depends on the weight and size of the vehicle’s rear door.
How does Sales Channel shape demand?
OEM is anticipated to capture 78.6% share in 2026.
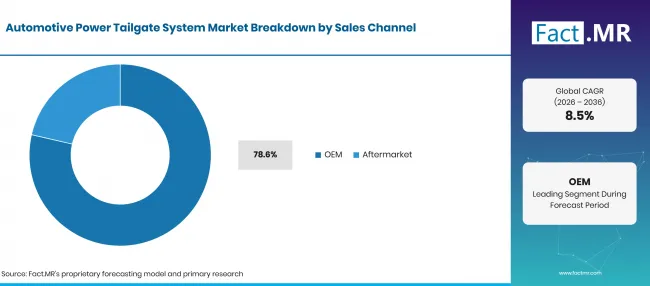
Automotive Power Tailgate System Market Breakdown Sales Channel | Source: Fact.MR
OEM supply leads because power tailgate systems are built into the vehicle body and electrical setup during development. Vehicle makers decide the mounting points and wiring before production, along with sensor settings and safety checks. Aftermarket demand mainly comes from replacement motors and other related parts.
What supports Electric technology?
Electric is forecast to represent 63.5% share in 2026.
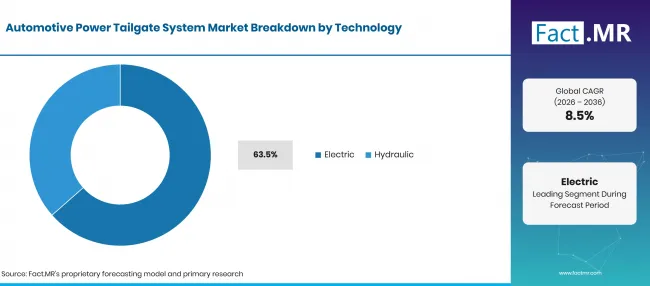
Automotive Power Tailgate System Market Breakdown Technology | Source: Fact.MR
Electric power tailgates work well with modern vehicle electronics and allow drivers to set how high the tailgate opens. The system also controls tailgate movement and responds when an object is detected in its path. In July 2026, the Japan Automobile Importers Association reported that 19,862 imported battery electric vehicles were registered in the first half of 2026 [10].
What is accelerating Automotive Power Tailgate System Market adoption, and what is holding it back?
Fact.MR survey, factory-installed systems and hands-free opening are increasing the use of power tailgates. Higher system costs and the space required for installation may keep these systems less common in entry-level vehicles.
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Wider factory fitment in passenger cars | +2.0% | Global | Medium term (2-4 years) |
| SUV and crossover rear-closure demand | +1.6% | North America, Europe, East Asia | Medium term (2-4 years) |
| Hands-free and sensor-based access | +1.2% | Europe, North America, Japan | Short term (<= 2 years) |
| Compact electric actuator designs | +0.9% | Global | Medium term (2-4 years) |
| Vehicle platform feature upgrades | +0.7% | Global | Long term (>= 4 years) |
Opportunity Impact Analysis
| Opportunity | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Powered access on mid-range vehicles | +1.1% | Global | Medium term (2-4 years) |
| Radar and gesture sensing | +0.8% | Europe, North America, East Asia | Short term (<= 2 years) |
| Integrated drive and control modules | +0.7% | Global | Medium term (2-4 years) |
| Replacement parts and service | +0.5% | Mature vehicle markets | Long term (>= 4 years) |
Restraints Impact Analysis
| Restraint | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Higher system cost than manual tailgates | -0.9% | Global | Short term (<= 2 years) |
| Tight body packaging and calibration | -0.7% | Global | Medium term (2-4 years) |
| Repair cost and electronic complexity | -0.5% | Mature markets | Medium term (2-4 years) |
| Lower fitment on basic commercial vehicles | -0.4% | Latin America, emerging markets | Long term (>= 4 years) |
Which countries are scaling the Automotive Power Tailgate System Market through 2036?
- Germany is projected to keep a 0.8-point lead over Brazil, supported by its passenger-car engineering base and high electronic content in new vehicle programs.
- Brazil is estimated to remain 0.8 points ahead of the USA, reflecting a growing light-vehicle base and rising use of electrified vehicle technologies.
- The USA is forecast to stay 0.8 points above the UK, supported by utility-vehicle demand and the large rear closures used on SUVs and crossovers.
- The UK is anticipated to hold a 0.8-point lead over Japan as new vehicle registrations keep a broad flow of current models entering the fleet.
- Japan is projected to close the listed range at 6.0%, where compact packaging and integrated electronics shape power-tailgate design choices.
Comparable CAGRs create different entry conditions because vehicle mix and feature pricing vary by country. Local engineering and body styles add further differences. Coverage includes North America and Latin America. Western and Eastern Europe are included with East Asia. South Asia & Pacific and Middle East & Africa complete the coverage.
As per Fact.MR survey, the power tailgate supply chain starts with motors and sensors before moving to control units and struts. Tier-1 suppliers combine these parts into complete systems for vehicle makers. Market growth depends on steady component supply and wider factory fitment across SUVs, crossovers and premium vehicles.
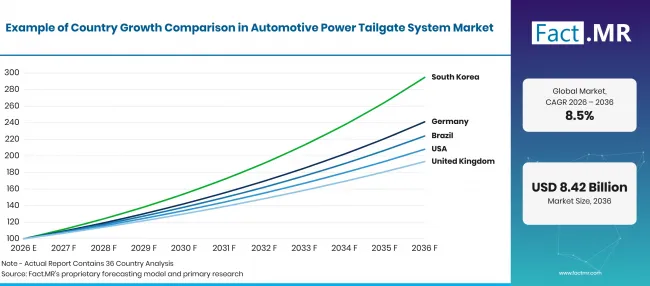
Automotive Power Tailgate System Market Growth Index | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| Germany | 9.2% |
| Brazil | 8.4% |
| USA | 7.6% |
| UK | 6.8% |
| Japan | 6.0% |
What supports Germany's outlook?
9.2% CAGR, supported by passenger-car scale and vehicle-access engineering.
Germany’s large passenger car export industry gives power tailgate suppliers many vehicle models to serve. In September 2026, Destatis reported that Germany exported about 2.0 million new passenger cars from January to July 2026 [8]. Compact motors and control systems work across both premium and mass-market vehicles.
How is Brazil scaling demand?
8.4% CAGR, led by an expanding electrified-vehicle base and passenger-car use.
Brazil is seeing more electric and hybrid vehicles, along with greater use of electronic features in new models. In June 2026, EPE reported that cumulative registrations of electrified vehicles in Brazil reached 396.8 thousand units in 2025 [5]. Power tailgate motors work with the same vehicle control systems used for other comfort features.
What underpins the USA outlook?
7.6% CAGR, backed by utility-vehicle demand and large rear cargo openings.
The U.S. has a large number of SUVs and light trucks, where power tailgates make loading and unloading cargo easier. In February 2026, the U.S. Bureau of Economic Analysis reported that light vehicle sales reached a seasonally adjusted annual rate of 14.81 million units in January 2026 [6]. This gives suppliers more opportunities to offer power tailgates on utility vehicles with added comfort features.
What is supporting the UK market?
6.8% CAGR, shaped by a steady flow of newly registered vehicles.
Steady vehicle registrations in the UK give vehicle makers more models where power tailgates can be installed during production. In September 2026, the Department for Transport reported that 682,000 vehicles were first registered in Q2 2026 [7]. Suppliers can focus on systems that bring together the motor, sensors, and vehicle electronics.
How does Japan perform?
6.0% CAGR, driven by compact packaging and electronics-led vehicle design.
Japan has strong demand for compact parts that fit into limited vehicle space and work with existing electronic systems. In January 2026, the Japan Automobile Importers Association reported about 2.9 million registered vehicles in 2025 [9]. Small power tailgate motors and reliable sensors are well suited to passenger cars.
Who leads the Automotive Power Tailgate System Market?
Brose and Magna offer complete power tailgate systems that combine the moving parts with vehicle electronics. They serve vehicle makers looking for the motor, controls, and access features to work together as one system.
Stabilus focuses on electric drive systems used to open and close vehicle doors and tailgates. Huf provides hands-free sensors that allow drivers to open the tailgate without touching it.
Mitsuba and AISIN supply rear-access parts and electronic systems for factory-installed applications. Johnson Electric mainly supplies motors and actuators that provide the movement needed to operate power tailgates.
Vehicle makers choose suppliers based on system size, smooth movement, reliable sensors, low noise, and easy connection with vehicle electronics. Suppliers that bring these features together in a reliable system have a stronger chance of winning new vehicle programs.
Which companies are the key providers?
Key companies include Brose Fahrzeugteile SE & Co. KG; Magna International Inc.; Stabilus GmbH; Huf Hülsbeck & Fürst GmbH & Co. KG; Mitsuba Corporation; AISIN Corporation; and Johnson Electric Holdings Limited.
- Brose Fahrzeugteile SE & Co. KG
- Magna International Inc.
- Stabilus GmbH
- Huf Hülsbeck & Fürst GmbH & Co. KG
- Mitsuba Corporation
- AISIN Corporation
- Johnson Electric Holdings Limited
Bibliography
- [1] Department for Transport. (2026, April 29). Vehicle licensing statistics, United Kingdom: 2025.
- [2] Huf Group. (2025, May 6). Huf wins first order for kick sensor with 79 GHz radar.
- [3] Stabilus SE. (2025, April 8). Stabilus is building a market-leading position in the future field of electromechanical door control systems for vehicles and wins major tenders.
- [4] Statistisches Bundesamt (Destatis). (2025, July 18). Exports of new passenger cars in the first five months of 2025 up 1.1% year on year.
- [5] Empresa de Pesquisa Energética. (2026, June 3). Balanço Energético Nacional 2026: Relatório Síntese – ano base 2025.
- [6] U.S. Bureau of Economic Analysis. (2026, February 20). Supplemental Estimates, Motor Vehicles.
- [7] Department for Transport. (2026, September 23). Vehicle licensing statistics: April to June 2026.
- [8] Statistisches Bundesamt (Destatis). (2026, September 21). Exports of new passenger cars down 4.0% year on year in the first seven months of 2026.
- [9] Japan Automobile Importers Association. (2026, February 2). January 29, 2026 JAIA Chairman’s Press Conference Keynote Speech.
- [10] Japan Automobile Importers Association. (2026, July 28). JAIA Chairman’s Press Conference Speech, July 27, 2026.
- [11] Stabilus SE. (2025, January 27). Stabilus SE increases revenue and result in Q1 FY2025.
- [12] Magna International. (2025, April 8). Magna to Showcase Advanced Innovations at Auto Shanghai 2025.
- [13] U.S. Bureau of Economic Analysis. (2026, October 2). Supplemental Estimates, Motor Vehicles [Data set].
This Report Addresses
- The report covers vehicle type and component along with sales channel and technology.
- Segment analysis identifies Passenger Cars and Motor/Actuator share in 2026.
- Channel analysis reviews OEM at 78.6% share and the aftermarket replacement route.
- Technology analysis compares Electric systems at 63.5% share with selected Hydraulic applications.
- Country analysis compares Germany and Brazil with the USA. The UK and Japan complete the CAGR set.
- Competitive analysis reviews active power-tailgate suppliers and related actuator or sensing capabilities.
- The forecast uses official vehicle data with verified company products and developments
What does the Automotive Power Tailgate System Market cover?
The Automotive Power Tailgate System Market covers powered rear-hatch and tailgate systems for passenger cars and commercial vehicles. It includes electric or hydraulic drives with controls and switches for powered opening and closing.
The assessment focuses on powered rear-access functions. Adjacent body-access technology is included when it supports tailgate operation through sensing and latching or obstacle detection and body control.
What is included in the scope?
The scope includes factory-fitted and replacement power tailgate systems. Related automotive actuator systems cover motion devices used across vehicle functions.
Rear closures also use automotive motor systems for powered movement. User commands may pass through automotive switches. Controllers and sensors connect the tailgate with wider automotive electronics. Hands-free access overlaps with passive entry door handles when gesture sensing triggers opening.
What is excluded from the scope?
Automotive cockpit electronics remain a separate cabin-interface category. Automotive lighting systems remain separate from rear-closure drive revenue.
Wider electric vehicle components are tracked outside the tailgate boundary. Automotive human interface systems are separate unless the interface directly controls tailgate operation. General automotive powertrain sensors remain outside the rear-access revenue scope.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report's scope and coverage?
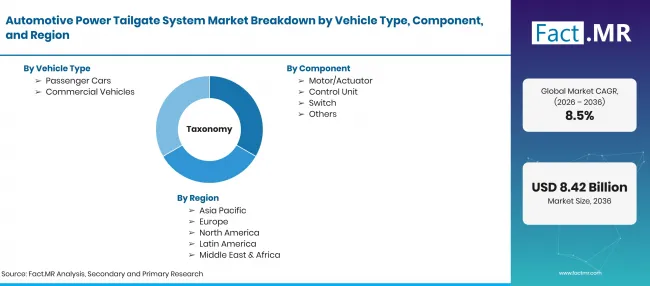
Automotive Power Tailgate System Market Taxonomy | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Factory-fitted and replacement systems that open and close a vehicle tailgate or rear hatch using powered drive hardware, control electronics, switches, and related safety sensing. |
| Vehicle Type | Passenger Cars; Commercial Vehicles |
| Component | Motor/Actuator; Control Unit; Switch; Others |
| Sales Channel | OEM; Aftermarket |
| Technology | Electric; Hydraulic |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | Germany; Brazil; USA; UK; Japan |
| Key Companies Profiled | Brose Fahrzeugteile SE & Co. KG; Magna International Inc.; Stabilus GmbH; Huf Hülsbeck & Fürst GmbH & Co. KG; Mitsuba Corporation; AISIN Corporation; Johnson Electric Holdings Limited |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using vehicle production and registration data, tailgate system architecture, supplied segment shares, country growth, and verified company portfolios. |
How is the market segmented?
-
By Vehicle Type:
- Passenger Cars
- Commercial Vehicles
-
By Component:
- Motor/Actuator
- Control Unit
- Switch
- Others
-
By Sales Channel:
- OEM
- Aftermarket
-
By Technology:
- Electric
- Hydraulic
-
By Region:
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa