- Market Value (2025): USD 833.8 Mn
- Estimated Value (2026): USD 872.0 Mn
- Forecast Value (2036): USD 1364.5 Mn
- CAGR (2026-2036): 4.6%
What is the Definite Purpose AC Contactors Market forecast to be worth by 2036?
USD 872.0 million in 2026 to USD 1364.5 million by 2036 at a 4.6% CAGR.
- Fact.MR estimates the definite purpose AC contactors market at USD 833.8 million for 2025, with HVAC compressors and refrigeration condensing units accounting for most of the units shipped.
- By 2036 the market will reach USD 1364.5 million, up from USD 872.0 million in 2026, as commercial cooling capacity grows and heat pumps take a wider role in space heating.
- A 4.6% CAGR reflects a business tied to equipment build rates and service cycles, where each new outdoor unit or condensing unit carries at least one contactor and many carry two.
| Year | Basis | Market Value (USD million) |
|---|---|---|
| 2025 | Actual | 833.8 |
| 2026 | Estimate | 872.0 |
| 2036 | Forecast | 1364.5 |
| CAGR 2026 to 2036 | Forecast period | 4.6% |
Source: Fact.MR analysis. Updated Nov 12, 2026
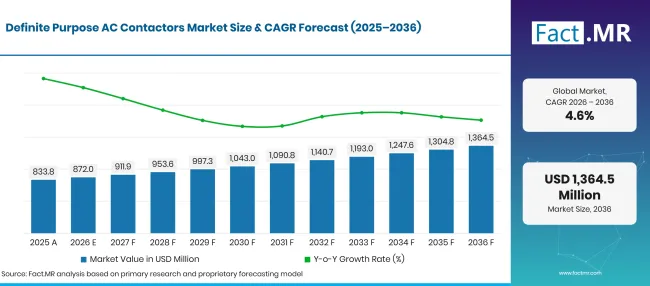
Definite Purpose Ac Contactors Market Forecast Global | Source: Fact.MR
What are the defining numbers behind Definite Purpose AC Contactors Market growth?
The 2026 to 2036 period adds USD 492.6 million in new value, most of it from HVAC equipment, cold-chain refrigeration and contactor replacement in ageing systems.
- Demand Drivers in the Market
- Electricity use in buildings is growing again after years of flat demand. US retail electricity sales rose 2.2% in the residential sector and 2.9% in the commercial sector in 2025. More cooling and heating load on the grid means more compressor starts, and every start passes through a contactor.
- Refrigerant rules are forcing equipment redesign. Since January 1, 2025, new residential and light commercial air conditioning and heat pump systems installed in the United States must use refrigerants with a GWP below 700. Reengineered outdoor units give OEMs a reason to requalify contactors, coils and wiring.
- Heat pumps are extending contactor demand into the heating season. A unit that runs for cooling in summer and heating in winter cycles its compressor far more often over a year than a cooling-only system.
- Cold-chain growth in supermarkets, food plants and warehouses adds steady demand for contactors on refrigeration compressors and evaporator fans.
- Contact wear makes contactors a routine service item. Technicians often swap the contactor during a compressor call, which keeps replacement demand flowing even when new equipment sales slow.
- Key Segments Analyzed
- By Product Type: 3-Pole will hold 42.3% share in 2026 because three-phase compressors and fan motors in commercial rooftop units and condensing units need all three lines switched together.
- By Application: HVAC will account for 38.4% of 2026 value, since every split system, packaged unit and heat pump uses a contactor to start its compressor.
- By End-User: Commercial will capture 48.3% of 2026 revenue as offices, retail stores, hotels and hospitals run large cooling and refrigeration fleets with frequent service visits.
- By Distribution Channel: Direct Sales will represent 50.2% of 2026 sales, given that HVAC and refrigeration OEMs buy contactors in volume under supply agreements with the manufacturer.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Contactor demand now moves with two cycles at once: new HVAC and refrigeration equipment builds and the service market for units already installed. Refrigerant changes and heat pump growth will push OEMs to requalify contactors over the next few years, and suppliers with UL-listed ranges and short lead times will win those slots. Through 2036, three-pole designs will keep their place in commercial equipment, while compact one-pole and two-pole versions will follow residential heat pump volumes.”
- Strategic Implications
- Contactor manufacturers should offer one-pole to four-pole ranges with common mounting footprints, so OEMs can use one design across several equipment sizes.
- HVAC and refrigeration OEMs should bring contactor suppliers into new-refrigerant redesign programmes early, when coil voltage, current rating and life-cycle tests are still open.
- Distributors should stock the coil voltages and ampere ratings that service technicians replace most often, since a missing part ends a repair call.
- Investors should track HVAC shipment data and refrigerant rule changes, as these signal contactor volumes months ahead of reported sales.
The United Kingdom heads the country set at 5.7%, a full point ahead of Japan, because heat pumps are replacing gas boilers in homes that never had a compressor before. Japan follows at 4.7% after record summer heat lifted air conditioner use and replacement. Germany trails Japan by only 0.4 points at 4.3%, with heat pumps now standard in new homes. The United States records 4.0%, a mature base where refrigerant redesign and replacement work drive volume. Brazil closes the range at 3.3%, 0.7 points behind the United States, as commercial cooling gains pace from a lower installed base.
How does the Definite Purpose AC Contactors Market break down by segment?
3-Pole will lead Product Type at 42.3%; HVAC will head Application at 38.4%; Commercial will hold End-User at 48.3%; Direct Sales will lead Distribution Channel at 50.2% in 2026.
Which Product Type leads?
3-Pole takes 42.3% of 2026 sales.
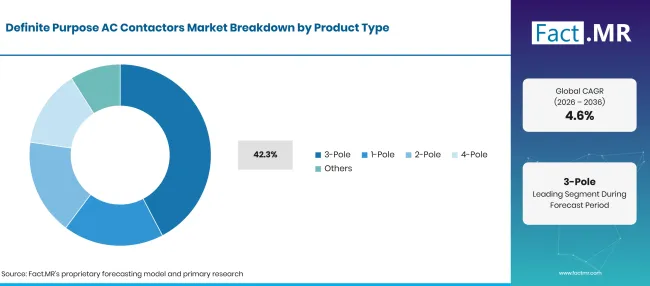
Definite Purpose Ac Contactors Market Breakdown Product Type | Source: Fact.MR
| Product Type | Share (2026) |
|---|---|
| 3-Pole (Leading segment) | 42.3% |
| Other segments combined | 57.7%* |
| Total | 100.0% |
Source: Fact.MR analysis. Updated Nov 12, 2026
Commercial rooftop units, chillers and refrigeration racks run on three-phase power, and their compressors need all three lines opened and closed at the same moment. Eaton’s July 2025 motor control catalog lists its C25 definite purpose contactors from 15 to 360 A in two-, three- and four-pole versions, originally designed for HVACR use. That range shows how far three-pole ratings extend into large reciprocating compressor and scroll applications. One-pole and two-pole contactors serve single-phase residential condensers and heat pumps, where breaking one leg of a 240 V supply can be enough. Four-pole units handle systems that switch a separate circuit, such as a crankcase heater or auxiliary fan. Others include reversing and two-speed assemblies.
What supports HVAC within Application?
HVAC represents 38.4% of 2026 revenue.
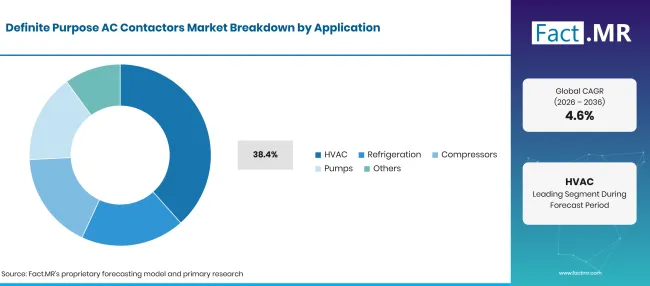
Definite Purpose Ac Contactors Market Breakdown Application | Source: Fact.MR
| Application | Share (2026) |
|---|---|
| HVAC (Leading segment) | 38.4% |
| Other segments combined | 61.6%* |
| Total | 100.0% |
Source: Fact.MR analysis. Updated Nov 12, 2026
Split systems, packaged units and heat pumps all use a contactor to start the compressor and outdoor fan on a thermostat call. Rule changes keep this segment active: EPA finalized a reconsideration of certain Technology Transitions requirements in May 2026, covering residential and light commercial air conditioning and heat pump systems among other subsectors. Wider heat pump use is extending contactor run hours into winter. Refrigeration is the second major use, covering cold rooms, display cases and condensing units across food retail and processing. Compressor applications outside HVAC include oil-free compressor packages and small air systems. Pumps for water circulation and irrigation use the same compact contactors.
How does End-User shape demand?
Commercial accounts for 48.3% of 2026 value.
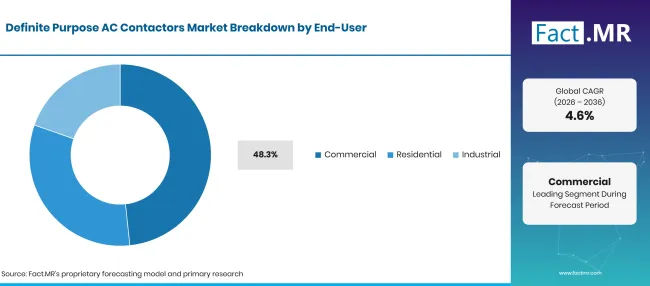
Definite Purpose Ac Contactors Market Breakdown End User | Source: Fact.MR
| End-User | Share (2026) |
|---|---|
| Commercial (Leading segment) | 48.3% |
| Other segments combined | 51.7%* |
| Total | 100.0% |
Source: Fact.MR analysis. Updated Nov 12, 2026
Offices, shopping centres, hotels and hospitals operate fleets of rooftop units and refrigeration systems that run long hours and get serviced on fixed schedules. The US Census Bureau published monthly shipment and new order values for ventilation, heating, air conditioning and refrigeration equipment manufacturing covering 2025 and 2026 in September 2026. Those factory series give contactor suppliers an early view of the commercial equipment pipeline. Residential demand comes from single-family condensers, mini-split outdoor units and heat pumps, mostly in one-pole and two-pole formats. Industrial users buy contactors for process chillers, pumps and air compressor systems, where duty cycles are heavier and ratings run higher.
What leads the Distribution Channel segment?
Direct Sales commands 72.4% of 2026 sales.
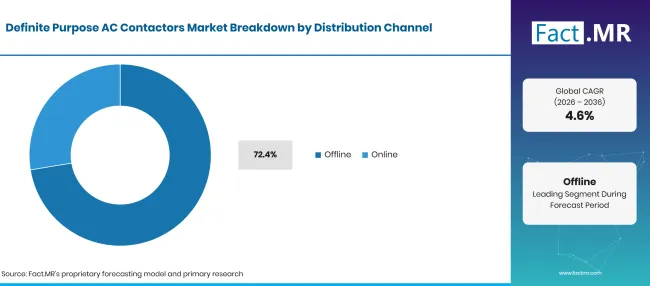
Definite Purpose Ac Contactors Market Breakdown Distribution Channel | Source: Fact.MR
| Distribution Channel | Share (2026) |
|---|---|
| Direct Sales (Leading segment) | 72.4% |
| Other segments combined | 27.6%* |
| Total | 100.0% |
Source: Fact.MR analysis. Updated Nov 12, 2026
HVAC and refrigeration OEMs order contactors by the tens of thousands under annual agreements that fix coil voltage, terminal style and approval marks. Buying from the manufacturer keeps part numbers stable across production runs and simplifies UL and CSA documentation. Distributors and wholesalers serve contractors and service technicians who need a replacement part the same day, often bundled with capacitors and electrical safety products. Online retail is growing for standard one-pole and two-pole models, though specialised ratings still move through counter sales.
What is accelerating Definite Purpose AC Contactors Market adoption, and what is holding it back?
Higher cooling and heating loads, heat pump uptake, cold-chain building and refrigerant-driven redesign are adding contactor demand across all regions. Growth is held in check by price competition from low-cost producers, swings in copper and silver prices and a gradual shift toward solid-state and inverter controls in premium equipment.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Rising installation of air conditioning and HVAC equipment in residential and commercial buildings | +1.5% | Global | Short term (<=2 years) |
| Expansion of commercial refrigeration and cold-chain infrastructure | +1.0% | Global | Medium term (2-4 years) |
| Wider use of heat pumps for space heating and cooling | +0.8% | Europe, North America, East Asia | Medium term (2-4 years) |
| Replacement of worn contactors in existing HVAC and industrial equipment | +0.6% | Global | Short term (<=2 years) |
Source: Fact.MR analysis. Updated Nov 12, 2026
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Compact, application-specific contactors for new-refrigerant HVAC platforms | +0.5% | Global | Medium term (2-4 years) |
| Heat pump retrofit programmes in homes and small buildings | +0.4% | Europe, North America | Long term (>=4 years) |
| Refrigeration equipment for food processing and cold storage | +0.3% | Latin America, South Asia & Pacific | Medium term (2-4 years) |
| Broader distributor networks and digital ordering for service parts | +0.2% | South Asia & Pacific, Middle East & Africa | Short term (<=2 years) |
Source: Fact.MR analysis. Updated Nov 12, 2026
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Price competition from low-cost manufacturers | -0.4% | Global | Short term (<=2 years) |
| Volatile copper, silver and other contact material costs | -0.3% | Global | Short term (<=2 years) |
| Qualification and compatibility requirements across HVAC equipment designs | -0.2% | Global | Medium term (2-4 years) |
| Gradual shift toward solid-state and inverter-based compressor control | -0.1% | North America, Western Europe, East Asia | Long term (>=4 years) |
Source: Fact.MR analysis. Updated Nov 12, 2026
Which countries are scaling the Definite Purpose AC Contactors Market through 2036?
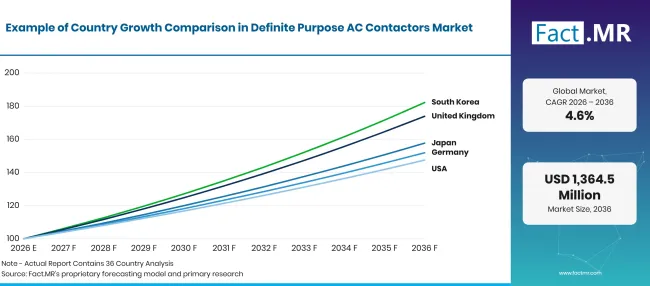
Definite Purpose Ac Contactors Market Growth Index | Source: Fact.MR
| Country | CAGR (2026 to 2036) |
|---|---|
| United Kingdom | 5.7% |
| Japan | 4.7% |
| Germany | 4.3% |
| United States | 4.0% |
| Brazil | 3.3% |
Source: Fact.MR analysis. Updated Nov 12, 2026
How is the United Kingdom scaling demand?
5.7% CAGR, driven by heat pumps replacing gas boilers in existing homes.
British homes are adding compressors at a pace the country has not seen before. Official statistics show retrofit heat pump installations in 2025 were 9% higher than the 48,857 recorded in 2024. The first half of 2026 brought 20,895 installations, down 22% from 26,768 in the same period of 2025. Each outdoor unit needs a contactor at installation and again when contacts wear, so the installed base keeps adding service demand even in a slower quarter.
What supports Japan’s adoption?
4.7% CAGR, backed by record summer heat and air conditioner replacement.
Japan’s summer of 2025 was the hottest since records began in 1898, with the national average temperature 2.36°C above normal and 132 of 153 observation sites setting new summer records. The year as a whole ran 1.25°C above normal, the third warmest on record. Long cooling seasons wear contactors faster in packaged air conditioners and push building owners to replace older units with high-efficiency models.
What supports adoption in Germany?
4.3% CAGR, helped by heat pumps becoming standard in new homes.
KfW Research found that 77% of 2024 building permits for single-family homes planned an air- or water-source heat pump as the main heating system, and that nearly one in two heating systems sold now is a heat pump. Regional data confirm the trend: in Thuringia, renewables were the main heating source in 79.7% of the 660 residential buildings completed in 2025. Every new heat pump brings compressor switching into homes that once relied on gas or oil.
What is supporting United States adoption?
4.0% CAGR, reflecting refrigerant redesign and a large replacement base.
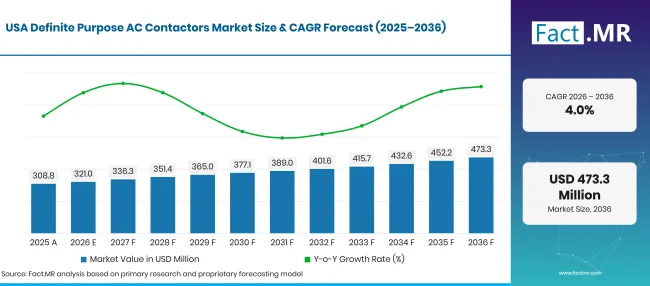
Definite Purpose Ac Contactors Market Forecast Usa | Source: Fact.MR
The United States has a long-established installed base of ducted air conditioners and rooftop units, and much of its contactor demand comes from replacement. A hot summer raised electricity use for cooling in the third quarter of 2026, with residential consumption up 6% and commercial up 5% on the same quarter a year earlier, according to the EIA. Heavier cooling seasons shorten contact life and bring forward service calls.
How is Brazil developing demand?
3.3% CAGR, as commercial and residential cooling loads grow.
Brazil’s air conditioner base is smaller per household than in the other countries profiled, which leaves room for growth. National electricity consumption rose 4.0% in September 2026 from a year earlier, the sixth monthly increase in a row, with commercial use up 8.3% and residential use up 7.7%. Supermarkets, shopping centres and food processors are adding refrigeration and cooling capacity that relies on three-pole contactors.
Who leads the Definite Purpose AC Contactors Market?
The market splits into two groups of suppliers. Broad-line electrical groups such as Schneider Electric, ABB, Siemens and Eaton sell definite purpose contactors alongside breakers and overload relays. That breadth lets HVAC OEMs source a complete control package from one vendor.
Eaton’s July 2025 motor control catalog shows how deep these ranges go, with C25 contactors from 20 A compact single-pole models up to 360 A three- and four-pole units and matching starters. A second group of automation and component specialists competes on compact design and OEM engineering support. Rockwell Automation offers its Allen-Bradley Bulletin 400 definite purpose contactors in a compact format, while TE Connectivity supplies contactors and relays to appliance and HVAC equipment makers. Through 2036, the suppliers that win OEM slots will be those that requalify quickly for new-refrigerant platforms and keep service parts on distributor shelves.
Which companies are the key providers?
Key companies in the Definite Purpose AC Contactors Market include Schneider Electric, ABB, Eaton, Siemens, Rockwell Automation and TE Connectivity.
- Schneider Electric
- ABB
- Eaton
- Siemens
- Rockwell Automation
- TE Connectivity
Bibliography
- Department for Energy Security and Net Zero, United Kingdom. (2026, September 10). Heat pump deployment statistics: June 2026: summary.
- Eaton. (2025, July). Volume 5, Motor Control and Protection: Definite Purpose Contactors and Starters.
- Empresa de Pesquisa Energética, Brazil. (2026, October 30). Resenha Mensal: consumo nacional de eletricidade cresce pelo sexto mês consecutivo.
- Japan Meteorological Agency. (2025, September 1). 2025年の梅雨入り・明け及び夏(6~8月)の記録的高温について.
- Japan Meteorological Agency. (2025, December 24). 2025年(令和7年)の天候のまとめ(速報).
- KfW Research. (2026, February 27). Wärmepumpen sind in neuen Einfamilienhäusern Standard.
- Thüringer Landesamt für Statistik. (2026, May 22). Wärmepumpen dominieren Neubausektor.
- U.S. Census Bureau. (2026, September 28). Monthly HVAC and Refrigeration Equipment Manufacturing.
- U.S. Energy Information Administration. (2026, March 5). U.S. electricity generation in 2025 hit a record, again.
- U.S. Energy Information Administration. (2026, October 6). Short-Term Energy Outlook: Electricity, Coal, and Renewables.
- U.S. Environmental Protection Agency. (2026, July 28). Regulatory Actions for Technology Transitions.
- U.S. Environmental Protection Agency. (2026, August 28). Technology Transitions HFC Restrictions by Sector
This Report Answers
- How will contactor revenue divide between one-pole, two-pole, three-pole and four-pole designs through 2036?
- Why do three-phase commercial systems keep three-pole contactors ahead of other configurations?
- What effect will refrigerant rules and heat pump growth have on HVAC contactor requalification?
- Where does commercial demand come from, and how does it differ from residential and industrial buying?
- Why do OEM supply agreements carry more revenue than distributor and online channels?
- Which of the five profiled countries will add contactor demand quickest, and what separates them?
What does the Definite Purpose AC Contactors Market cover?
This market tracks AC contactors built and listed for defined duties, chiefly compressor, fan and pump switching in HVAC and refrigeration equipment. Products are counted from one-pole to four-pole designs across the usual coil voltages and current ratings.
Value is measured at manufacturer selling price, whether the contactor goes to an OEM production line or reaches a technician through a distributor or online store.
What is included in the scope?
New definite purpose contactors for air conditioners, heat pumps, rooftop units and packaged systems are included.
Contactors fitted to refrigeration condensing units, display cases and commercial refrigeration equipment in food retail and cold storage are covered.
Units sold for compressor, pump and fan switching in light industrial equipment are counted.
Replacement contactors bought for servicing and repair of installed equipment are included.
What is excluded from the scope?
General-purpose IEC and NEMA contactors not rated or marketed for definite purpose duty are excluded.
Circuit breakers, overload relays, motor starters sold as complete assemblies, drives and control panels are left out.
DC contactors, automotive and EV contactors and high-voltage switching equipment are not counted.
The value of the HVAC units, refrigeration systems, compressors and pumps in which contactors are installed is outside the study.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
Segmentation
What is the report’s scope and coverage?
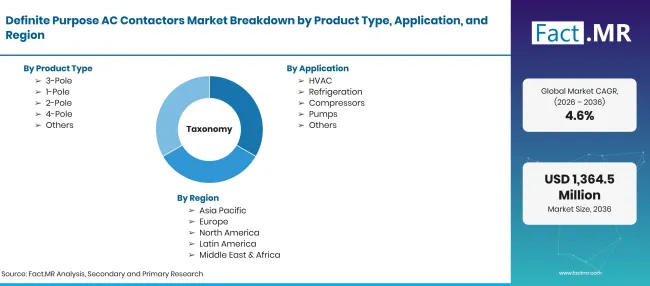
Definite Purpose Ac Contactors Market Taxonomy | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD million |
| Market Definition | Definite purpose AC contactors are electrically operated switches rated and listed for specific loads such as HVAC compressors, refrigeration units, fans and pumps, sold new to equipment makers and to the service market. |
| Product Type | 1-Pole; 2-Pole; 3-Pole; 4-Pole; Others |
| Application | HVAC; Refrigeration; Compressors; Pumps; Others |
| End-User | Commercial; Residential; Industrial |
| Distribution Channel | Direct Sales; Distributors and Wholesalers; Online Retail |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | United Kingdom; Japan; Germany; United States; Brazil |
| Companies Profiled | Schneider Electric; ABB; Eaton; Siemens; Rockwell Automation; TE Connectivity |
| Forecast Period | 2026 to 2036 |
| Approach | Unit build from HVAC and refrigeration equipment output and replacement rates, multiplied by contactor content and average selling price, then checked against supplier product ranges and channel mix. |
Source: Fact.MR analysis. Updated Nov 12, 2026
How is the market segmented?
-
By Product Type
- 1-Pole
- 2-Pole
- 3-Pole
- 4-Pole
- Others
-
By Application
- HVAC
- Refrigeration
- Compressors
- Pumps
- Others
-
By End-User
- Commercial
- Residential
- Industrial
-
By Distribution Channel
- Direct Sales
- Distributors and Wholesalers
- Online Retail
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa
Frequently Asked Questions
How large is the definite purpose AC contactors market in 2026?
What growth rate will the definite purpose AC contactors market record?
Which product type leads?
Which application leads?
Which end-user leads?
Which distribution channel leads?
Which country will grow quickest?
Who are the main companies?
What holds the market back?
Who worked on this report


Preview the report firsthand - request a free sample
Free SampleGet the brochure for pricing and purchase details
Download PDF