- Market Value (2025): USD 1.95 Bn
- Estimated Value (2026): USD 2.06 Bn
- Forecast Value (2036): USD 3.53 Bn
- CAGR (2026-2036): 5.5%
What is the Dehydrated Beans Market forecast to be worth by 2036?
USD 2.06 billion in 2026 to USD 3.53 billion by 2036 at a 5.5% CAGR.
- As per Fact.MR analysis, the dehydrated beans market reached USD 1.95 billion in 2025.
- Demand is projected to increase from USD 2.06 billion in 2026 to USD 3.53 billion by 2036.
- The dehydrated beans market is forecast to record 5.5% CAGR from 2026 to 2036 as food makers and households use quicker-cooking bean formats.
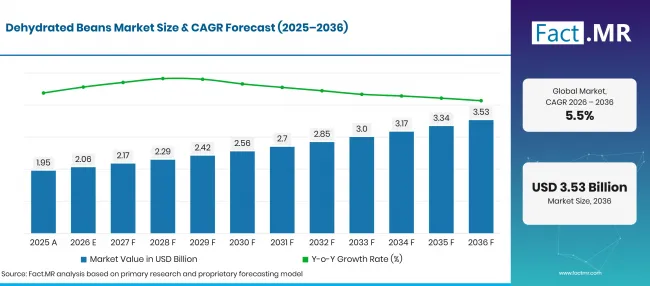
Dehydrated Beans Market Forecast Global | Source: Fact.MR
| Year | Basis | Market value (USD million) |
|---|---|---|
| 2025 | Actual | 1.95 |
| 2026 | Estimate | 2.06 |
| 2036 | Forecast | 3.53 |
| CAGR 2026 to 2036 | 5.5% | |
Source: Fact.MR analysis. Updated 08.10.2026.
What are the defining numbers behind Dehydrated Beans Market growth?
An absolute opportunity of USD 1.4 billion is projected between 2026 and 2036.
- Demand Drivers in the Market
- Food companies use dehydrated beans in soups, meal kits, and prepared foods because they soften faster and require less soaking.
- Foodservice kitchens benefit from easy storage and consistent portions when using dry bean products. Staff can prepare the amount needed for each service period without relying heavily on chilled storage.
- Ingredient processors supply dehydrated beans to prepared-food companies and commercial kitchens that want faster preparation and simple storage. The dry format is also easy to measure for each production batch.
- Key Segments Analyzed
- By Product Type: Black Beans are estimated to hold 28.3% share in 2026 owing to broad use in soups and Mexican-style meals. They also fit snacks and prepared bean fillings.
- By Application: Food Industry is projected to account for 42.1% share in 2026 as food makers use dehydrated beans in shelf-stable meal systems and packaged foods.
- By Distribution Channel: Supermarkets/Hypermarkets are expected to capture 38.9% share in 2026 due to wider household access to packaged beans and convenient pantry foods.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Pre-cooked dehydrated beans reduce the time and steps needed for preparation while remaining easy to store. Buyers prefer products that absorb water evenly and keep the familiar taste and texture of cooked beans.”
- Strategic Implications
- Processors need to keep soaking time and final texture consistent because both affect the quality of soups and prepared meals.
- Food brands benefit from buying beans from more than one region when possible. A wider supply base gives companies more flexibility when harvest volumes change in one location.
- Retail suppliers need simple cooking instructions that clearly explain preparation time and the amount of water required. This helps shoppers understand how dehydrated beans save time compared with standard dry beans.
Brazil leads the five countries with a 7.1% CAGR through 2036, supported by local bean production for processing. The UK follows at 6.5%, backed by its large food manufacturing sector. Japan records 5.9% as bean-based foods remain common in local diets. Germany grows at 4.9% with access to a wide range of pulses, while the USA reaches 4.5% with support from its large dry-bean production base.
How does the Dehydrated Beans Market break down by segment?
Black Beans lead Product Type at 28.3%; Food Industry leads Application at 42.1%; Supermarkets/Hypermarkets lead Distribution Channel at 38.9%.
Which Product Type dominates?
Black Beans are projected to hold 28.3% share in 2026.
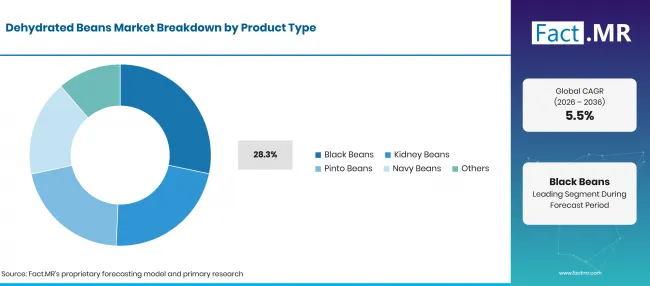
Dehydrated Beans Market Forecast Global | Source: Fact.MR
Dehydrated Beans Market Breakdown by Product Type
| Product type | Share (2026) |
|---|---|
| Black Beans (Leading segment) | 28.3% |
| Other segments combined | 71.7%* |
| Total | 100.0% |
Source: Fact.MR’s proprietary forecasting model and primary research.
Black beans are likely to lead because their familiar taste and color work well in soups and chili. Kidney beans are widely used in ready meals and fillings, while pinto beans are a common choice for Mexican-style foods. Navy beans are mainly used in soups and baked-bean recipes. Buyers generally choose the bean type based on the recipe and the texture after preparation.
What leads the Application segment?
Food Industry is projected to account for 42.1% share in 2026.
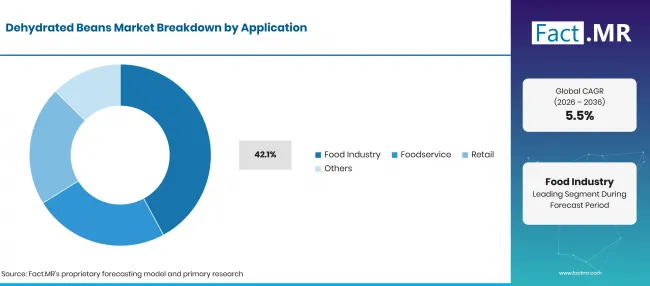
Dehydrated Beans Market Forecast Global | Source: Fact.MR
Dehydrated Beans Market Breakdown by Application
| Application | Share (2026) |
|---|---|
| Food Industry (Leading Segment) | 42.1% |
| Other Segments Combined | 57.9% |
| Total | 100.0% |
Source: Fact.MR’s proprietary forecasting model and primary research.
The food industry is projected to lead because manufacturers add dehydrated beans to dry mixes and prepared foods that soften during final cooking. In July 2026, the Office for National Statistics reported that food manufacturing accounted for 22.9% of UK manufacturers’ product sales in 2025 [2]. Foodservice is another important user, as kitchens benefit from measured portions and faster preparation. Food companies also follow set soaking and cooking steps to keep recipes consistent across production batches.
How does Distribution Channel shape demand?
Supermarkets/Hypermarkets are expected to capture 38.9% share in 2026.
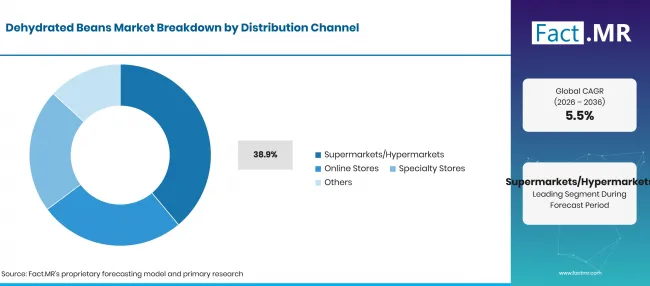
Dehydrated Beans Market Forecast Global | Source: Fact.MR
Dehydrated Beans Market Breakdown by Distribution Channel
| Distribution Channel | Share (2026) |
|---|---|
| Supermarkets/Hypermarkets (Leading Segment) | 38.9% |
| Other Segments Combined | 61.1% |
| Total | 100.0% |
Source: Fact.MR’s proprietary forecasting model and primary research.
Supermarkets and hypermarkets are anticipated to lead because they make packaged bean products easy for households to find and buy. Online stores are more suitable for larger packs and less common bean varieties. Specialty stores attract shoppers looking for pantry staples and plant-based foods. Buyers usually choose a sales channel based on pack size, available varieties, and how often they purchase the product.
What is accelerating Dehydrated Beans Market adoption, and what is holding it back?
Faster cooking helps dehydrated beans gain sales among households and food businesses looking to save preparation time. Changes in crop supply can raise costs, while cheaper standard dry beans can make buyers less willing to switch.
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Quick rehydration for prepared foods | +1.2% | Global | Short term (<= 2 years) |
| Shelf-stable meal and soup use | +0.9% | North America, Europe | Medium term (2-4 years) |
| Retail convenience and pantry storage | +0.8% | USA, UK, Japan | Medium term (2-4 years) |
| Pulse availability for processing | +0.6% | Brazil, USA, Germany | Short term (<= 2 years) |
| Foodservice labor and batch control | +0.4% | Global | Long term (>= 4 years) |
Opportunity Impact Analysis
| Opportunity | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Instant bean flakes and powders | +0.7% | North America, Europe | Medium term (2-4 years) |
| Clean-label prepared meals | +0.6% | USA, Germany, UK | Medium term (2-4 years) |
| Export-oriented bean processing | +0.5% | Brazil, USA | Long term (>= 4 years) |
| Online bulk and outdoor-food packs | +0.3% | USA, UK, Japan | Short term (<= 2 years) |
Restraints Impact Analysis
| Restraint | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Lower price of conventional dry beans | -0.7% | Global | Long term (>= 4 years) |
| Crop and raw-material variability | -0.6% | Brazil, USA, Europe | Short term (<= 2 years) |
| Texture loss after over-rehydration | -0.4% | Global | Medium term (2-4 years) |
| Limited consumer familiarity | -0.3% | Europe, Japan | Medium term (2-4 years) |
Which countries are scaling the Dehydrated Beans Market through 2036?
- Brazil is projected to stay 0.6 percentage points ahead of the UK as domestic bean supply supports processing activity.
- The UK is expected to hold a 0.6-point lead over Japan with its large food-production base supporting convenient ingredient formats.
- Japan is estimated to remain 1.0 point above Germany as familiar dry-bean foods support steady use in packaged foods.
- Germany is forecast to stay 0.4 points ahead of the USA as domestic pulse production supports ingredient supply.
- The USA is projected to close the displayed range at 4.5% as a mature dry-bean base gives dehydrated formats a measured growth path.
Country CAGRs reflect differences in bean supply, food-processing scale and cooking habits. Coverage spans North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, and Middle East & Africa.
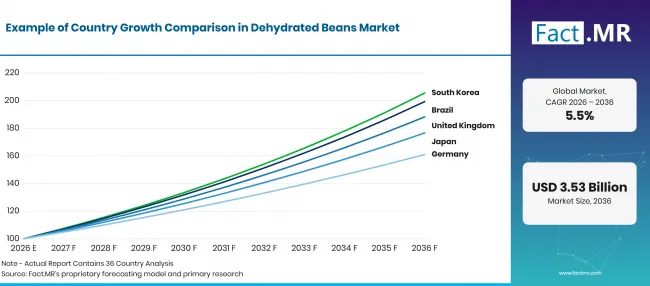
Dehydrated Beans Market Forecast Global | Source: Fact.MR
| Country | CAGR |
|---|---|
| Brazil | 7.1% |
| UK | 6.5% |
| Japan | 5.9% |
| Germany | 4.9% |
| USA | 4.5% |
How is Brazil scaling demand?
7.1% CAGR, supported by domestic bean output and food-processing use.
Brazil’s large bean production base gives food companies a steady supply for processing. In February 2026, IBGE estimated the country’s 2026 bean crop at 3.0 million tonnes, up 0.9% from the 2025 harvest [3]. Dehydrated beans can gain wider use in soups, meal kits, and dry mixes because they are easy to store, measure, and prepare.
What supports UK adoption?
6.5% CAGR, supported by food production and convenient meal formats.
The UK has a large supply base for field beans and dry peas, giving food companies access to ingredients for different products. Defra reported in September 2026 that peas harvested dry and field beans covered 202,000 hectares in 2025 [4]. Dehydrated beans fit well in soups and prepared meals because measured portions help kitchens and food companies keep cooking time and batch size consistent.
How is Japan developing demand?
5.9% CAGR, supported by well-known dry-bean foods and packaged uses.
Adzuki and kidney beans are already familiar ingredients in many Japanese foods. In February 2026, the Ministry of Agriculture, Forestry and Fisheries reported that dry kidney bean production reached 5,430 tonnes in 2025, with Hokkaido supplying 95% of the national total [5]. Dehydrated beans provide packaged-food companies with an easy-to-store option that gives consistent cooking results while keeping the familiar bean base.
What supports Germany's growth?
4.9% CAGR, supported by domestic pulse supply and food-processing use.
Germany has an established pulse-growing sector that provides a local supply base for bean ingredients. Destatis reported in December 2025 that 65,000 hectares of organic farmland were used to grow pulses for grain [6]. Dehydrated beans are well suited to soups and prepared meals because they are easy to store and give food companies better control over cooking time.
How is the USA scaling demand?
4.5% CAGR, supported by broad dry-bean production and convenient food use.
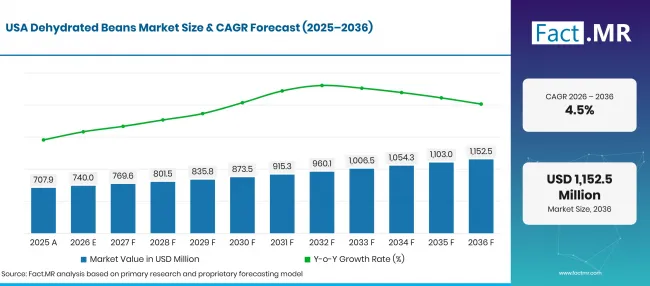
Dehydrated Beans Market Forecast Global | Source: Fact.MR
The USA has a large dry-bean production base that supplies beans for many food products. USDA reported in January 2026 that dry edible bean production reached 26.9 million cwt in 2025, with 1.33 million acres harvested [1]. Dehydrated beans can attract buyers by offering faster cooking and easy pantry storage.
Who leads the Dehydrated Beans Market?
Harmony House Foods and Van Drunen Farms have direct dehydrated-bean coverage, while BCFoods add broader dehydrated-ingredient and pulse capabilities.
Harmony House Foods offers pre-cooked dehydrated black, kidney, navy, and pinto beans in packs for households and bulk buyers. Van Drunen Farms supplies dried and powdered black bean ingredients, while Mother Earth Products and Kiril Mischeff offer pre-cooked dehydrated beans for different food uses.
BCFoods supplies dehydrated food ingredients for industrial customers, although its current public product range does not clearly show the same direct range of dehydrated beans. Specialist suppliers mainly compete on faster cooking, consistent texture, and pack sizes that suit different food applications.
Which companies are the key providers?
Harmony House Foods and Van Drunen Farms are direct providers, while Mother Earth Products, Kiril Mischeff, and BCFoods are also profiled.
- Harmony House Foods, Inc.
- Van Drunen Farms
- Mother Earth Products
- Kiril Mischeff
- BCFoods, Inc.
Bibliography
- [1] U.S. Department of Agriculture, National Agricultural Statistics Service. (2026, January 12). Crop Production 2025 Summary.
- [2] Office for National Statistics. (2026, July 24). UK manufacturers’ sales by product: 2025.
- [3] Brazilian Institute of Geography and Statistics (IBGE). (2026, February 12). Em janeiro, IBGE prevê safra de 342,7 milhões de toneladas para 2026 [In January, IBGE forecasts a harvest of 342.7 million tonnes for 2026].
- [4] Department for Environment, Food & Rural Affairs. (2026, September 3). Agriculture in the United Kingdom 2025: Chapter 2 – Structure of industry.
- [5] Ministry of Agriculture, Forestry and Fisheries of Japan. (2026, February 27).[2025 planted area and harvest volume for adzuki beans, kidney beans and peanuts (dry seed)].
- [6] Statistisches Bundesamt (Destatis). (2025, December 5). Ökologischer Landbau in Deutschland: Ackerland und Dauergrünland [Organic farming in Germany: Arable land and permanent grassland].
- [7] BCFoods. (2025, October 6). BCFoods Announces Expansion to New Warehouse Facility in Bolingbrook, Illinois.
This Report Answers
- The report explains how dehydrated beans are sold by product type, application and distribution channel.
- Segment analysis identifies Black Beans, Food Industry and Supermarkets/Hypermarkets as the 2026 share leaders.
- Country analysis compares Brazil, the UK, Japan, Germany and the USA using crop supply, food processing and cooking habits.
- Competitive analysis reviews direct dehydrated-bean suppliers alongside broader pulse and dehydrated-ingredient companies.
- Product analysis covers black, kidney, pinto and navy beans, while wider fruit and vegetable processing gives context for dehydrated food production and ingredient handling.
- Application analysis covers food manufacturing and foodservice, while adjacent plant protein ingredients and protein ingredients help frame how bean ingredients fit wider formulation needs.
- Channel analysis reviews supermarkets, online stores and specialty stores, while related dried fruit products show how shelf-stable products move through similar retail channels.
- Official crop data and company checks support the forecast framework, while the low-moisture food category provides added context for shelf-stable dry foods.
What does the Dehydrated Beans Market cover?
Pre-cooked or processed black, kidney, pinto, navy, and other beans sold in shelf-stable dehydrated formats for food preparation.
According to Fact.MR analysis, the market covers beans dehydrated after cooking or other preparation so they rehydrate faster than standard dry beans. Whole beans and flakes serve food manufacturing, foodservice and household use. Pieces and powders add more format choices.
The boundary is narrower than the wider pulses category. Ordinary uncooked dry beans and canned beans fall outside the core revenue scope unless they are sold in a clearly dehydrated or instant format.
What is included in the scope?
Dehydrated bean products used in packaged foods, foodservice recipes, retail pantry products, and shelf-stable meal systems.
Coverage includes black, kidney, pinto, navy and other beans in whole, flake, piece or powder formats. Canned legumes provide a useful adjacent convenience format, while pulse flour applications show how beans move into milled dry systems. Adzuki beans provide a bean-specific comparison for traditional dry-bean use.
What is excluded from the scope?
Standard uncooked dry beans, canned beans, fresh green beans, and frozen bean products are outside the core scope.
The assessment excludes ordinary uncooked dry beans that require long soaking and cooking, while canned, retort-pouch, frozen and fresh green beans are outside the revenue boundary. Bean flour is treated as an adjacent category unless sold as a dehydrated bean ingredient.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report’s scope and coverage?
Dehydrated Beans Market Forecast Global | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Pre-cooked or otherwise processed beans with moisture removed to create shelf-stable whole beans, flakes, pieces, or powders that rehydrate before or during food preparation. |
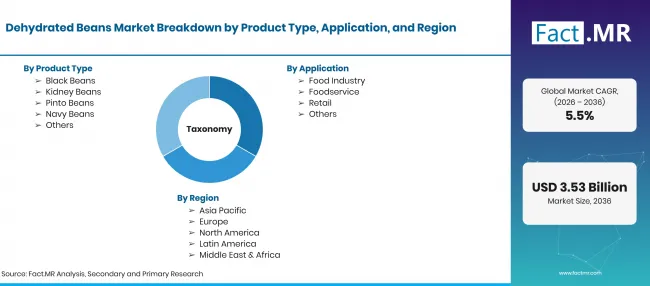
| Product Type | Black Beans; Kidney Beans; Pinto Beans; Navy Beans; Others |
| Application | Food Industry; Foodservice; Retail; Others |
| Distribution Channel | Supermarkets/Hypermarkets; Online Stores; Specialty Stores; Others |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | Brazil; UK; Japan; Germany; USA |
| Key Companies Profiled | Harmony House Foods, Inc.; Van Drunen Farms; Mother Earth Products; Kiril Mischeff; BCFoods, Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using bean crop availability, dehydration formats, application mix, retail and foodservice use, country growth, and company portfolio review. |
How is the market segmented?
-
By Product Type:
- Black Beans
- Kidney Beans
- Pinto Beans
- Navy Beans
- Others
-
By Application:
- Food Industry
- Foodservice
- Retail
- Others
-
By Distribution Channel:
- Supermarkets/Hypermarkets
- Online Stores
- Specialty Stores
- Others
-
By Region:
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa