- Market Value (2025): USD 1.4 Bn
- Estimated Value (2026): USD 1.6 Bn
- Forecast Value (2036): USD 6.8 Bn
- CAGR (2026-2036): 15.4%
What is the Microplastic-Free Soluble Films Market forecast to be worth by 2036?
USD 1.6 billion in 2026 to USD 6.8 billion by 2036 at a 15.4% CAGR.
- The Microplastic-Free Soluble Films Market crossed a valuation of USD 1.4 billion in 2025.
- Demand is projected to increase from USD 1.6 billion in 2026 to USD 6.8 billion by 2036.
- The market is set to grow at a 15.4% CAGR from 2026 to 2036 as soluble dose packs spread across cleaning, farm and specialty uses.
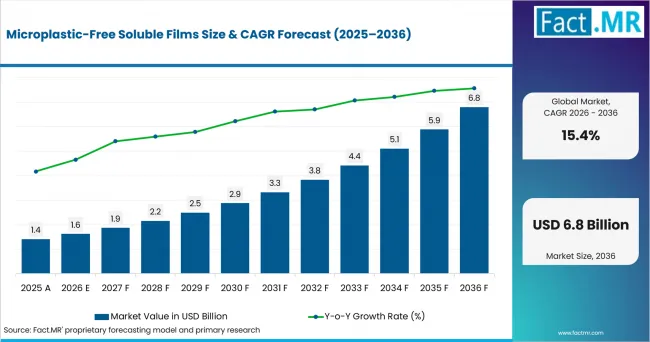
Microplastic Free Soluble Films Value Analysis | Source: Fact.MR
What are the defining numbers behind Microplastic-Free Soluble Films Market growth?
An absolute opportunity of USD 5.2 billion by 2036. PVOH/PVA leads Material Platform. Cold-water film leads Dissolution. Unit-dose pouches lead Use.
- Demand Drivers in the Market
- Home-care teams need films that stay strong in the pack. The same film must dissolve at normal wash temperatures.
- Agrochemical makers use soluble packs for measured doses. The pack enters a spray tank or mixing step with less direct handling.
- Hygiene teams test soluble materials for use in wet systems. They check how the material breaks down after use and moves through wastewater.
- Food teams use soluble sachets for measured ingredients. The sachet can enter a water-based process with the product. Chemical users apply the same idea when dose control adds value.
- Key Segments Analyzed
- By Material Platform: PVOH/PVA film is expected to hold 33.0% share in 2026. It forms films well and its water release can be tuned for detergent and dosing uses.
- By Dissolution: Cold-water film is expected to hold 34.0% share in 2026. It can release in cool or room-temperature water, which fits many home-care doses.
- By Use: Unit-dose pouches are expected to hold 37.0% share in 2026. The format gives a set dose and goes straight into water-based use.
- By Environmental Position: Microplastic-free claim is expected to hold 29.0% share in 2026. Choice depends on clear proof of water release and residue after use.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR states: “Sales depend on more than water solubility. Film must run well on packing lines and release at the right temperature. Demand is expected to favor grades backed by clear use and end-of-life data.”
- Strategic Implications
- Film makers should state test temperatures for each grade. They should also show the intended use. Clear test terms help teams compare films on the same basis.
- Home-care brands should test film fit with concentrated liquids. Water in the formula can change pack strength during storage.
- Agrochemical firms should match pack design to dose size and handling steps. A pack should enter the mixing stage as one measured unit.
- Hygiene teams should test how a film behaves in wastewater. They should also check how it runs on production lines. The disposal route depends on the use.
France is forecast at 16.2% CAGR through 2036. China follows at 15.5%. The USA and Japan each record 15.0%, while Germany reaches 14.8%. Each market has its own mix of pack demand, handling needs and end-of-life checks.
How does the Microplastic-Free Soluble Films Market break down by segment?
Unit-dose pouches lead Use with 37.0% share in 2026. Cold-water grades lead Dissolution with 34.0%.
Which Material Platform dominates?
PVOH/PVA is expected to hold 33.0% share in 2026.
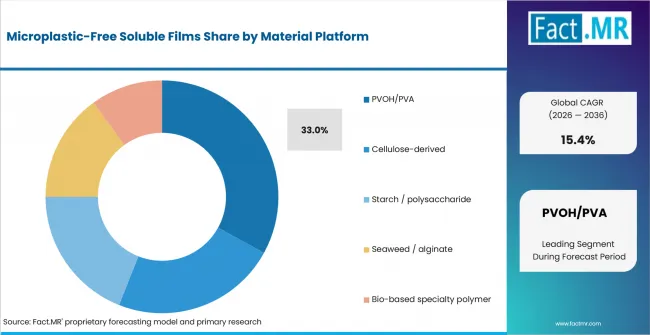
Microplastic Free Soluble Films Analysis By Material Platform | Source: Fact.MR
PVOH/PVA is expected to lead because it makes flexible film and dissolves in water. Kuraray lists soluble unit-dose detergent systems as a PVOH use. Farm and other dose packs add more uses.
Cellulose-derived and starch-based films widen the choice of materials. Seaweed-based films add another route. These options suit uses where source material or end-of-life behavior guides film choice.
What leads the Dissolution segment?
Cold-water leads with 34.0% share in 2026.
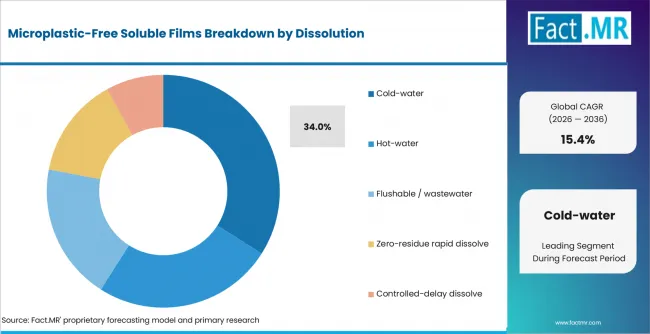
Microplastic Free Soluble Films Analysis By Dissolution | Source: Fact.MR
Cold-water grades are expected to lead because many wash cycles start in cool water. Hot-water grades suit uses where the pack must stay intact for longer.
Wastewater formats focus on how the film moves after use. Fast-dissolve grades shorten release time. Delayed grades keep the pack intact for a set period.
How does Application shape demand?
Unit-dose pouches account for 37.0% share in 2026.
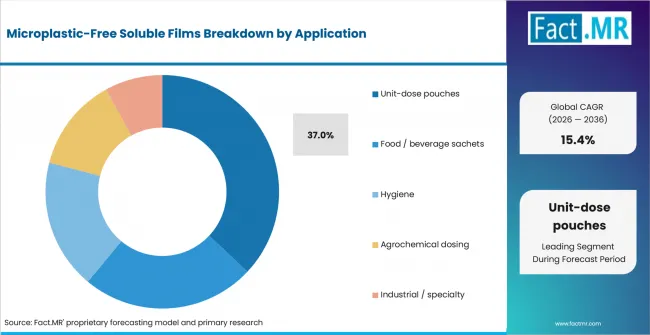
Microplastic Free Soluble Films Analysis By Application | Source: Fact.MR
Unit-dose pouches are expected to lead because they give containment and dose control. The format is common in laundry and dishwashing. It also suits strong chemicals that mix with water.
Agrochemical packs use the same measured-dose idea. Food sachets need food-contact review. Aquapak reported in March 2025 that Hydropol was being used in a dissolvable nonwoven material for wet wipes. The company also documented a separate sanitary-pad application in which Hydropol coating or film is applied to nonwoven materials in place of conventional plastic.
What supports the Environmental Position segment?
Microplastic-free claim is expected to hold 29.0% share in 2026.
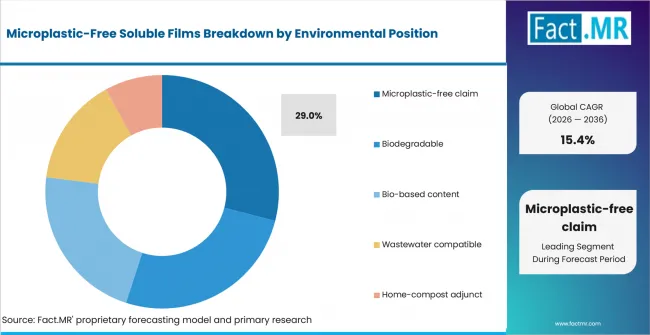
Microplastic Free Soluble Films Analysis By Environmental Position | Source: Fact.MR
Microplastic-free claims are expected to lead when users want clear proof of what remains after the film dissolves.
Bio-based and biodegradable claims answer other needs. Wastewater fit is a separate issue. Home-compost claims add another route after use. Film makers need tests that fit each claim.
What is accelerating Microplastic-Free Soluble Films Market adoption, and what is holding it back?
Dose control supports use; claim proof and formula fit shape the pace.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Unit-dose home-care formats | +2.1% | Global | Short term (<= 2 years) |
| Controlled agrochemical dosing | +1.7% | USA, China, Europe | Medium term (2-4 years) |
| Packaging end-of-life scrutiny | +1.3% | Europe, Japan | Medium term (2-4 years) |
| Cold-water dissolution performance | +1.0% | Global | Short term (<= 2 years) |
| Wastewater-oriented hygiene concepts | +0.7% | Europe, Japan, USA | Long term (>= 4 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Food and beverage ingredient sachets | +1.2% | Global | Medium term (2-4 years) |
| Industrial chemical dosing | +0.9% | Global | Medium term (2-4 years) |
| Hygiene dispersible structures | +0.8% | Europe, Japan, USA | Long term (>= 4 years) |
| Bio-based soluble polymer grades | +0.6% | Europe, Asia | Long term (>= 4 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Environmental claim substantiation | -0.8% | Global | Short term (<= 2 years) |
| Moisture sensitivity during storage | -0.6% | Global | Medium term (2-4 years) |
| Chemical compatibility limits | -0.5% | Global | Medium term (2-4 years) |
| Application-specific disposal rules | -0.4% | Europe, USA, Japan | Long term (>= 4 years) |
Which countries are scaling the Microplastic-Free Soluble Films Market through 2036?
- The five listed country CAGRs span 1.4 percentage points. France records 16.2% and Germany records 14.8%.
- France records 16.2% CAGR as packaging rules raise the need for clear end-of-life proof.
- China follows at 15.5% as daily-use goods and set-dose packs support film demand.
- The USA and Japan each record 15.0%. Home care has a larger role in the USA. Japan adds a strong focus on resource use and waste systems.
- Germany records 14.8%. Its recycling system raises the need for proof on new soluble formats.
Similar CAGRs can come from different market needs. Product rules shape each country. The mix of home care and other uses changes the route to scale.
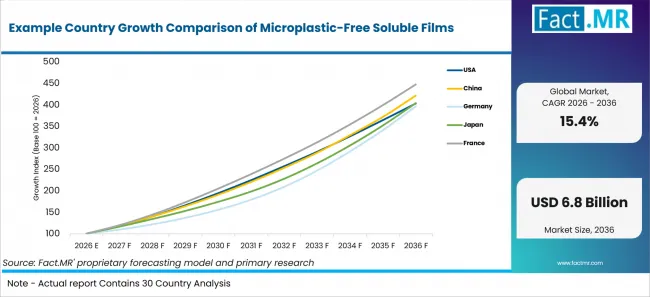
Example Country Growth Comparison Of Microplastic Free Soluble Films | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| France | 16.2% |
| China | 15.5% |
| United States | 15.0% |
| Japan | 15.0% |
| Germany | 14.8% |
What supports France adoption?
16.2% CAGR, supported by packaging rules and end-of-life proof.
France is expected to see more focus on clear end-of-life proof for packs. ADEME said in its 2026 review that 6,345 kt of household packaging and graphic papers were placed on the French market in 2024. This shows the scale of the pack system. Soluble packs can serve uses where film dissolves during use, such as home-care doses and ingredient sachets.
How is China scaling demand?
15.5% CAGR, shaped by daily-use goods and measured-dose uses.
Daily-use goods can support set-dose packs in China. The National Bureau of Statistics of China said in January 2026 that retail sales of daily necessities by firms above the designated size rose 6.3% in 2025. Farm doses add another use for packs that enter a water mix.
What supports USA adoption?
15.0% CAGR, led by established unit-dose cleaning formats.
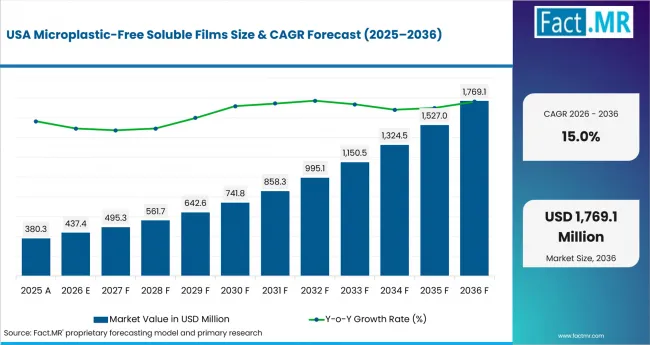
Microplastic Free Soluble Films Country Value Analysis | Source: Fact.MR
U.S. home-care brands are expected to keep using unit-dose formats. The Bureau of Labor Statistics said in September 2026 that the household cleaning products index was 2.1% higher year on year in August 2026. Film makers still compete on cool-water release and pack strength. Farm and specialty doses add more uses.
How does Japan perform?
15.0% CAGR, backed by local film skills and resource-use policy.
Japan has a broad system to sort plastic packs. In March 2026, the Ministry of the Environment said 1,434 municipalities, or 82.4%, planned separate collection of plastic containers and packaging in fiscal 2026. This puts more focus on clear routes after use. Local film skills also support cool-water and timed-release grades.
What is supporting Germany’s adoption?
14.8% CAGR, backed by strict pack rules and clear records.
German film users place high value on clear end-of-life proof. The German Environment Agency and ZSVR reported in January 2026 that about 5.5 million tonnes of packaging waste collected by the dual systems were recovered in 2024.
Who leads the Microplastic-Free Soluble Films Market?
Kuraray is an active provider through its PVOH resin business and MonoSol water-soluble films. The portfolio supports soluble unit-dose applications where films must remain stable during storage and then dissolve under defined water conditions. This positions the company across detergent dosing and other measured-use formats.
Aquapak Polymers competes through Hydropol™, which is used across soluble-film, barrier, and nonwoven applications. The material has also been applied in dissolvable hygiene structures, giving the company exposure beyond conventional detergent pouches and into wastewater-oriented formats.
LACTIPS and POLYVA complete the profiled provider set alongside Kuraray and Aquapak Polymers. The pasted source identifies both companies as market participants, although it does not provide the same level of product-specific detail for them.
Which companies are the key providers?
Key companies include Kuraray (MonoSol), LACTIPS, Aquapak Polymers, POLYVA.
- Kuraray (MonoSol)
- LACTIPS
- Aquapak Polymers
- POLYVA
Bibliography
- Directorate-General for Environment. (2025, February 11). New rules enter into force for a more sustainable and competitive packaging economy. European Commission.
- Kuraray Co., Ltd. (2025, June 23). Held management briefing on growth opportunities of PVOH resin business.
- Aquapak Polymers. (2025, March 12). Hydropol™ set to revolutionise disposable hygiene products, making them dissolvable, fully flushable, microplastic free and preventing them forming fatbergs.
- ADEME. (2026, March). Household packaging and graphic papers: Data 2024.
- National Bureau of Statistics of China. (2026, January 20). Total retail sales of consumer goods in December 2025.
- U.S. Bureau of Labor Statistics. (2026, September 11). Consumer Price Index-August 2026 (USDL-26-1496).
- German Environment Agency, & Central Agency Packaging Register. (2026, January 27). Facts against myths: Packaging waste recycling in Germany is working.
This Report Answers
- The report shows where soluble films are used. It covers film type, water release, end use and end-of-life position across five countries.
- Segment review shows the leading subsegments. It explains how film strength, water release and dose control shape choice.
- The country review covers pack rules and use in France, China, the United States, Japan and Germany.
- The company review covers six named firms. It looks at PVOH film, other soluble systems, hygiene uses and industrial dose packs.
- Use review separates detergent dose packs from food and hygiene formats. Farm and industrial uses are matched with their planned end-of-use route.
What does the Microplastic-Free Soluble Films Market cover?
The market covers soluble films that hold a product and then dissolve in water. Uses include unit-dose pouches and ingredient sachets. Hygiene formats add another route. Farm dosing adds a measured-pack use. The review keeps water solubility separate from biodegradation and microplastic claims.
What is included in the scope?
The scope covers soluble film and ready-to-use pouches when water release is part of use. It includes cool-water, hot-water, wastewater and timed-release grades when release after use is part of the design.
What is excluded from the scope?
The core scope focuses on films that dissolve during a planned use or disposal step. Conventional films and plain paper packs remain adjacent formats. Compostable films used only for composting are treated as nearby options. Reusable and recyclable packaging appears as a comparison point for material choice.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report’s scope and coverage?
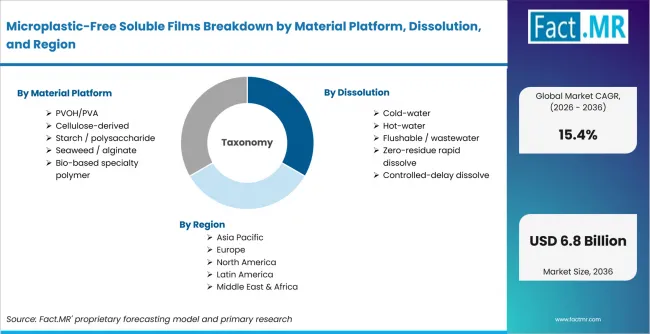
Microplastic Free Soluble Films Breakdown By Material Platform, Dissolution, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD Billion |
| Market Definition | Water-soluble film that holds a product during storage or handling and dissolves under set water conditions. The market covers claims tied to residue after use and microplastic-free positioning. |
| Material Platform | PVOH/PVA; Cellulose-derived; Starch / polysaccharide; Seaweed / alginate; Bio-based specialty polymer |
| Dissolution | Cold-water; Hot-water; Flushable / wastewater; Zero-residue rapid dissolve; Controlled-delay dissolve |
| Application | Unit-dose pouches; Food / beverage sachets; Hygiene; Agrochemical dosing; Industrial / specialty |
| Environmental Position | Microplastic-free claim; Biodegradable; Bio-based content; Wastewater compatible; Home-compost adjunct |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | France; China; United States; Japan; Germany |
| Key Companies Profiled | Kuraray (MonoSol); LACTIPS; Aquapak Polymers; POLYVA |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using end-use demand; film participation; water-release needs; country conditions; and provider portfolio checks. |
How is the market segmented?
-
By Material Platform:
- PVOH/PVA
- Cellulose-derived
- Starch / polysaccharide
- Seaweed / alginate
- Bio-based specialty polymer
-
By Dissolution:
- Cold-water
- Hot-water
- Flushable / wastewater
- Zero-residue rapid dissolve
- Controlled-delay dissolve
-
By Use:
- Unit-dose pouches
- Food / beverage sachets
- Hygiene
- Agrochemical dosing
- Industrial / specialty
-
By Environmental Position:
- Microplastic-free claim
- Biodegradable
- Bio-based content
- Wastewater compatible
- Home-compost adjunct
-
By Region:
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa

