- Market Value (2025): USD 24.6 Bn
- Estimated Value (2026): USD 25.9 Bn
- Forecast Value (2036): USD 43.7 Bn
- CAGR (2026-2036): 5.4%
What is the Frozen Finger Chips (Frozen French Fries) Market forecast to be worth by 2036?
USD 25.9 billion in 2026 to USD 43.7 billion by 2036, at a 5.4% CAGR.
- As per Fact.MR analysis, the market reached USD 24.6 billion in 2025.
- Sales are projected to move from USD 25.9 billion in 2026 to USD 43.7 billion by 2036.
- The frozen finger chips (frozen french fries) market is forecast to record a 5.4% CAGR between 2026 and 2036 as restaurant chains and households continue buying ready-to-cook fries.
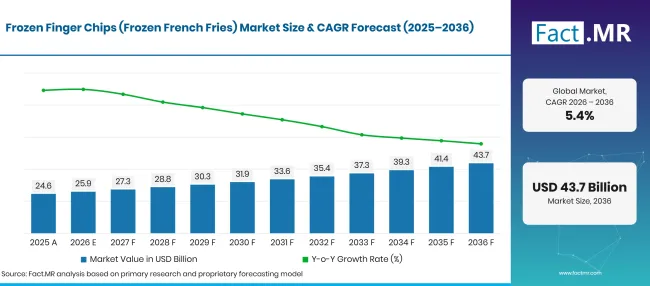
Factmr Frozen Finger Chips Frozen French Fries Market Forecast Global | Source: Fact.MR
| Year | Basis | Market Value (USD billion) |
|---|---|---|
| 2025 | Historical estimate | 24.6 |
| 2026 | Estimate | 25.9 |
| 2036 | Forecast | 43.7 |
| CAGR 2026 to 2036 | Forecast period | 5.4% |
Source: Fact.MR analysis. Updated Oct 16, 2026
What are the defining numbers behind Frozen Finger Chips Market growth?
USD 17.8 billion of absolute opportunity from 2026 to 2036, with white potato fries and foodservice forming the main sales base.
- Demand Drivers in the Market
- Restaurant kitchens need repeatable cooking results. Consistent cuts reduce uneven browning and help maintain serving portions during busy hours.
- Foodservice distributors value frozen inventory because customers place frequent orders across multiple outlets. Dependable delivery schedules and clear storage instructions protect supply when restaurant traffic changes.
- Households purchase frozen fries for convenient meals that require limited preparation. Oven and air-fryer cooking instructions make product comparison easier for shoppers using different home appliances.
- Key Segments Analyzed
- By Product Types: White Potato Fries will account for 81.4% share in 2026, reflecting their widespread use in standard restaurant portions and household packs.
- By Use Types: Food Services will hold 62.4% share in 2026, supported by repeat orders from quick-service restaurants and other meal outlets.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Frozen fries purchasing depends on the operating needs of kitchens as much as consumer taste. Buyers compare how quickly each cut reaches an even finish and whether every carton performs consistently. Producers with reliable potato sourcing and reliable cold storage are better placed to win repeat orders without relying only on lower prices.”
- Strategic Implications
- Potato growers and processors should agree on suitable varieties and storage needs before each processing season, reducing quality variation once production begins.
- Restaurant operators should review finished portions and cooking yield alongside the quoted case price, giving purchasing teams a clearer picture of serving cost.
- Cold-chain distributors should coordinate delivery windows with restaurant order patterns to preserve product condition.
- Consumer brands should explain oven and air-fryer preparation clearly on retail packs, allowing households to choose cuts that suit their cooking equipment.
Brazil is forecast to post 6.4% CAGR, followed by the United Kingdom at 5.6%. The United States is projected to record 4.9%, Japan 4.4%, and Germany 4.0% during 2026 to 2036. Different local crop conditions and distribution systems shape these outlooks.
How does the Frozen Finger Chips Market break down by segment?
White Potato Fries 81.4%; Food Services 62.4% in 2026.
Which Product Type dominates?
White Potato Fries hold a 81.4% share in 2026.
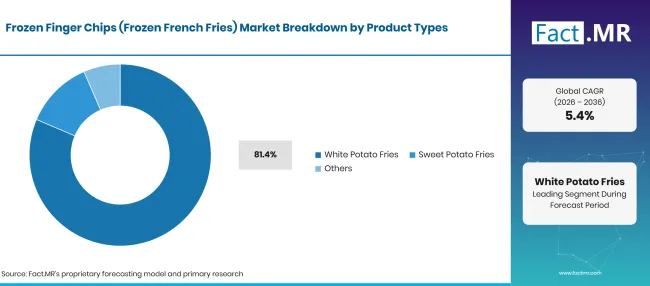
Factmr Frozen Finger Chips Frozen French Fries Market Breakdown Product Types 1 | Source: Fact.MR
| Product Types | Share (2026) |
|---|---|
| White Potato Fries (Leading segment) | 81.4% |
| Other segments combined | 18.6% |
| Total | 100.0% |
Source: Fact.MR analysis. Updated Oct 16, 2026
White potato fries cover the familiar straight-cut and related potato preparations used by restaurant chains. Processors aim for uniform colour and texture after frying, while kitchen staff evaluate portion size and preparation time. Sweet potato fries offer a different flavour and colour for menus seeking variation. Other fry formats can serve specialist menu needs, although their production runs and raw material choices vary from conventional white potatoes.
What leads the Application Types segment?
Food Services represent a 62.4% share in 2026.
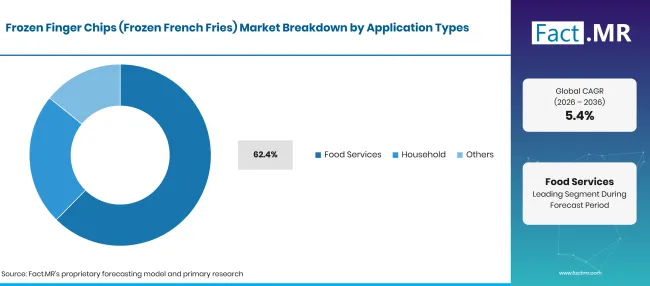
Factmr Frozen Finger Chips Frozen French Fries Market Breakdown Application Types | Source: Fact.MR
| Application Types | Share (2026) |
|---|---|
| Food Services (Leading segment) | 62.4% |
| Other applications combined | 37.6% |
| Total | 100.0% |
Source: Fact.MR analysis. Updated Oct 16, 2026
Foodservice kitchens purchase frozen fries in bulk cartons. Chain restaurants often set precise requirements for cut size and cooking method, making product consistency central to supplier reviews. Independent restaurants can favour accessible pack formats and flexible minimum orders. Household buyers commonly select smaller bags that fit domestic freezers and provide clear cooking directions.
What is accelerating Frozen Finger Chips adoption, and what is holding it back?
Regular foodservice orders support sales; potato supply variation and frozen distribution costs constrain expansion.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Chain restaurant standardization | +1.1% | Global | Medium term (2–4 years) |
| Ready-to-cook household meals | +0.9% | USA, UK, Japan | Short term (≤ 2 years) |
| Local fry processing investment | +0.8% | Brazil, Europe | Long term (≥ 4 years) |
| Consistent menu portions | +0.6% | Global | Medium term (2–4 years) |
| Frozen distribution reach | +0.5% | Latin America, Asia | Long term (≥ 4 years) |
Source: Fact.MR analysis. Updated Oct 16, 2026
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Restaurant-specific fry cuts | +0.7% | Global | Medium term (2–4 years) |
| Domestic processing capacity | +0.6% | Brazil | Long term (≥ 4 years) |
| Home air-fryer preparation | +0.5% | USA, UK, Japan | Short term (≤ 2 years) |
| Supplier crop planning | +0.4% | Germany, USA | Medium term (2–4 years) |
Source: Fact.MR analysis. Updated Oct 16, 2026
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Variable potato harvests | -0.8% | Global | Short term (≤ 2 years) |
| Cold storage and transport expense | -0.7% | Global | Medium term (2–4 years) |
| Restaurant pricing pressure | -0.5% | USA, Brazil | Short term (≤ 2 years) |
| Processing quality rejects | -0.4% | Global | Medium term (2–4 years) |
Source: Fact.MR analysis. Updated Oct 16, 2026
Which countries are scaling Frozen Finger Chips Market through 2036?
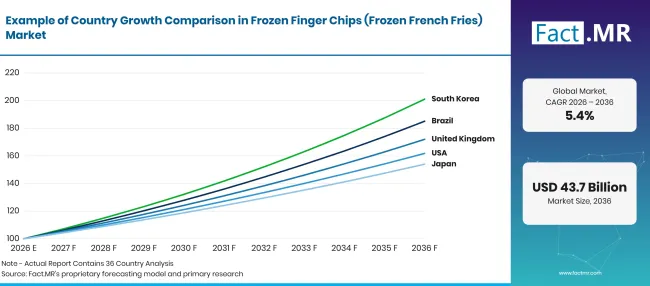
Factmr Frozen Finger Chips Frozen French Fries Market Growth Index | Source: Fact.MR
| Country | CAGR (2026–2036) |
|---|---|
| Brazil | 6.4% |
| United Kingdom | 5.6% |
| United States | 4.9% |
| Japan | 4.4% |
| Germany | 4.0% |
Source: Fact.MR analysis. Updated Oct 16, 2026
Why is Brazil expanding frozen French fry processing?
6.4% CAGR, driven by local processing investment and a growing domestic supply base.
Brazil is adding frozen fry capacity closer to restaurant and retail customers. McCain Foods announced an estimated R$ 1.8 billion investment at Araxá in October 2025 [2], including a new French fry line. Local processors also depend on potatoes that meet frying specifications, while shorter delivery routes can improve supply options for restaurant distributors and supermarkets.
How is the United Kingdom strengthening frozen fry sales?
5.6% CAGR, supported by foodservice demand and a sizeable domestic potato crop.
In the UK, restaurants like to use frozen chips because they can guaranty the same size portion and the same cooking performance even when they are very busy. Defra reported a potato harvest of 5.549 million tons in 2025 [4] providing processors with a quantifiable domestic raw material base. Retail sales also benefit from oven-ready and air-fryer products, while local growers support factories that require varieties suited to cutting and frying.
What supports United States frozen finger chips purchasing?
4.9% CAGR, linked to recurring foodservice orders and large-scale potato processing.
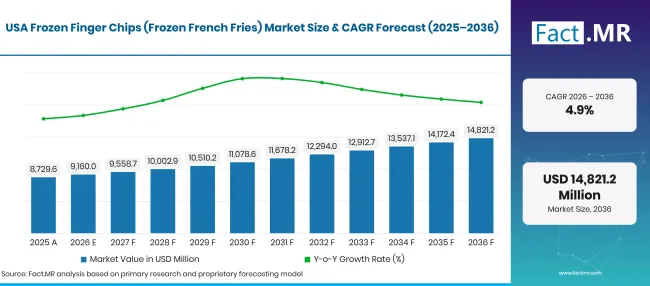
Factmr Frozen Finger Chips Frozen French Fries Market Forecast Usa | Source: Fact.MR
U.S. restaurant chains regularly purchase frozen fries that meet consistent size, cooking, and delivery requirements. The USDA Economic Research Service reported an average frozen potato supply of 58 pounds per person for 2022–2024, published in September 2025 [1]. Domestic processors also benefit from a large potato crop that supports factory intake and regular foodservice distribution.
Why does Japan remain a steady market for frozen fries?
4.4% CAGR, shaped by portion consistency, freezer distribution, and practical pack sizes.
Japanese restaurants value frozen fries that deliver repeatable cooking results in compact kitchens. The Ministry of Agriculture released its 2025 spring-planted potato statistics in February 2026 [5], helping processors plan potato grades and supply schedules. Consumer products also benefit from smaller pack sizes, while suppliers need reliable cold-chain handling for imported and locally processed potato products.
How is Germany balancing raw potato supply and frozen fry sales?
4.0% CAGR, supported by established potato production, processing, and storage infrastructure.
Germany has a large domestic potato base that supports both fresh sales and industrial processing. Destatis reported a 2025 potato harvest of 13.9 million tonnes [3]. Frozen fry manufacturers benefit from access to local farms and specialist storage, although they still need varieties that meet strict frying, shape, and solids requirements for consistent restaurant and retail products.
Who leads the Frozen Finger Chips Market?
McCain Foods, Lamb Weston, J.R. Simplot, Aviko and Farm Frites have established frozen fry product ranges.
McCain Foods serves foodservice and retail channels with frozen potato products, including French fries. Lamb Weston focuses strongly on frozen potato products for restaurant, foodservice and retail customers, while J.R. Simplot supplies frozen French fries and other prepared potato products. According to Fact.MR analysis, consistent cut size, texture and cooking performance can support repeat purchasing by restaurant and foodservice customers.
Aviko and Farm Frites also supply frozen French fries to foodservice customers. The wider company landscape includes a mix of frozen potato specialists and broader food businesses, so competitive comparisons should focus on documented French fry portfolios, customer channels and regional availability.
Which companies are the key providers?
Key companies include McCain Foods Limited; Lamb Weston Holdings; J.R. Simplot Company; Aviko Group; Farm Frites; and Himalaya Food International.
- McCain Foods Limited
- Lamb Weston Holdings
- J.R. Simplot Company
- Aviko Group
- Farm Frites
- Himalaya Food International
Bibliography
- [1] Weber, C. (2025, September 4). From fresh to frozen: Potato per capita availability changes over time. U.S. Department of Agriculture, Economic Research Service.
- [2] McCain Foods. (2025, October 29). McCain Foods to invest R$ 1.8 billion in major expansion of Araxá (MG) facility.
- [3] Statistisches Bundesamt (Destatis). (n.d.). 2025 grain and potato harvest: 45 million tons of grain and 14 million tons of potatoes.
- [4] Department for Environment, Food & Rural Affairs. (2026, September 3). Agriculture in the United Kingdom 2025: Chapter 7, crops.
- [5] Ministry of Agriculture, Forestry and Fisheries. (2026, February 10).[2025 spring-planted potato acreage, harvest and shipments].
- [6] Ministry of Agriculture, Forestry and Fisheries. (2026, February 3).[2025 sweet potato area and production].
This Report Answers
- The report assesses how white potato fries compare with sweet potato and specialist varieties in regular commercial use.
- Application analysis explains the role of foodservice buying and household freezer purchases in frozen fries sales.
- Country analysis compares Germany, Brazil, the United States, the United Kingdom and Japan.
- The competitive review examines named frozen potato processors and their foodservice or retail routes.
- The supply-chain analysis considers suitable potato varieties and temperature-controlled delivery requirements.
What does the Frozen Finger Chips Market cover?
The market covers prepared frozen French fries sold to commercial kitchens and households. It includes white potato fries and sweet potato fry products, with other formats counted where sold as frozen finger chips. Related category detail is available in Fact.MR coverage of frozen potato products and potato snacks.
What is included in the scope?
Included sales cover frozen French fries in bulk foodservice packs and consumer retail packs. Restaurant supply contracts and distribution orders form part of the commercial channel, while household purchases occur through food retail. White potato fry formats and sweet potato fries remain within the product categories. Products sold under a separate prepared meal category enter only when the frozen fries are identifiable as the item being sold. Country-specific comparison is available for frozen French fries in India.
What is excluded from the scope?
Fresh table potatoes are excluded until processed into frozen French fries. Potato crisps and dehydrated potato flakes fall outside the frozen fry product boundary. Standalone cold-storage services and equipment sales are also excluded because they do not represent a sale of the finished food item. Frozen hash browns and other potato specialties are considered adjacent products unless they meet the market definition of frozen finger chips.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
Segmentation
What is the report’s scope and coverage?
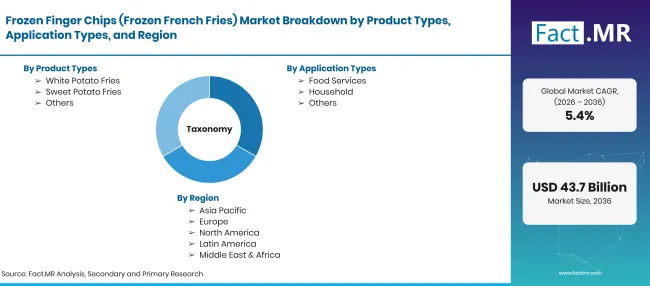
Factmr Frozen Finger Chips Frozen French Fries Market Taxonomy | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion in 2026 to USD billion by 2036 at CAGR |
| Market Definition | Frozen prepared French fries made from white potatoes, sweet potatoes and other fry varieties. |
| Product Types | White Potato Fries; Sweet Potato Fries; Others |
| Application Types | Food Services; Household; Others |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | Germany; Brazil; United States; United Kingdom; Japan |
| Companies Profiled | McCain Foods Limited; Lamb Weston Holdings; J.R. Simplot Company; Aviko Group; Farm Frites; and Himalaya Food International |
| Forecast Period | 2026 to 2036 |
| Approach | Market forecast scenarios, product and buyer comparisons, company releases and official crop statistics |
Source: Fact.MR analysis. Updated Oct 16, 2026
How is the market segmented?
-
By Product Types
- White Potato Fries
- Sweet Potato Fries
- Others
-
By Application Types
- Food Services
- Household
- Others
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa
Frequently Asked Questions
How big is the frozen finger chips market in 2026?
What is the CAGR from 2026 to 2036?
Which product type leads?
Which application leads?
Which companies participate in frozen finger chips?
Who worked on this report


Preview the report firsthand - request a free sample
Free SampleGet the brochure for pricing and purchase details
Download PDF