- Market Value (2025): USD 167.5 Mn
- Estimated Value (2026): USD 175.2 Mn
- Forecast Value (2036): USD 274.4 Mn
- CAGR (2026-2036): 4.6%
What is the Headlight Beam Tester Market forecast to be worth by 2036?
USD 175.2 million in 2026 to USD 274.4 million by 2036 at a 4.6% CAGR.
- In 2025, the headlight beam tester market was worth USD 167.5 million, with most revenue coming from replacement purchases at established inspection lanes and workshops.
- Revenue will move from USD 175.2 million in 2026 to USD 274.4 million by 2036 as inspection authorities tighten headlamp aim checks for LED and adaptive lighting.
- A 4.6% CAGR reflects a replacement-led market in which each regulatory change to headlamp testing brings a fresh round of equipment upgrades.
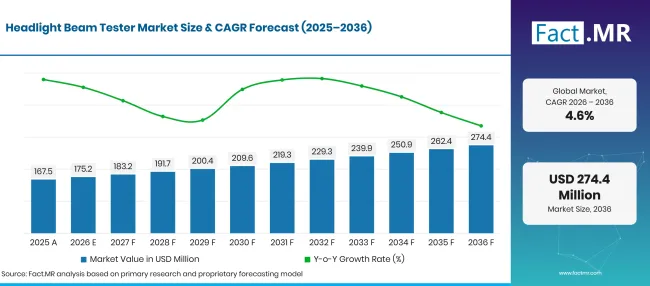
Headlight Beam Tester Market Forecast Global | Source: Fact.MR
| Year | Basis | Market Value (USD million) |
|---|---|---|
| 2025 | Actual | 167.5 |
| 2026 | Estimate | 175.2 |
| 2036 | Forecast | 274.4 |
| CAGR 2026 to 2036 | Forecast period | 4.6% |
Source: Fact.MR analysis. Updated Nov 2, 2026
What are the defining numbers behind Headlight Beam Tester Market growth?
The 2026 to 2036 period will add USD 99.2 million in new value, with digital testers for inspection centers and passenger car workshops taking most of it.
- Demand Drivers in the Market
- Periodic roadworthiness testing creates steady equipment demand, since every inspection lane needs a calibrated headlamp tester. The European Commission’s 2025 roadworthiness package proposes annual periodic technical inspections for cars aged ten years or more [1]. Any rise in test frequency adds lane hours and brings forward replacement cycles.
- LED retrofits are changing what inspectors must check at the beam pattern. From 14 October 2026, the UK MOT manual accepts ECE approved LED replacement bulbs in compatible halogen headlamp units when the bulb carries a manufacturer approval sticker [2]. Testers that read LED cut-off lines and glare zones accurately gain ground as a result.
- Regulators are also revisiting headlamp aim itself. In October 2026 the National Highway Traffic Safety Administration opened a review of US lighting standards covering glare, LED technology and automatic high beams [3]. Headlamp height, aim and test procedures are also under review. Clearer aim rules tend to push repair shops toward measured alignment.
- Commercial vehicle inspection adds a second demand stream. The DVSA heavy goods vehicle inspection manual revised its headlamp aim check from 1 April 2026, so any adjustment outside the cab adjuster now counts as a deficiency [4]. Truck and bus test stations need testers that handle tall mounting heights and wide track widths.
- Key Segments Analyzed
- By Product Type: Digital Headlight Beam Tester will hold 61.4% share in 2026 because camera units record cut-off position and intensity without operator judgment.
- By Application: Vehicle Inspection Centers will account for 38.7% of 2026 value, given that every periodic test lane carries a headlamp station.
- By Vehicle Type: Passenger Cars will capture 63.8% of 2026 revenue, as cars form the bulk of vehicles passing through annual and biennial tests.
- By Sales Channel: Offline will command 74.3% of 2026 sales, since lane installation and on-site calibration still require a distributor or service engineer.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Headlight beam testers are being replaced faster than their mechanical life would suggest. Lighting rules now change more often than inspection equipment does. Through 2036, buyers will favor camera-based testers with software that can be updated as LED, matrix and adaptive beam patterns evolve. Suppliers with dense calibration and service networks will win the inspection lane contracts that set the pace of this market.”
- Strategic Implications
- Manufacturers should build testers around updatable software and vehicle databases so that new beam patterns can be added without a hardware change.
- Distributors should bundle installation, annual calibration and operator training, as inspection authorities audit equipment accuracy as closely as test results.
- Inspection centers and workshops should plan replacements around regulatory dates such as Japan’s low-beam switch and the UK LED replacement bulb rule, not around equipment age alone.
- Investors should look at suppliers with approvals from inspection authorities and vehicle makers, since these listings decide which brands can sell into regulated lanes.
Growth across the five countries follows how fast each one is rewriting its headlamp rules. The United States leads at 5.7%, helped by a large vehicle fleet and a federal review of lighting standards. Germany follows at 5.3%, where a dense network of inspection stations and early matrix LED uptake keep upgrades frequent. Japan reaches 4.8% after its nationwide switch to low-beam measurement, a one-time change that lifts demand and then settles. The United Kingdom posts 4.5%, reflecting MOT rule changes on a mature lane base. Brazil trails at 3.3%, given that periodic inspection is not yet uniform across states, so purchases come mainly from workshops.
How does the Headlight Beam Tester Market break down by segment?
Digital Headlight Beam Tester will lead Product Type at 61.4%; Vehicle Inspection Centers will head Application at 38.7%; Passenger Cars will hold Vehicle Type at 63.8%; Offline will lead Sales Channel at 74.3% in 2026.
Which Product Type leads?
Digital Headlight Beam Tester takes 61.4% of 2026 sales.
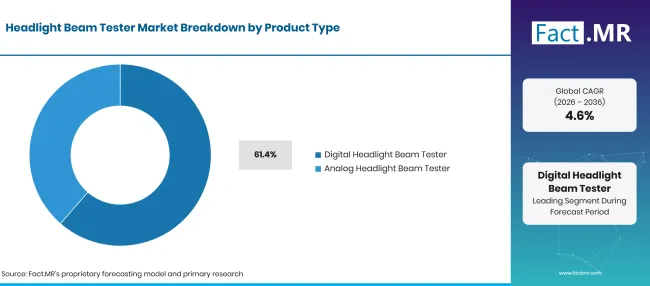
Headlight Beam Tester Market Breakdown Product Type | Source: Fact.MR
| Product Type | Share (2026) |
|---|---|
| Digital Headlight Beam Tester (Leading segment) | 61.4% |
| Other segments combined | 38.6%* |
| Total | 100.0% |
Source: Fact.MR analysis. Updated Nov 2, 2026
Camera-based units capture the beam image, locate the cut-off line and report deviation in numbers that an auditor can check later. Inspection lanes rely on that record to show why a vehicle passed or failed. Digital testers also store pattern libraries for halogen, xenon and LED lamps, which links them closely to the wider automotive lighting upgrade cycle. Analog testers with optical screens and a Fresnel lens keep a place in smaller workshops where cost decides the purchase. They need no software licenses and few spare parts. Their weakness is reading the soft cut-off of some LED modules, so many shops buy a digital unit once their vehicle mix shifts toward newer models.
What supports Vehicle Inspection Centers within Application?
Vehicle Inspection Centers represent 38.7% of 2026 revenue.
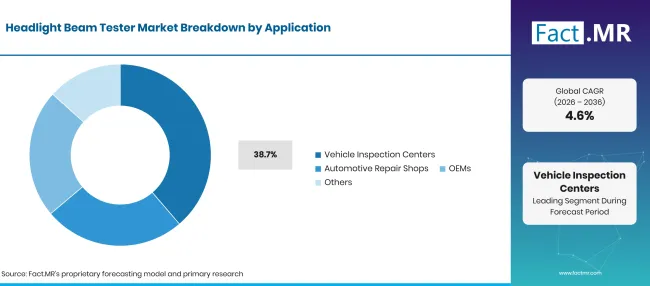
Headlight Beam Tester Market Breakdown Application | Source: Fact.MR
| Application | Share (2026) |
|---|---|
| Vehicle Inspection Centers (Leading segment) | 38.7% |
| Other segments combined | 61.3%* |
| Total | 100.0% |
Source: Fact.MR analysis. Updated Nov 2, 2026
Statutory test stations buy testers in volume and replace them when rules change. The European Parliamentary Research Service notes that the Commission’s impact assessment links the roadworthiness package to about 7,000 lives and 65,000 serious injuries saved between 2026 and 2050 [1]. Safety targets of this kind keep headlamp checks firmly inside the test protocol. Automotive repair shops form the next customer group, using testers after headlamp replacement and front-end work. Demand from collision repair services is steady because almost every front-end repair ends with an aim check. OEM plants use testers on end-of-line stations, while fleet depots and training schools form the remaining user base.
How does Vehicle Type shape demand?
Passenger Cars account for 63.8% of 2026 value.
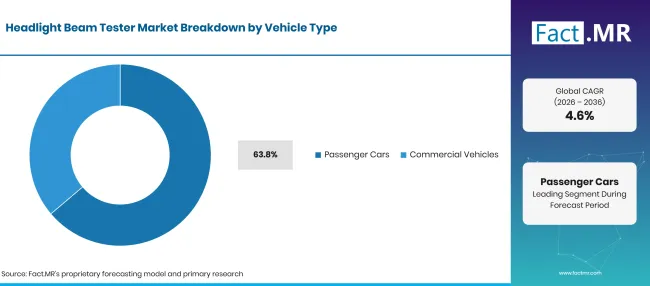
Headlight Beam Tester Market Breakdown Vehicle Type | Source: Fact.MR
| Vehicle Type | Share (2026) |
|---|---|
| Passenger Cars (Leading segment) | 63.8% |
| Other segments combined | 36.2%* |
| Total | 100.0% |
Source: Fact.MR analysis. Updated Nov 2, 2026
Cars pass through periodic inspection far more often than any other class, and their headlamps are where LED and matrix technology arrived first. Workshops that fit ADAS aftermarket equipment often add a digital headlamp tester in the same bay, since both jobs need a level floor and accurate vehicle alignment. Trucks, buses and vans need testers with taller columns and wider working ranges. The DVSA heavy goods vehicle manual’s April 2026 revision of the headlamp aim check shows how closely regulators watch this class [4]. Fleet operators tend to buy fewer units, though each one costs more owing to height adjustment and rail systems.
What role does Offline play within Sales Channel?
Offline captures 74.3% of 2026 sales.
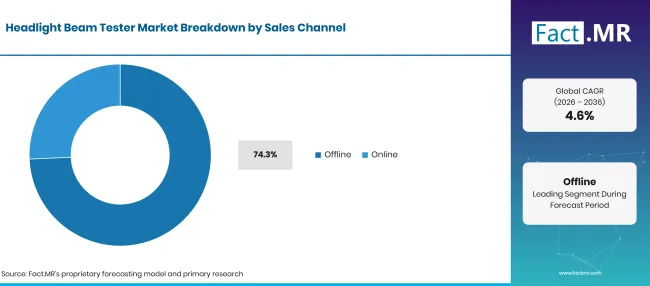
Headlight Beam Tester Market Breakdown Sales Channel 1 | Source: Fact.MR
| Sales Channel | Share (2026) |
|---|---|
| Offline (Leading segment) | 74.3% |
| Other segments combined | 25.7%* |
| Total | 100.0% |
Source: Fact.MR analysis. Updated Nov 2, 2026
Installation decides channel choice in this market. A tester has to be leveled on rails or a calibrated floor plate, and inspection authorities expect a certificate of calibration before the lane opens. Distributors and direct sales teams supply that service, which keeps most orders in the offline channel. Online channels work for portable units, replacement parts and software licenses. Buyers who already know the specification use web catalogues to compare features. Digital testers linked to forward camera sensing systems calibration tools are still sold through dealers because setup needs trained staff.
What is accelerating Headlight Beam Tester Market adoption, and what is holding it back?
New rules on headlamp aim, LED retrofits and inspection frequency are bringing forward tester replacement in Europe, the United States and Japan. Camera-based units also suit workshops that want digital records. On the other side, digital tester prices, level floor needs and annual calibration costs slow purchases at small garages. The drag is stronger where periodic inspection is not mandatory.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Periodic roadworthiness testing and stricter headlamp aim checks | +1.2% | Global | Short term (<=2 years) |
| Spread of LED, matrix and adaptive headlamps in the car parc | +0.9% | Western Europe, North America, East Asia | Medium term (2-4 years) |
| Headlamp aim checks after collision and front-end repairs | +0.7% | Global | Medium term (2-4 years) |
| Digital record keeping at inspection lanes | +0.5% | Western Europe, North America, East Asia | Long term (>=4 years) |
Source: Fact.MR analysis. Updated Nov 2, 2026
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Software-updatable testers for adaptive and matrix headlamps | +0.8% | Western Europe, North America, East Asia | Short term (<=2 years) |
| New inspection lanes in markets expanding periodic testing | +0.6% | Latin America, South Asia & Pacific | Medium term (2-4 years) |
| Portable testers for mobile and small workshops | +0.4% | Global | Medium term (2-4 years) |
| Calibration and service contracts for installed testers | +0.3% | Western Europe, North America, East Asia | Long term (>=4 years) |
Source: Fact.MR analysis. Updated Nov 2, 2026
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| High purchase price of camera-based digital testers | -0.6% | Global | Short term (<=2 years) |
| Annual calibration and level floor requirements | -0.4% | Global | Short term (<=2 years) |
| Differences in beam patterns across vehicle models | -0.3% | Western Europe, North America, East Asia | Medium term (2-4 years) |
| Limited periodic inspection coverage in some emerging markets | -0.2% | Latin America, South Asia & Pacific | Long term (>=4 years) |
Source: Fact.MR analysis. Updated Nov 2, 2026
Which countries are scaling the Headlight Beam Tester Market through 2036?
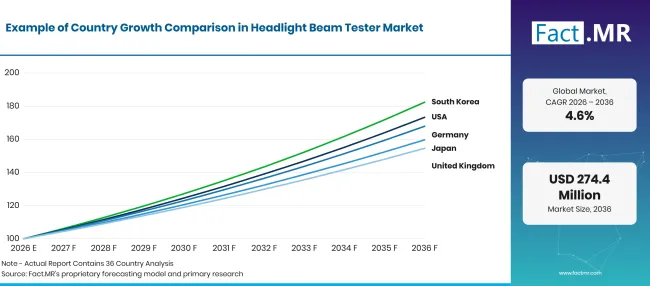
Headlight Beam Tester Market Growth Index | Source: Fact.MR
| Country | CAGR (2026 to 2036) |
|---|---|
| United States | 5.7% |
| Germany | 5.3% |
| Japan | 4.8% |
| United Kingdom | 4.5% |
| Brazil | 3.3% |
Source: Fact.MR analysis. Updated Nov 2, 2026
What is supporting United States adoption?
5.7% CAGR, driven by a large registered fleet and a federal review of headlamp aim rules.
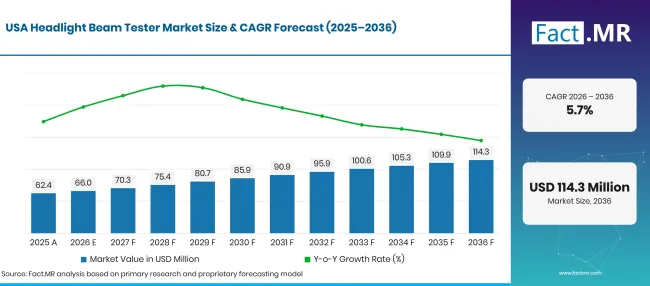
Headlight Beam Tester Market Forecast Usa | Source: Fact.MR
The Federal Highway Administration counts 298 million registered motor vehicles in the United States in 2024, about 88 for every 100 residents [5]. That base keeps dealer service bays and collision shops busy with headlamp replacements. Most US states do not run periodic safety inspections, so workshops and OEM plants buy more testers than inspection lanes do. The October 2026 lighting review gives these shops a reason to move from wall screens to measured aim [3].
How is Germany developing demand?
5.3% CAGR, backed by a dense inspection network and early uptake of matrix LED lighting.
Germany had about 49.5 million passenger cars on 1 January 2026, up from 49.3 million a year earlier [6]. Car density reached 593 per 1,000 inhabitants. Every car faces the general inspection (HU) at regular intervals, and the headlamp check there uses a leveled test area. Domestic tester makers supply both inspection organizations and dealer workshops, which gives the country a short replacement cycle.
What supports Japan’s adoption?
4.8% CAGR, reflecting the nationwide shift to low-beam headlamp measurement.
From 1 August 2026, Japan’s transport ministry (MLIT) moved all vehicles made on or after 1 September 1998 to low-beam measurement at inspection [7]. The change had first been planned for August 2024. Shaken test lanes and certified workshops had to confirm that their testers read low-beam cut-off lines. That deadline concentrated purchases in 2025 and 2026, and later demand will follow normal replacement.
How is the United Kingdom scaling demand?
4.5% CAGR, as MOT rule changes refresh a mature base of test lanes.
There were 42.3 million licensed vehicles in the United Kingdom at the end of 2025, and the average car was 10 years old [8]. Older cars need more headlamp repairs, which keeps MOT stations and garages using their testers daily. New registrations rose 12.0% in April to June 2026 compared with a year earlier, adding cars with LED lamps to the future test pool [9].
How does Brazil perform?
3.3% CAGR, with demand coming mainly from workshops and fleet operators.
The National Traffic Secretariat (Senatran) publishes monthly national fleet tables, and its 2025 series runs through December 2025 [10]. Brazil has a large and aging fleet, yet periodic safety inspection is not applied in the same way across states. Testers therefore sell mostly to dealer workshops, bus and truck operators and inspection firms tied to vehicle transfers. Price and access to local calibration support decide most purchases.
Who leads the Headlight Beam Tester Market?
Competition falls into two tiers. The first holds German specialists with long inspection-lane histories: MAHA, Beissbarth and FORVIA HELLA, whose Hella Gutmann Solutions unit sells headlamp testers.
These firms compete on measurement accuracy, approvals from vehicle makers and dense service networks. MAHA used Automechanika 2026 to show TrueLight MLT, a new method for testing modern headlamp systems [11]. Hella Gutmann Solutions launched the camera-based SEG-Tool PRO and the analog SEG-Tool PLUS in September 2026 as successors to its SEG IV and SEG V series [12]. The second tier covers regional and channel specialists. Capelec supplies the CAP2600 camera tester for French and export inspection lanes, Anzen Motor Car serves Japan’s shaken stations with automatic testers, and Snap-on sells a DVSA approved tester through its UK workshop network. This tier wins on price, local approvals and dealer reach. As lighting grows more complex, software depth and vehicle-maker approvals will decide who supplies the next generation of inspection lanes.
Which companies are the key providers?
Key companies in the Headlight Beam Tester Market include FORVIA HELLA, MAHA, Beissbarth, Snap-on, Capelec and Anzen Motor Car.
- FORVIA HELLA
- MAHA
- Beissbarth
- Snap-on
- Capelec
- Anzen Motor Car
Bibliography
- [1] European Parliamentary Research Service. (2026, January). Roadworthiness package.
- [2] Driver and Vehicle Standards Agency. (2026, October 14). Updates: MOT inspection manual: cars and passenger vehicles.
- [3] National Highway Traffic Safety Administration. (2026, October 6). Trump’s Transportation Department Moves to Modernize Outdated Vehicle Lighting Standards, Make America’s Roads Safer.
- [4] Driver and Vehicle Standards Agency. (2026, April 1). Heavy goods vehicle inspection manual.
- [5] Federal Highway Administration. (2026, July 31). Vehicles: Our Nation’s Highways 2026.
- [6] Statistisches Bundesamt. (2026, July 22). Pkw-Dichte 2026 erneut gestiegen.
- [7] Ministry of Land, Infrastructure, Transport and Tourism. (2026, May). Switching to low-beam measurement: headlamp inspection using headlight testers.
- [8] Department for Transport. (2026, April 29). Vehicle licensing statistics, United Kingdom: 2025.
- [9] Department for Transport. (2026, September 23). Vehicle licensing statistics: April to June 2026.
- [10] Secretaria Nacional de Trânsito. (2026, March 30). Frota de Veículos: 2025.
- [11] MAHA. (2026, August 18). FUTURE STARTS NOW. Experience the Workshop of Tomorrow.
- [12] FORVIA HELLA. (2026, September 8). Automechanika 2026: Hella Gutmann Solutions Sets New Standards with the SEG-Tool PRO and SEG-Tool PLUS.
This Report Answers
- How is headlight beam tester revenue split across product type, application, vehicle type and sales channel?
- Why are camera-based digital testers replacing optical screen units at inspection lanes?
- Which regulatory changes in Europe, the United States and Japan bring forward tester replacement?
- Where do repair workshops and OEM plants add demand beyond statutory inspection?
- How do the United States, Germany, Japan, the United Kingdom and Brazil differ in growth and buyer mix?
- Which suppliers hold approvals and service networks that decide inspection lane contracts?
What does the Headlight Beam Tester Market cover?
This study tracks revenue from headlamp aiming and testing equipment sold to inspection centers, repair shops, OEM plants and other professional users. It counts both camera-based digital testers and optical analog units, together with rail systems and leveling plates sold with them.
Values are reported in USD million at manufacturer selling price for the 2026 to 2036 period. Calibration contracts are counted only when sold with the equipment, since many lanes buy them as part of the tester package.
What is included in the scope?
Digital headlight beam testers using camera or photodiode sensors, with or without vehicle databases.
Analog testers with optical screens, Fresnel lenses and alignment lasers.
Rails, leveling plates and software licenses sold with testers for inspection and workshop use.
Testers installed at OEM end-of-line stations and at automotive stereo camera and driver-assist calibration bays where headlamp aim is checked.
What is excluded from the scope?
Headlamps, LED and halogen bulbs, lighting modules and other replacement lighting parts.
Wheel alignment machines, brake testers, diagnostic scanners and other workshop equipment without a headlamp test function.
Stand-alone calibration services, inspection fees and lighting design services.
Battery and charging test systems used in electric vehicle service, even when sold by the same suppliers.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
Segmentation
What is the report’s scope and coverage?
Headlight Beam Tester Market Taxonomy | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD million in 2026 to USD million by 2036 at CAGR |
| Market Definition | Equipment that measures and adjusts the aim, cut-off position and intensity of motor vehicle headlamps for inspection, repair and production checks. |
| Product Type | Digital Headlight Beam Tester; Analog Headlight Beam Tester |
| Application | Vehicle Inspection Centers; Automotive Repair Shops; OEMs; Others |
| Vehicle Type | Passenger Cars; Commercial Vehicles |
| Sales Channel | Offline; Online |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | United States; Germany; Japan; United Kingdom; Brazil |
| Companies Profiled | FORVIA HELLA; MAHA; Beissbarth; Snap-on; Capelec; Anzen Motor Car |
| Forecast Period | 2026 to 2036 |
| Approach | Lane and workshop installed base, replacement cycles tied to regulatory dates and tester price bands, checked against supplier product ranges. |
Source: Fact.MR analysis. Updated Nov 2, 2026
How is the market segmented?
-
By Product Type
- Digital Headlight Beam Tester
- Analog Headlight Beam Tester
-
By Application
- Vehicle Inspection Centers
- Automotive Repair Shops
- OEMs
- Others
-
By Vehicle Type
- Passenger Cars
- Commercial Vehicles
-
By Sales Channel
- Offline
- Online
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa
Frequently Asked Questions
How large is the headlight beam tester market in 2026?
What growth rate will the headlight beam tester market record?
Which product type leads?
Which application leads?
Which vehicle type leads?
Which sales channel leads?
Which country will grow quickest?
Who are the main companies?
What holds the market back?
Who worked on this report


Preview the report firsthand - request a free sample
Free SampleGet the brochure for pricing and purchase details
Download PDF