- Market Value (2025): USD 13.2 Bn
- Estimated Value (2026): USD 13.8 Bn
- Forecast Value (2036): USD 22.2 Bn
- CAGR (2026-2036): 4.8%
What is the Lawn Tools Market forecast to be worth by 2036?
USD 13.8 billion in 2026 to USD 22.2 billion by 2036, at a 4.8% CAGR.
- As per Fact.MR analysis, the lawn tools market reached USD 13.2 billion in 2025.
- Sales are projected to increase from USD 13.8 billion in 2026 to USD 22.2 billion by 2036.
- The market may grow at a 4.8% CAGR during 2026 to 2036 as homeowners replace aging mowers and grounds crews expand equipment fleets.
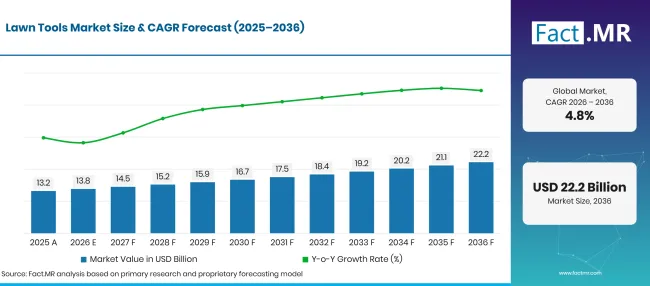
Factmr Lawn Tools Market Forecast Global 1 | Source: Fact.MR
| Year | Basis | Market Value (USD billion) |
|---|---|---|
| 2025 | Actual | 13.2 |
| 2026 | Estimate | 13.8 |
| 2036 | Forecast | 22.2 |
| CAGR 2026 to 2036 | Forecast period | 4.8% |
Source: Fact.MR analysis. Updated Oct 19, 2026
What are the defining numbers behind Lawn Tools Market growth?
USD 8.4 billion absolute opportunity between 2026 and 2036, with lawn mowers forming the main product category.
- Demand Drivers in the Market
- Homeowners use compact mowers and edge trimmers to keep grass at a manageable height without arranging outside maintenance for every visit.
- Landscape contractors need durable cutting equipment that starts reliably and can be serviced quickly during busy mowing seasons.
- Public grounds teams buy blowers and trimming tools for routine grass and debris management along walkways and maintained public areas.
- Equipment dealers support repeat sales when customers can obtain compatible batteries, blades and other spare parts without delay. Practical repair guidance also helps owners keep existing tools in use for longer.
- Key Segments Analyzed
- By Product Type: Lawn Mowers represent 32.4% share in 2026, reflecting the value of routine grass-cutting equipment.
- By Power Source: Gas-Powered tools hold 54.3% share in 2026, supported by extended work sessions and familiar refueling routines.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Lawn tool purchases follow a practical replacement cycle shaped by cutting performance and maintenance needs. A homeowner buying one mower weighs storage space and ease of operation, while a contractor managing several machines also considers service time and parts availability.”
- Strategic Implications
- Manufacturers should match cutting width and machine weight to the size of residential lawns so equipment feels manageable in everyday use.
- Dealers benefit from keeping blades and fuel-system or battery-related replacement parts available during the months when lawns need frequent care.
- Commercial grounds teams can compare service intervals, handling comfort and expected daily use before replacing several machines. Evaluating the whole fleet makes it easier to select equipment suited to regular routes.
- Online sellers can make remote purchases easier by showing product dimensions and clear battery compatibility information. Buyers need these details when they cannot inspect a mower or attachment before ordering.
Japan may grow at 5.4% CAGR through 2036, while Brazil follows at 5.1%. Germany carries a 4.6% outlook as buyers compare powered cutting tools for private and professional use. The United States is projected to post 4.2% growth, while the United Kingdom records 3.6% as established equipment owners balance replacement costs against the benefits of newer machines.
How does the Lawn Tools Market break down by segment?
Lawn Mowers 32.4%; Gas-Powered 54.3%; Residential and Commercial combined 100.0%; Online and Offline Retail combined 100.0% in 2026.
Which Product Type dominates?
Lawn Mowers hold 32.4% share in 2026.
| Product Type | Share (2026) |
|---|---|
| Lawn Mowers (Leading segment) | 32.4% |
| Other segments combined | 67.6%* |
| Total | 100.0% |
Source: Fact.MR analysis. Updated Oct 19, 2026
Mowers are purchased for routine cutting of maintained grass, so their replacement pattern is closely tied to property size and seasonal use. Trimmers and edgers tackle narrow areas near boundaries where mower decks are awkward to use. Leaf blowers are selected for collecting loose grass and leaves from paths, while chainsaws address tree cutting and heavier branch work. Other tools serve more specialized maintenance jobs.
What leads the Power Source segment?
Gas-Powered accounts for 54.3% share in 2026.
| Power Source | Share (2026) |
|---|---|
| Gas-Powered (Leading segment) | 54.3% |
| Other segments combined | 45.7%* |
| Total | 100.0% |
Source: Fact.MR analysis. Updated Oct 19, 2026
Gasoline engines remain familiar to customers who cover large outdoor areas or operate several machines during a working day. Electric tools offer quieter starting and are often easier to store in smaller homes. Corded models work when power outlets are nearby, while battery products need suitable charging plans and compatible packs. Manual equipment remains useful for light maintenance and smaller plots.
What is accelerating Lawn Tools Market adoption, and what is holding it back?
Regular grass and grounds maintenance supports lawn tool sales, while equipment prices and repair needs influence when buyers replace their machines.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Replacement of aging mowers | +1.0% | North America, Europe | Medium term (2–4 years) |
| Commercial lawn care | +0.8% | Global | Medium term (2–4 years) |
| Battery platform range | +0.7% | Europe, Japan | Long term (>= 4 years) |
| Residential property care | +0.5% | Global | Short term (<= 2 years) |
| Dealer service networks | +0.4% | Global | Medium term (2–4 years) |
Source: Fact.MR analysis. Updated Oct 19, 2026
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Interchangeable batteries | +0.8% | Global | Medium term (2–4 years) |
| Robotic mowing | +0.6% | Europe, Japan | Long term (>= 4 years) |
| Fleet servicing | +0.5% | North America | Medium term (2–4 years) |
| Online replacement parts | +0.4% | Global | Short term (<= 2 years) |
Source: Fact.MR analysis. Updated Oct 19, 2026
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Upfront equipment cost | -0.8% | Global | Short term (<= 2 years) |
| Repairs and spare parts | -0.6% | Global | Medium term (2–4 years) |
| Battery runtime limits | -0.5% | Global | Medium term (2–4 years) |
| Seasonal buying cycles | -0.4% | Temperate markets | Long term (>= 4 years) |
Source: Fact.MR analysis. Updated Oct 19, 2026
Which countries are scaling the Lawn Tools Market through 2036?
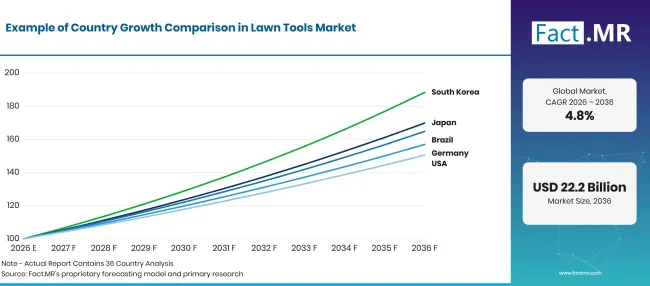
Factmr Lawn Tools Market Growth Index | Source: Fact.MR
| Country | CAGR (2026–2036) |
|---|---|
| Japan | 5.4% |
| Brazil | 5.1% |
| Germany | 4.6% |
| United States | 4.2% |
| United Kingdom | 3.6% |
Source: Fact.MR analysis. Updated Oct 19, 2026
Why is Japan expanding lawn tool adoption?
5.4% CAGR, with compact cutting systems and equipment replacement shaping sales.
Japanese lawn equipment purchases depend on outdoor space and the amount of work a household can manage. The Statistics Bureau of Japan reported 29.319 million occupied detached houses in 2023 in its 2025 handbook [2]. Detached properties create a potential customer base for compact mowers, although garden size varies.
How are Brazilian landscape services shaping purchases?
5.1% CAGR, influenced by maintained public greenery and residential garden care.
Brazilian urban grounds teams use trimmers around planted strips and paths where a larger mower is harder to handle. Households with maintained gardens compare equipment ownership against the cost of hiring a gardener. Repair workshops help landscape contractors continue using equipment during active grass-cutting periods. IBGE published 2022 Census neighbourhood infrastructure results in April 2025 [3], offering background on public-space conditions across Brazilian communities rather than a direct measure of lawn-tool sales.
What supports Germany’s lawn tools outlook?
4.6% CAGR, shaped by managed green areas and specialized garden equipment.
Germany has a developed network of gardening businesses serving maintained private and commercial spaces. Destatis reported 2,821 ornamental-plant businesses in 2025 [4], showing the scale of one group working with managed outdoor growing areas. Tree nurseries also require clear access paths and maintained vegetation. Destatis reported 15,350 hectares of nursery land in 2025 [5]. Household buyers compare mower noise and storage requirements, while specialist retailers assist customers choosing blades and compatible batteries.
How does the United States maintain lawn equipment sales?
4.2% CAGR, supported by professional groundskeeping and home maintenance.
In the United States, professional landscaping firms often use machines at several customer properties during the working week. The Bureau of Labor Statistics counted about 1.3 million grounds maintenance jobs in 2025 [6]. Crews depend on timely repairs and dependable cutting performance, while residential owners choose equipment according to lawn size.
How is the United Kingdom balancing lawn maintenance costs?
3.6% CAGR, tied to property upkeep and maintenance of accessible green areas.
UK households often choose compact mowers that fit smaller gardens and limited storage areas. The Office for National Statistics estimated 29.0 million households in the United Kingdom in 2025 [7], representing a broad residential base with different outdoor maintenance needs. In March 2026, Defra reported that 80% of households in England had access to green or blue space within a 15-minute walk [8]. Grounds contractors serve public gardens and planted areas, while specialist stores help household customers compare lightweight machines.
Who leads the Lawn Tools Market?
Husqvarna Group and Toro supply lawn equipment, alongside Deere & Company and STIHL across relevant outdoor tool categories.
Husqvarna Group sells mowers and cutting equipment for residential and professional grounds care. Deere & Company participates through John Deere lawn and turf machines, while Toro supplies turf maintenance products and residential mowers. These businesses serve different customer groups and equipment sizes, so buying decisions depend on the job and the service support available. Husqvarna’s February 2025 robotic mower introduction extends that range into routine automated cutting [1].
STIHL supplies chainsaws and handheld lawn maintenance tools. Honda remains associated with outdoor power equipment and engines in relevant markets. Bosch and Makita sell electric garden tools, while Ariens and Briggs & Stratton contribute mower equipment or engines.
Which companies are the key providers?
Key companies include Husqvarna Group; Deere & Company; Honda Motor Co., Ltd.; The Toro Company; Robert Bosch GmbH; STIHL Holding AG & Co. KG; Briggs & Stratton, LLC; Ariens Company; Makita Corporation.
- Husqvarna Group
- Deere & Company
- Honda Motor Co., Ltd.
- The Toro Company
- Robert Bosch GmbH
- STIHL Holding AG & Co. KG
- Briggs & Stratton, LLC
- Ariens Company
- Makita Corporation
Bibliography
- [1] Husqvarna Group. (2025, February 6). Husqvarna Group introduces its largest launch in history—13 new boundary wire-free robotic lawnmowers.
- [2] Statistics Bureau of Japan. (2025, September). Statistical Handbook of Japan 2025.
- https://www.stat.go.jp/english/data/handbook/pdf/2025half_2.pdf
- [3] Instituto Brasileiro de Geografia e Estatística. (2025, April 17). Censo Demográfico 2022: Características urbanísticas do entorno dos domicílios.
- [4] Statistisches Bundesamt (Destatis). (2025, November 24). Zierpflanzen 2025: Rund 10 % weniger Betriebe und 8 % weniger Flächen als im Jahr 2021.
- [5] Statistisches Bundesamt (Destatis). (2025, October 29). Baumschulen 2025: Rund 11 % weniger Betriebe und Flächen als im Jahr 2021.
- [6] U.S. Bureau of Labor Statistics. (2026, August 27). Grounds maintenance workers. Occupational Outlook Handbook.
- [7] Office for National Statistics. (2026, April 17). Families and households in the UK: 2025.
- [8] Department for Environment, Food & Rural Affairs. (2026, March 4). Access to green and blue space in England.
This Report Answers
- Power source analysis compares gas-powered equipment against electric and manual alternatives for lawn maintenance.
- The country comparison examines distinct conditions in Japan, Brazil, Germany, the United States and the United Kingdom.
- Competitive analysis considers the lawn-related product ranges of established manufacturers and equipment brands.
- Channel analysis explains how online sellers and physical dealers serve different purchasing and service needs.
What does the Lawn Tools Market cover?
The market covers mowers and other equipment used to maintain grass and nearby vegetation around homes and maintained outdoor spaces. It includes handheld trimmers and blowers alongside chainsaws that are sold into garden and grounds maintenance uses. Related equipment categories include gardening equipment, lawn mowers and outdoor power equipment.
What is included in the scope?
Included equipment is bought for residential garden care and professional grounds maintenance.
Gas-powered machines and electric models are both covered, along with manual tools used for the same functions. The channel comparison includes direct online sales and purchases from physical dealers or shops. Replacement machines count as market sales when a customer purchases a complete tool. The analysis considers product type and source of power as separate dimensions so individual sales are not counted twice.
What is excluded from the scope?
Agricultural tractors and field-scale farm machines fall outside the lawn tools definition when they are purchased for crop production.
Garden irrigation systems and unrelated construction equipment are also outside the equipment boundary. Maintenance contracts and routine labor charges are distinct from a new lawn tool sale. Parts alone are not counted as complete machines unless they are included in the priced equipment package.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
Segmentation
What is the report’s scope and coverage?
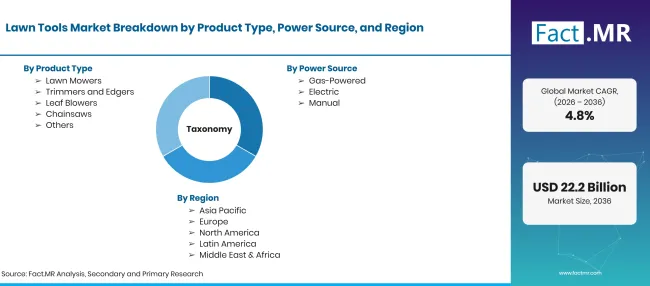
Factmr Lawn Tools Market Taxonomy | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion in 2026 to USD billion in 2036, at CAGR |
| Market Definition | Machines and handheld tools used to cut or maintain grass and nearby vegetation. |
| Product Type | Lawn Mowers; Trimmers and Edgers; Leaf Blowers; Chainsaws; Others |
| Power Source | Gas-Powered; Electric; Manual |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | Germany; Brazil; United States; United Kingdom; Japan |
| Companies Profiled | Husqvarna Group; Deere & Company; Honda Motor Co., Ltd.; The Toro Company; Robert Bosch GmbH; STIHL Holding AG & Co. KG; Briggs & Stratton, LLC; Ariens Company; Makita Corporation. |
| Forecast Period | 2026 to 2036 |
| Approach | Assessment of lawn maintenance applications, source technologies, distribution and official industry evidence |
Source: Fact.MR analysis. Updated Oct 19, 2026
How is the market segmented?
-
By Product Type
- Lawn Mowers
- Trimmers and Edgers
- Leaf Blowers
- Chainsaws
- Others
-
By Power Source
- Gas-Powered
- Electric
- Manual
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa
Frequently Asked Questions
How big is the lawn tools market in 2026?
What CAGR is projected from 2026 to 2036?
Which product type has the largest stated share?
What is the leading power source?
Who are the main companies in the lawn tools market?
Who worked on this report

Preview the report firsthand - request a free sample
Free SampleGet the brochure for pricing and purchase details
Download PDF