- Market Value (2025): USD 1.6 Bn
- Estimated Value (2026): USD 1.8 Bn
- Forecast Value (2036): USD 6.7 Bn
- CAGR (2026-2036): 13.8%
What is the Microemulsion Retinol Complexes Market forecast to be worth by 2036?
USD 1.8 billion in 2026 to USD 6.7 billion by 2036 at a 13.8% CAGR.
- The Microemulsion Retinol Complexes Market was valued at USD 1.6 billion in 2025.
- Demand is projected to increase from USD 1.8 billion in 2026 to USD 6.7 billion by 2036.
- The market is forecast to record 13.8% CAGR from 2026 to 2036 as beauty brands and dermocosmetic formulators use protected retinoid systems for stability and skin comfort.
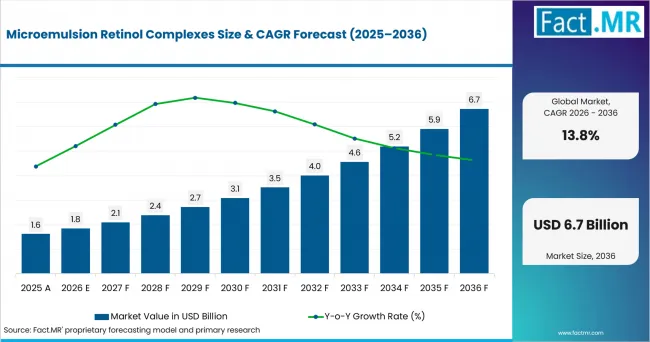
Microemulsion Retinol Complexes Value Analysis | Source: Fact.MR
What are the defining numbers behind Microemulsion Retinol Complexes Market growth?
An absolute opportunity of USD 4.9 billion is expected between 2026 and 2036.
- Demand Drivers in the Market
- Retinol suppliers need delivery systems that protect the active molecule during storage. Carrier design is expected to carry more weight as brands move retinol into daily-use facial care and lighter serum formats.
- Beauty brands are expected to favor carriers that make retinol easier to use in everyday facial care. Water-soluble and lipid-based capsules can help formulators balance active delivery with comfort-led positioning.
- Regulatory teams are expected to place greater value on ingredient traceability. FDA reported 16,398 unique active cosmetic product facility registrations under MoCRA as of June 30, 2026.
- China’s large digital retail base provides broad channel context for skincare sales. The National Bureau of Statistics reported that online retail sales of physical goods reached CNY 13,092.3 billion in 2025.
- Dermocosmetic formulators are expected to use controlled-release systems where retinol comfort shapes repeat use. Such systems help brands position anti-aging products for longer routines and sensitive-use occasions.
- Key Segments Analyzed
- By Carrier: Microemulsion is expected to hold 29.0% share in 2026 because small dispersed droplets fit serum and cream formats that need stable retinoid delivery.
- By Retinoid: Retinol is projected to account for 36.0% share in 2026 supported by its familiarity in anti-aging facial care and dermocosmetic product positioning.
- By Application: Serums are anticipated to capture 31.0% share in 2026 owing to their fit with concentrated active systems and routine-based facial care.
- By Benefit: Stability is estimated to represent 37.0% share in 2026 driven by the formulation challenge of protecting retinol during storage and use.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, "Retinol is becoming a delivery-system decision before it becomes a claims decision. Brands are asking whether the carrier can protect the molecule and make the finished formula easier to tolerate. Supplier selection is expected to favor partners that combine retinoid chemistry, carrier design, claim evidence and regional compliance support."
- Strategic Implications
- Formulators should document retinol stability under light and temperature stress before positioning a complex for premium facial skincare.
- Ingredient suppliers should offer prototype serums and creams so brands can compare release behavior and sensory feel in finished products.
- Regulatory teams should map retinol equivalent limits by region before selecting retinol, retinal, retinyl ester or bio-retinoid blend systems.
- Contract manufacturers should validate processing conditions for each carrier type so droplet behavior remains consistent during scale-up.
China is expected to record 14.3% CAGR through cosmetics retail scale and active skincare launches. France is projected to advance at 14.2% as dermocosmetic heritage and EU compliance needs shape formulation choices. The USA is forecast to post 13.8% through MoCRA documentation and active-led skincare demand. Germany is anticipated to reach 13.6% because drugstore beauty channels support product renovation. Japan is estimated to register 12.7% as skincare cosmetics remain central to domestic shipment value.
How does the Microemulsion Retinol Complexes Market break down by segment?
Microemulsion leads Carrier at 29.0%; Retinol leads Retinoid at 36.0%.
Which Carrier dominates?
Microemulsion holds 29.0% share in 2026.
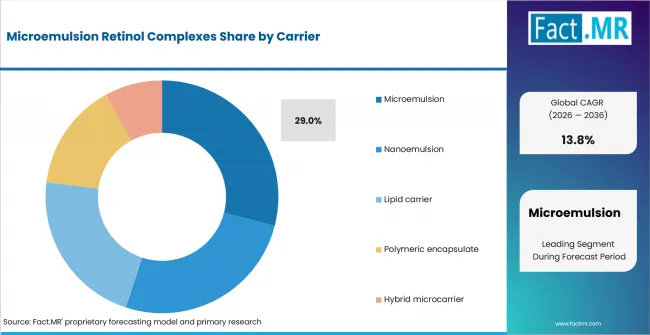
Microemulsion Retinol Complexes Analysis By Carrier | Source: Fact.MR
Microemulsion carriers lead because they disperse retinoid actives into small droplets that fit lightweight serum and cream systems. Formulators value this format when a finished product must look elegant, remain stable and deliver an active with a comfortable skin feel.
Carrier selection is closely tied to irritation control. BASF states that retinol is prone to light and air degradation and may cause irritation, which explains why protected systems are being used to widen practical formulation options.
What leads the Retinoid segment?
Retinol accounts for 36.0% share in 2026.
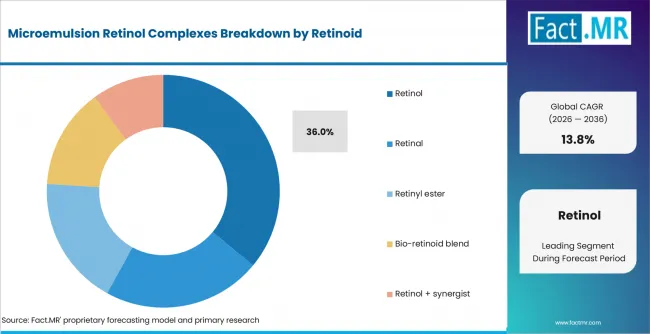
Microemulsion Retinol Complexes Analysis By Retinoid | Source: Fact.MR
Retinol remains the reference active for many anti-aging facial products because consumers recognize the ingredient and brands can position it across premium and dermocosmetic ranges. Encapsulation and microemulsion formats extend its use by addressing instability and comfort concerns.
Evonik lists ROVISOME Retinol Moist Pro MB as a stabilized vitamin A system with lower skin irritation potential. The company also positions the ROVISOME delivery system for deeper delivery of cosmetic actives and improved ingredient bioavailability.
How does Application shape demand?
Serums capture 31.0% share in 2026.
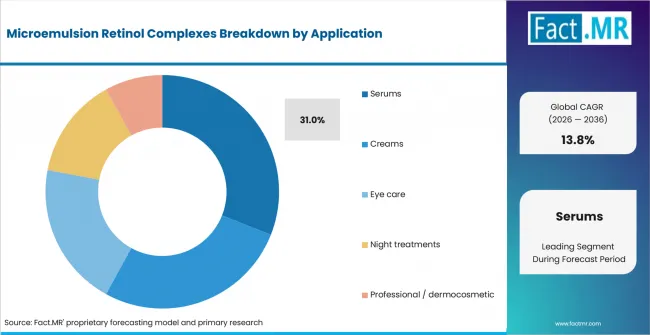
Microemulsion Retinol Complexes Analysis By Application | Source: Fact.MR
Serums lead application use because they are associated with concentrated active delivery and step-based skincare routines. Brands can introduce microemulsion retinol complexes in serum formats while keeping the rest of the routine familiar for consumers.
Germany provides a strong demand signal for facial-care products. IKW reported in December 2025 that sales of skin and facial care products in Germany increased by 11.1% in 2025, making the category one of the strongest-growing segments of the country’s beauty-care market.
What supports Benefit demand?
Stability represents 37.0% share in 2026.
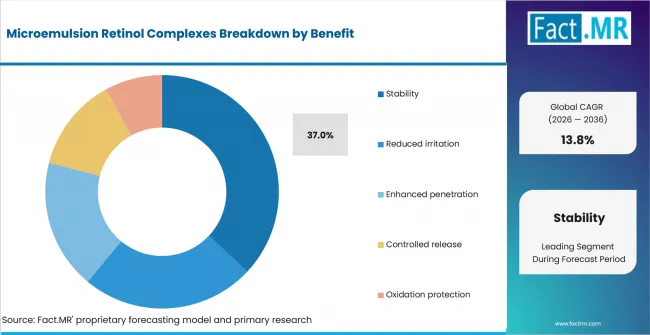
Microemulsion Retinol Complexes Analysis By Benefit | Source: Fact.MR
Stability leads the benefit segment because retinol loses performance when exposure to light and air is poorly controlled. Brands therefore evaluate whether the carrier protects the active through storage and use.
BASF reported in September 2025 that its solid lipid-particle retinol formulation retained 83% retinol after four months in a company-described real-life study, versus a market benchmark.
What is accelerating Microemulsion Retinol Complexes Market adoption, and what is holding it back?
Demand is expected to rise through active skincare routines and better retinol delivery. Growth is limited by compliance work, formulation cost and proof requirements.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Protected retinol stability in facial care | +1.8% | Global | Short term (<= 2 years) |
| MoCRA and ingredient listing discipline | +1.1% | USA | Medium term (2-4 years) |
| Serum-led active skincare routines | +1.0% | China, Europe, Japan | Medium term (2-4 years) |
| Dermocosmetic channel need for tolerability proof | +0.8% | Europe, Japan | Long term (>= 4 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Retinol systems for low-irritation routines | +1.2% | Global | Short term (<= 2 years) |
| Dermocosmetic and pharmacy-led facial care | +0.9% | Europe, Japan | Medium term (2-4 years) |
| Hybrid carrier formats for eye care and night care | +0.7% | North America, East Asia | Long term (>= 4 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| EU retinol equivalent limits | -0.8% | Europe | Short term (<= 2 years) |
| Higher formulation and testing cost | -0.6% | Global | Medium term (2-4 years) |
| Scale-up sensitivity of carrier systems | -0.4% | Global | Long term (>= 4 years) |
Which countries are scaling the Microemulsion Retinol Complexes Market through 2036?
- China remains 0.1 percentage point above France through cosmetics retail scale and online active-skincare discovery.
- France remains 0.4 percentage point above the USA through dermocosmetic heritage and EU formulation discipline.
- The USA remains 0.2 percentage point above Germany as MoCRA product listing increases documentation discipline.
- Germany remains 0.9 percentage point above Japan through drugstore beauty channels and facial-care spending.
- Japan closes the displayed range through skincare shipment weight and careful retinol positioning.
Comparable CAGRs can create different entry conditions due to regulation, channel structure and consumer tolerance expectations. Full report coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Middle East & Africa.
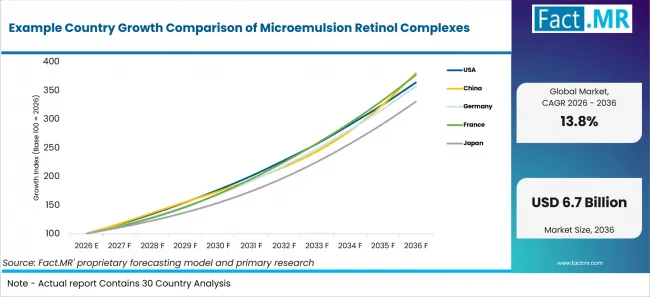
Example Country Growth Comparison Of Microemulsion Retinol Complexes | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| China | 14.3% |
| France | 14.2% |
| USA | 13.8% |
| Germany | 13.6% |
| Japan | 12.7% |
What supports China adoption?
14.3% CAGR, supported by cosmetics retail scale and serum-led active skincare.
China gives active skincare brands a large retail base for premium facial care. NBS reported in January 2026 that cosmetics retail sales among enterprises above designated size reached 465.3 billion yuan in 2025. Microemulsion retinol complexes are expected to fit serum launches where lightweight texture and visible anti-aging positioning shape consumer choice.
What supports France adoption?
14.2% CAGR, shaped by dermocosmetic strength and EU retinoid compliance.
France combines premium beauty manufacturing with pharmacy-led skincare credibility. FEBEA reported in 2025 that the French cosmetics sector generated EUR 35.6 billion in turnover during 2024. Retinol delivery systems are expected to fit dermocosmetic ranges where tolerance evidence and EU dossier readiness shape launch planning.
What supports USA adoption?
13.8% CAGR, supported by MoCRA documentation and active-led skincare demand.
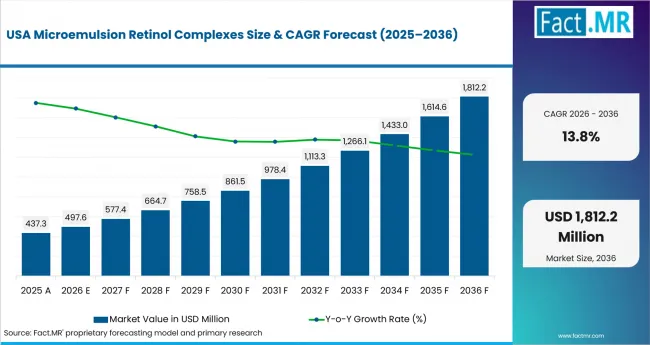
Microemulsion Retinol Complexes Country Value Analysis | Source: Fact.MR
The USA is expected to favor retinol complexes backed by clear ingredient records and repeatable batch data. FDA reported 1,298,361 unique active cosmetic product listings under MoCRA as of June 30, 2026. That listing environment supports ingredient suppliers that can provide traceable retinoid systems for active skincare brands.
What supports Germany adoption?
13.6% CAGR, led by drugstore channel depth and facial-care spending.
Germany offers a practical route for retinol systems through drugstores and facial-care routines. IKW reported in December 2025 that cosmetics were most frequently purchased in drugstores with 53% market share. Microemulsion retinol complexes are expected to suit brands that need stable actives and clear shopper education at shelf level.
How does Japan perform?
12.7% CAGR, backed by skincare shipment weight and careful active positioning.
Japan remains a skincare-led beauty market with high expectations for texture and mild use experience. JCIA reported in October 2025, using METI production statistics, that Japan’s 2024 cosmetic shipment value rose 5.5% to JPY 1,374.5 billion. Protected retinol systems are expected to gain use in night treatments and eye care where comfort shapes repeat use.
Who leads the Microemulsion Retinol Complexes Market?
BASF is active through VitaGuard® A and Cylasphere™ Retinol systems. Its personal-care portfolio uses retinol encapsulation to improve stability and bioavailability while reducing irritation potential in cosmetic formulations.
Evonik is active through ROVISOME® Retinol Moist Pro MB and its cosmetic delivery-system technology. Evonik states that the ROVISOME delivery system can deliver cosmetic actives to deeper skin layers and increase their bioavailability, while ROVISOME Retinol Moist Pro MB provides enhanced retinol stabilization and lower skin-irritation potential.
Croda participates through ReVitAlide™ and broader beauty encapsulation capabilities. ReVitAlide is described as a water-soluble capsule carrying 3% active retinol with enhanced stability and improved bioavailability.
Givaudan Active Beauty participates through Spherulite™ R-10, a microencapsulated stabilized-retinol system designed to protect retinol, enhance its stability and provide slow release in anti-ageing skincare. Clariant participates through VitiSpheres™ R8, a retinol carrier system that provides controlled prolonged release and remains stable during stirring and storage while protecting retinol. Tagra Biotechnologies participates through CelluCap™ RL, an encapsulated pure-retinol system whose microencapsulation technology protects retinol from environmental degradation and helps preserve its stability and efficacy during production and shelf life.
Which companies are the key providers?
Directly evidenced providers include BASF, Evonik, Croda, Givaudan Active Beauty, Clariant and Tagra Biotechnologies.
- BASF
- Evonik
- Croda
- Givaudan Active Beauty
- Clariant
- Tagra Biotechnologies
Bibliography
- BASF. (2025, January 23). BASF’s Personal Care business launches VitaGuard® A, an innovative encapsulation technology for retinol.
- BASF. (2025, September 9). BASF to present the latest advancements in cosmetic science at IFSCC Congress.
- National Bureau of Statistics of China. (2026, January 20). Total retail sales of consumer goods in December 2025.
- Industrieverband Körperpflege- und Waschmittel e. V. (2025, December 3). Renewed growth for the beauty and home care industry.
- Fédération des Entreprises de la Beauté. (2025, June). Beauty Industry Package: FEBEA’s 5 priorities for a competitive and sustainable cosmetics industry.
- European Commission. (2024, April 3). Commission Regulation (EU) 2024/996 of 3 April 2024 amending Regulation (EC) No 1223/2009 of the European Parliament and of the Council as regards the use of Vitamin A, Alpha-Arbutin and Arbutin and certain substances with potential endocrine disrupting properties in cosmetic products. Official Journal of the European Union.
- Clariant. (2026, June 17). VitiSpheres™ R8.
This Report Answers
- The report explains where microemulsion retinol complexes are used across carrier and retinoid type. It also covers application and benefit segmentation.
- Segment analysis identifies the leading subsegments and the formulation reasons brands prioritize them.
- Country analysis examines the listed markets and the retail, regulatory or skincare mechanisms supporting retinol delivery adoption.
- Competitive analysis reviews current providers across encapsulated retinol, delivery systems, personal care actives and dermocosmetic formulation support.
- Application analysis assesses how stability, tolerability and controlled release influence ingredient selection in serums, creams, eye care and night treatments.
What does the Microemulsion Retinol Complexes Market cover?
The Microemulsion Retinol Complexes Market centers on microemulsion-based retinoid delivery systems used in cosmetic and dermocosmetic skincare. Nanoemulsion, lipid, polymeric and hybrid retinoid-delivery systems are treated as adjacent or competing carrier categories where they are included for comparative segmentation.
The assessment covers carrier design, retinoid selection, application format and benefit claims. It aligns with adjacent demand in personal care active ingredients and skin bioactive ingredients where formulators evaluate stability and skin response.
What is included in the scope?
The core scope includes cosmetic ingredient systems that deliver retinol, retinal, retinyl ester or bio-retinoid blends through microemulsion-based carrier formats. Other protected carrier systems are considered as adjacent technologies for comparative analysis rather than as synonymous with microemulsions.
It includes serum, cream, eye care and night-treatment applications where carrier technology supports stability or controlled release. The assessment also covers adjacent product formats such as stick-format face serums where active delivery influences sensory design.
What is excluded from the scope?
The scope excludes finished retail skincare brands when sold as consumer products alone. Adjacent skin care products are considered only when they use carrier-based retinoid ingredients within the formulation boundary.
General emulsifiers, fragrances and basic moisturizer ingredients are excluded unless they are part of a retinoid delivery system. Adjacent areas such as antioxidant-rich skincare, premium beauty and personal care products and e-commerce personal care products are treated as context for channel demand.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with ingredient manufacturers, technology developers, distributors, formulators, contract manufacturers and technical experts. These conversations examine purchasing priorities, product adoption, testing requirements, regulatory needs, competitive positioning and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, technical studies, industry associations, standards, public policy and other authoritative sources. Principal public sources cited in the report are documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals and shifts in commercial adoption.
What is the report’s scope and coverage?
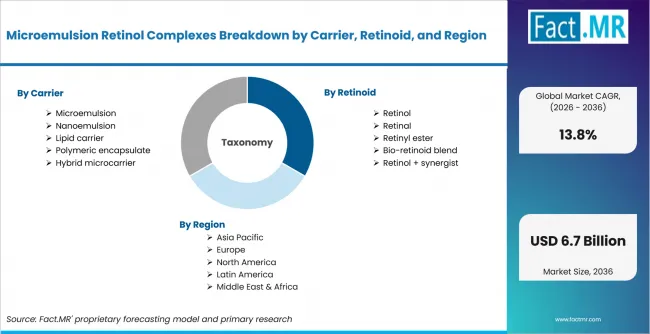
Microemulsion Retinol Complexes Breakdown By Carrier, Retinoid, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Market assessment centered on microemulsion-based retinoid delivery systems used in cosmetic and dermocosmetic formulations to support retinoid solubilization, stability and controlled topical delivery. Nanoemulsion, lipid, polymeric and hybrid systems are included as adjacent or competing carrier categories where specified in the comparative segmentation. |
| Carrier | Microemulsion; Nanoemulsion; Lipid carrier; Polymeric encapsulate; Hybrid microcarrier |
| Retinoid | Retinol; Retinal; Retinyl ester; Bio-retinoid blend; Retinol + synergist |
| Application | Serums; Creams; Eye care; Night treatments; Professional / dermocosmetic |
| Benefit | Stability; Reduced irritation; Enhanced penetration; Controlled release; Oxidation protection |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | China; France; USA; Germany; Japan |
| Key Companies Profiled | BASF; Evonik; Croda; Givaudan Active Beauty; Clariant; Tagra Biotechnologies |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using cosmetic ingredient demand, retinoid delivery technology, application mix, country adoption, company portfolios and verified public evidence. |
How is the market segmented?
-
By Carrier
- Microemulsion
- Nanoemulsion
- Lipid carrier
- Polymeric encapsulate
- Hybrid microcarrier
-
By Retinoid
- Retinol
- Retinal
- Retinyl ester
- Bio-retinoid blend
- Retinol + synergist
-
By Application
- Serums
- Creams
- Eye care
- Night treatments
- Professional / dermocosmetic
-
By Benefit
- Stability
- Reduced irritation
- Enhanced penetration
- Controlled release
- Oxidation protection
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa

