- Market Value (2025): USD 2.1 Bn
- Estimated Value (2026): USD 2.3 Bn
- Forecast Value (2036): USD 5.5 Bn
- CAGR (2026-2036): 9.1%
What is the Clean-Label Gummy Systems Market forecast to be worth by 2036?
USD 2.3 billion in 2026 to USD 5.5 billion by 2036, at a 9.1% CAGR.
- The Clean-Label Gummy Systems Market was valued at USD 2.1 billion in 2025.
- Demand is projected to increase from USD 2.3 billion in 2026 to USD 5.5 billion by 2036.
- The market is forecast to record a 9.1% CAGR from 2026 to 2036 as nutraceutical and functional-gummy formulators refine texture systems. Confectionery formulators are expected to expand sweetening-system work across reduced-sugar formats.
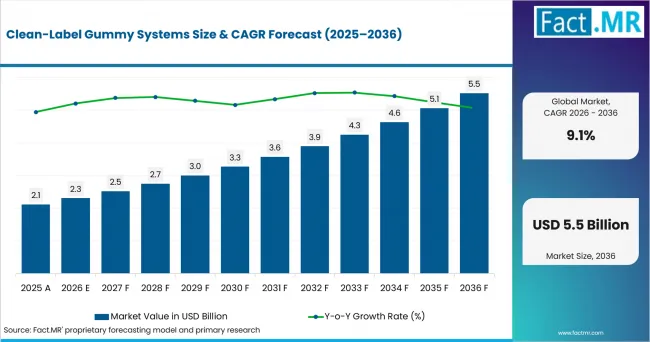
Clean Label Gummy Systems Value Analysis | Source: Fact.MR
What are the defining numbers behind Clean-Label Gummy Systems Market growth?
USD 3.2 billion absolute opportunity by 2036, led by nutraceutical gummies, soft-chew textures, and pectin-based systems.
- Demand Drivers in the Market
- Nutraceutical brands need reliable texture systems as supplement use supports chewable formats. The National Center for Health Statistics reported in May 2026 that 60.2% of U.S. adults aged 20 or older used any dietary supplement in the past 30 days during the August 2021–August 2023 survey period.
- Confectionery and functional-food formulators need stable gels across a broad spending base. USDA Economic Research Service reported on June 11, 2026 that total U.S. food spending reached USD 2.51 trillion in 2025 in inflation-adjusted 2025 dollars.
- Color reformulation increases the value of formulation systems that preserve appearance and flavor. The U.S. Food and Drug Administration announced on April 22, 2025 that it would work with industry to eliminate six remaining petroleum-based synthetic dyes from the food supply.
- Sweetener and texture suppliers need scalable low-sugar systems for high-volume food markets. China’s National Bureau of Statistics reported in January 2026 that 2025 per capita spending on food and tobacco with liquor reached 8,631 yuan.
- Key Segments Analyzed
- By Gelling Base: Pectin is expected to account for 31.0% share in 2026 because it supports plant-based positioning and is widely used for gummy gel formation.
- By Sweetener System: Polyols are projected to hold 29.0% share in 2026 owing to their role in sugar-reduced recipes that still require bulk and controlled sweetness.
- By Application: Nutraceutical gummies are anticipated to capture 36.0% share in 2026 as supplement brands use chewable formats for vitamins and minerals. Wellness ingredients add another formulation requirement.
- By Texture Target: Soft chew is estimated to represent 34.0% share in 2026 since a yielding bite helps formulators serve broad age groups and functional-gummy applications.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR states, “The commercial challenge extends beyond replacing one ingredient with another. A clean-label gummy system has to align sweetness with gel strength while maintaining active stability and release behavior. Supplier portfolios that combine hydrocolloid expertise with sweetening support are expected to gain more formulation work as brands shorten development cycles.”
- Strategic Implications
- Formulators should compare pectin cost and performance during scale-up. Cargill’s March 2025 AAHAR program introduced a pectin replacer designed for gummies and jellies.
- Nutraceutical developers should evaluate plant-based gelling systems alongside active loading. IFF announced in April 2025 that GRINDSTED Pectin Premium would be showcased for plant-based gummies at Vitafoods Europe.
- Contract manufacturers should benchmark starch-free processing against conventional routes. GELITA’s March 2025 CONFIXX material described fast-setting gelatin for low-temperature fortified-gummy production.
Japan is projected to record 9.5% CAGR through 2036, supported by functional-food demand and established health-oriented food categories. China is anticipated to advance at 9.2% as food spending and retail activity expand the addressable consumer base. France is estimated to post 9.1% owing to supplement interest and continued confectionery consumption. The USA is forecast to reach 8.7% as dietary-supplement use supports nutraceutical-gummy formats. Germany is expected to register 8.5% as sugar-reduction goals and established confectionery production shape reformulation work.
How does the Clean-Label Gummy Systems Market break down by segment?
Nutraceutical gummies lead Application at 36.0%, soft chew leads Texture Target at 34.0%.
Which Gelling Base dominates?
Pectin is expected to hold 31.0% share in 2026.
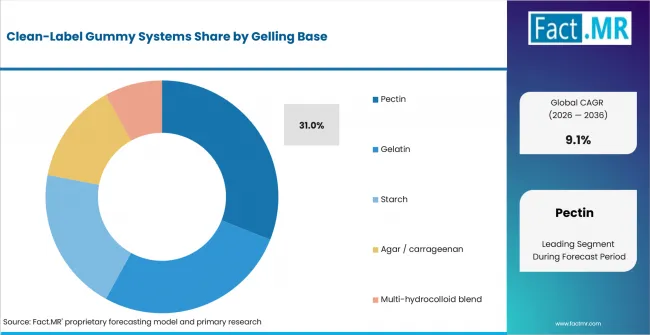
Clean Label Gummy Systems Analysis By Gelling Base | Source: Fact.MR
Pectin is expected to lead the gelling-base share because it supports plant-based positioning and controlled gel formation. Gelatin remains relevant for elastic chew while starch and multi-hydrocolloid systems address set speed and process economics. Citrus pectin and food stabilizer categories provide adjacent context for gummy texture design.
What leads the Sweetener System segment?
Polyols are projected to account for 29.0% share in 2026.
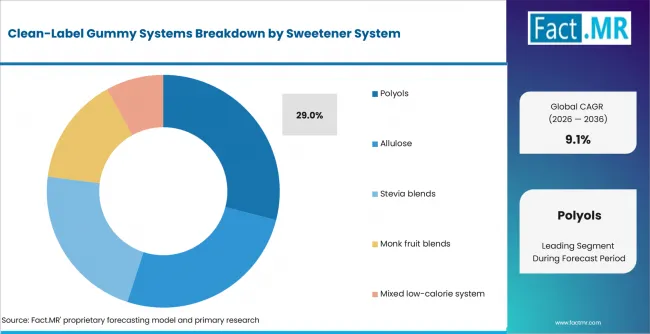
Clean Label Gummy Systems Analysis By Sweetener System | Source: Fact.MR
Polyols are projected to lead because they provide bulk and sweetness in reduced-sugar gummies. Allulose and stevia blends offer other sweetness routes. Monk fruit blends and mixed systems broaden formulation choices. Work therefore centers on sweetness quality and solids replacement while controlling aftertaste and gel compatibility.
How does Application shape demand?
Nutraceutical gummies are anticipated to capture 36.0% share in 2026.
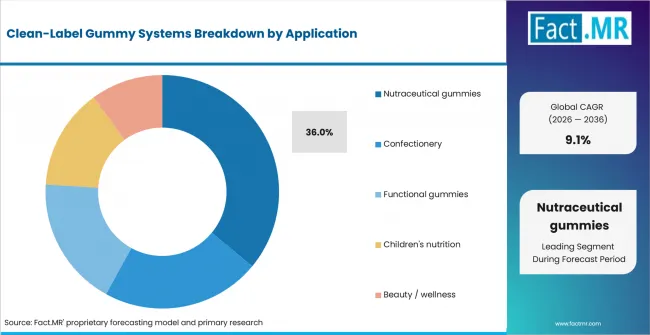
Clean Label Gummy Systems Analysis By Application | Source: Fact.MR
Nutraceutical gummies are anticipated to lead Application because chewable formats carry vitamins and wellness ingredients. Children’s nutrition and beauty or wellness products add tighter dose and stability requirements. France’s DGCCRF reported on November 3, 2025, that its 2023 dietary-supplement investigation covered 270 establishments, with anomalies identified at around one-third of those inspected. The findings highlight the importance of accurate formulation, labeling and claims compliance.
What supports Soft Chew within Texture Target?
Soft chew is estimated to represent 34.0% share in 2026.
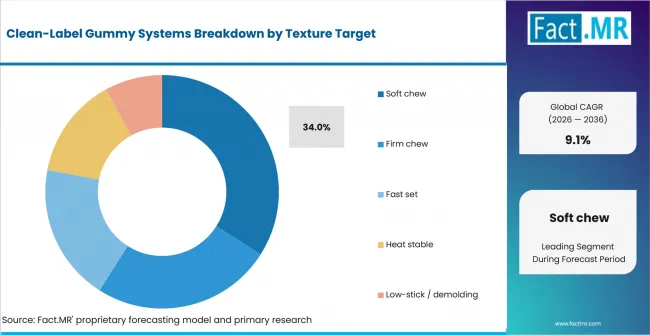
Clean Label Gummy Systems Analysis By Texture Target | Source: Fact.MR
Soft chew is estimated to lead the texture share because it works across nutraceutical and mainstream gummies. Firm chew serves classic confectionery profiles while fast-set and low-stick systems support higher throughput. Texture selection therefore depends on gel chemistry and active sensitivity while accounting for deposition conditions and release behavior.
What is accelerating Clean-Label Gummy Systems Market adoption, and what is holding it back?
Supplement-format demand and reformulation needs drive adoption, process sensitivity and regulatory compliance restrain it.
The source provides the driver, opportunity, restraint, geographic relevance, and timeline, but not numeric CAGR-impact values. The percentages below are analytical estimates to match your required table format.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Nutraceutical gummy format expansion | +1.8% | Global | Short term (<= 2 years) |
| Sugar-reduction reformulation | +1.4% | North America, Europe, East Asia | Medium term (2-4 years) |
| Plant-based gelling demand | +1.1% | North America, Europe | Medium term (2-4 years) |
| Faster setting and demolding needs | +0.9% | Global | Short term (<= 2 years) |
| Supplier portfolio integration | +0.7% | Global | Long term (>= 4 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Reduced-sugar clean-label gummies | +1.3% | North America, Europe | Medium term (2-4 years) |
| Starch-free fortified gummy processing | +1.0% | Global | Short term (<= 2 years) |
| Beauty and wellness gummies | +0.8% | North America, Europe, East Asia | Medium term (2-4 years) |
| Custom multi-hydrocolloid systems | +0.6% | Global | Long term (>= 4 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Texture shifts during sugar reduction | -0.7% | Global | Short term (<= 2 years) |
| Active-ingredient heat sensitivity | -0.5% | Global | Medium term (2-4 years) |
| Color and additive reformulation rules | -0.4% | North America, Europe | Medium term (2-4 years) |
| Ingredient and process cost trade-offs | -0.3% | Global | Long term (>= 4 years) |
Which countries are scaling the Clean-Label Gummy Systems Market through 2036?
- The country comparison spans 1.0 percentage point across the 2026 to 2036 forecast period.
- Japan remains 0.3 percentage point above China as health-oriented gummy formats support formulation work.
- China remains 0.1 percentage point above France as food spending and large-scale manufacturing support new gummy concepts.
- France remains 0.4 percentage point above the USA as food consumption and supplement activity sustain texture-system demand.
- The USA remains 0.2 percentage point above Germany as dietary-supplement use supports nutraceutical gummy development.
- Germany closes the displayed range as confectionery production and sugar-reduction work sustain reformulation activity.
Comparable CAGRs create different entry conditions because each country combines its own mix of supplement use and confectionery activity. Regulation and formulation capability shape the route to market. Full report coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Middle East & Africa.
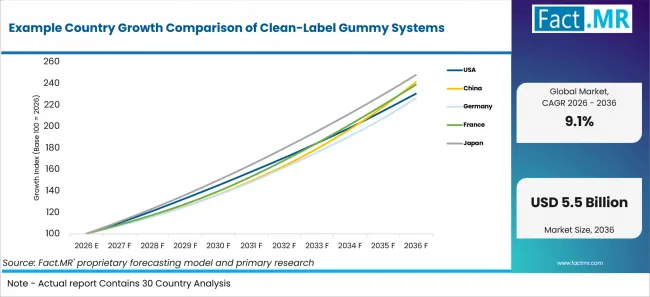
Example Country Growth Comparison Of Clean Label Gummy Systems | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| Japan | 9.5% |
| China | 9.2% |
| France | 9.1% |
| USA | 8.7% |
| Germany | 8.5% |
What is powering Japan’s clean-label gummy systems outlook?
9.5% CAGR through 2036, supported by functional-food approval pathways and texture-system development.
Japan’s Consumer Affairs Agency reported on August 13, 2025 that, as of that date, 1,033 foods had received Foods for Specified Health Uses permits or approvals. Japan is projected to record 9.5% CAGR through 2036 as health-oriented formulations maintain demand for pectin and gelatin with blended texture systems. Suppliers that pair gel control with active compatibility are positioned to serve shorter development cycles.
How is China scaling clean-label gummy systems demand?
9.2% CAGR through 2036, driven by food-market scale and formulation control.
China’s State Administration for Market Regulation reported on April 3, 2026 that 6,661,030 batches of food-safety supervision sampling were completed in 2025. China is anticipated to advance at 9.2% CAGR from 2026 to 2036 as large-scale food manufacturing supports pectin and polyol systems. Mixed sweetener systems are expected to benefit from repeatable ingredient documentation and set behavior.
What supports France’s clean-label gummy systems outlook?
9.1% CAGR through 2036, led by food spending and nutraceutical formulation activity.
INSEE reported in May 2026 that French household consumption of food and non-alcoholic beverages reached EUR 192.8 billion in 2025. France is estimated to post 9.1% CAGR by 2036 as confectionery and supplement formats sustain work on pectin and gelatin. Reduced-sugar systems are expected to focus on texture stability and active loading.
What underpins the USA outlook?
8.7% CAGR through 2036, backed by dietary-supplement use and nutraceutical gummy demand.
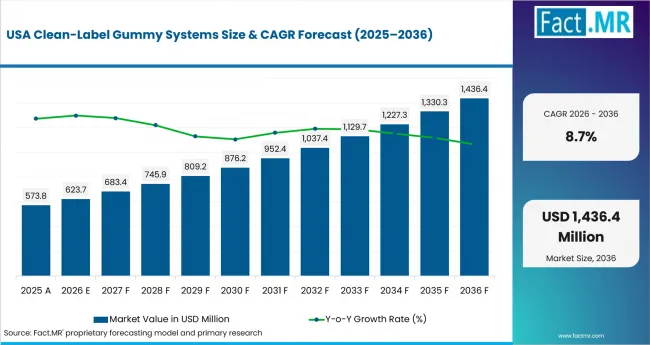
Clean Label Gummy Systems Country Value Analysis | Source: Fact.MR
The U.S. Bureau of Labor Statistics reported in its December 2025 Employment and Earnings table that seasonally adjusted employment in sugar and confectionery product manufacturing was 75.8 thousand workers in November 2025. The USA is forecast to reach 8.7% CAGR through 2036 as confectionery and nutraceutical brands broaden chewable formats. Suppliers that document deposition and set time with active compatibility are expected to gain formulation work.
How is Germany developing clean-label gummy systems demand?
8.5% CAGR through 2036, shaped by confectionery production and reformulation activity.
Destatis reported in December 2025 that Germany produced nearly 1.07 million tonnes of chocolate products in 2024. Germany is expected to register 8.5% CAGR from 2026 to 2036 as confectionery capability supports gummy texture and sweetener reformulation. Pilot-scale support is expected to help manufacturers compare chew and setting before commercial runs.
Who leads the Clean-Label Gummy Systems Market?
Tate & Lyle including CP Kelco and Cargill provide broad texture and sweetening coverage. GELITA and Ingredion add specialized formulation capabilities while IFF supports pectin-based systems.
Tate & Lyle combines sweetening and mouthfeel capabilities with CP Kelco’s pectin and specialty-gum portfolio. Its June 2025 Annual Report described the combined business following the November 2024 acquisition of CP Kelco and highlighted its strengthened positions across sweetening, mouthfeel and fortification.
Cargill contributes pectin, pectin-replacement solutions, starches and functional food systems for confectionery applications, including gummies and jellies.
Competitive differentiation includes sensory performance, sugar-reduction capability, compatibility with functional ingredients and application-development support. Technical assistance during formulation and scale-up also supports supplier evaluation for confectionery and fortified-gummy applications.
Which companies are the key providers?
Tate & Lyle including CP Kelco and Cargill are profiled alongside Ingredion and IFF. GELITA completes the company set.
- CP Kelco, part of Tate & Lyle
- Cargill
- Ingredion
- IFF
- GELITA
Bibliography
- Stierman, B., Couch, C. A., Gahche, J. J., & Mishra, S. (2026, May). Dietary supplement use: United States, August 2021–August 2023 (NCHS Data Brief No. 561). National Center for Health Statistics.
- Zeballos, E., & Sinclair, W. (2026, June 11). Total U.S. food spending reached $2.51 trillion in 2025. U.S. Department of Agriculture, Economic Research Service.
- U.S. Food and Drug Administration. (2025, April 22). HHS, FDA to phase out petroleum-based synthetic dyes in nation’s food supply.
- National Bureau of Statistics of China. (2026, January 20). Households’ income and consumption expenditure in 2025.
- Beretti, P.-A., & Pereira, É. (2026, June 16). La consommation des ménages en 2025 : La consommation des ménages ralentit en dépit d’une forte décélération des prix. Insee Première, (2110).
- Statistisches Bundesamt (Destatis). (2025, December 2). 12,8 Kilo Schokolade pro Kopf wurden 2024 produziert [12.8 kilograms of chocolate per capita were produced in 2024].
- Direction générale de la concurrence, de la consommation et de la répression des fraudes. (2025, November 3). Compléments alimentaires : des anomalies encore trop nombreuses.
- Cargill. (2025, March 4). Cargill showcases full range of innovative food solutions at AAHAR 2025.
- IFF. (2025, April 22). IFF Pharma Solutions to showcase plant-based dietary supplement ingredients and technical expertise at Vitafoods™ Europe 2025.
- GELITA. (2025, March 28). CONFIXX®: Revolutionize your fortified gummy production [E-book].
- Ingredion Incorporated. (2025, April 29). PureCircle™ by Ingredion first to achieve Farm Sustainability Assessment Silver performance level for 100% of stevia supply.
This Report Addresses
- The report explains how gelling and sweetener choices shape gummy processing.
- Segment analysis identifies pectin and polyols as the share leaders for 2026. Nutraceutical gummies and soft chew lead their respective dimensions.
- Country analysis covers Japan and China alongside France. The USA and Germany complete the five-country comparison using official evidence.
- Competitive analysis reviews CP Kelco within Tate & Lyle alongside Cargill and Ingredion. IFF and GELITA complete the profiled supplier set.
- Technology assessment compares pectin with gelatin and starch. Agar or carrageenan and multi-hydrocolloid systems complete the texture-system coverage.
- Application analysis covers nutraceutical and confectionery gummies alongside functional formats. Children’s nutrition and beauty or wellness gummies complete the application set.
- Texture analysis covers soft chew and firm chew alongside fast-set systems. Heat-stable and low-stick or demolding requirements complete the texture assessment.
- The forecast combines official statistics with company portfolio checks and formulation evidence across the profiled countries.
What does the Clean-Label Gummy Systems Market cover?
Pectin, gelatin, starch, agar or carrageenan, and blended systems used to control gummy texture and sweetness.
The market covers gelling and sweetener systems used in nutraceutical and functional gummies. Confectionery and children’s nutrition formats are included alongside beauty or wellness gummies.
The market boundary centers on formulation systems while finished gummy products fall outside the defined market. Sweeteners or hydrocolloids enter the scope when they serve a direct gummy formulation function.
What is included in the scope?
Clean-label gummy systems used in nutraceutical and confectionery products alongside functional formats. Children’s nutrition and beauty or wellness products complete the application coverage.
The scope includes the listed gelling bases and sweetener systems together with applications and texture targets. Ingredient context is connected to citrus pectin and food stabilizers where gel strength and texture control overlap gummy formulation. gelatin systems and gelatin substitutes provide adjacent context for animal-derived and plant-based routes.
Sweetener and application context includes next-generation stevia and dietary supplements alongside nutraceutical confectionery. Finished-format context is assessed through gummy vitamins and multivitamin gummies alongside adult vitamin gummies to keep ingredient-system analysis tied to real applications.
What is excluded from the scope?
Finished gummy brands and unrelated confectionery ingredients are outside the scope.
The scope boundary places finished gummy revenue and packaging outside the formulation-system market. Depositing or coating equipment and unrelated ingredients belong to adjacent categories. Non-gummy pharmaceutical dosage forms fall outside the defined scope.
How was the analysis built?
120+ sources, 35+ company portfolios, 25+ countries, and 20+ industry interviews.
- Primary Research: Inputs cover formulators and nutraceutical brands alongside ingredient suppliers. Contract manufacturers and application specialists contribute views on texture and sweetness while addressing active loading and process limits.
- Desk Research: Reviews government statistics and regulators alongside supplier portfolios. Company announcements and standards are assessed together with public policy.
- Market-Sizing and Forecasting: The model combines application demand with gelling and sweetener use. Country inputs and supplier activity are assessed alongside formulation constraints while retaining the market values unchanged.
- Data Validation and Update Cycle: Official statistics are checked against supplier activity and formulation reasoning. Company status and developments are rechecked alongside country evidence before updates.
What is the report’s scope and coverage?
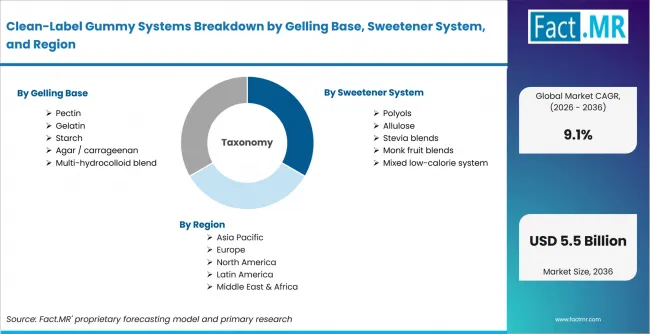
Clean Label Gummy Systems Breakdown By Gelling Base, Sweetener System, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Ingredient and formulation systems used to build clean-label gummy texture and sweetness across nutraceutical, functional, confectionery, children’s nutrition, and beauty or wellness applications. |
| Gelling Base | Pectin, Gelatin, Starch, Agar / carrageenan, Multi-hydrocolloid blend |
| Sweetener System | Polyols, Allulose, Stevia blends, Monk fruit blends, Mixed low-calorie system |
| Application | Nutraceutical gummies, Confectionery, Functional gummies, Children’s nutrition, Beauty / wellness |
| Texture Target | Soft chew, Firm chew, Fast set, Heat stable, Low-stick / demolding |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Middle East & Africa |
| Countries Covered | USA, China, Germany, France, Japan |
| Key Companies Profiled | CP Kelco, part of Tate & Lyle, Cargill, Ingredion, IFF, GELITA |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up review using gummy application demand, ingredient functionality, country evidence, supplier portfolios, and formulation constraints. |
How is the market segmented?
-
By Gelling Base
- Pectin
- Gelatin
- Starch
- Agar / carrageenan
- Multi-hydrocolloid blend
-
By Sweetener System
- Polyols
- Allulose
- Stevia blends
- Monk fruit blends
- Mixed low-calorie system
-
By Application
- Nutraceutical gummies
- Confectionery
- Functional gummies
- Children’s nutrition
- Beauty / wellness
-
By Texture Target
- Soft chew
- Firm chew
- Fast set
- Heat stable
- Low-stick / demolding
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa