- Market Value (2025): USD 2.6 Bn
- Estimated Value (2026): USD 2.7 Bn
- Forecast Value (2036): USD 4.9 Bn
- CAGR (2026-2036): 6.1%
What is the Matte MDO Polyethylene Films Market forecast to be worth by 2036?
USD 2.7 billion in 2026 to USD 4.9 billion by 2036, at a 6.1% CAGR.
- The market is valued at USD 2.6 billion in 2025.
- Demand is projected to increase from USD 2.7 billion in 2026 to USD 4.9 billion by 2036.
- The market is forecast to record a 6.1% CAGR from 2026 to 2036 as converters qualify matte MDO-PE for recyclable flexible packaging while preserving print quality and pack-line performance.
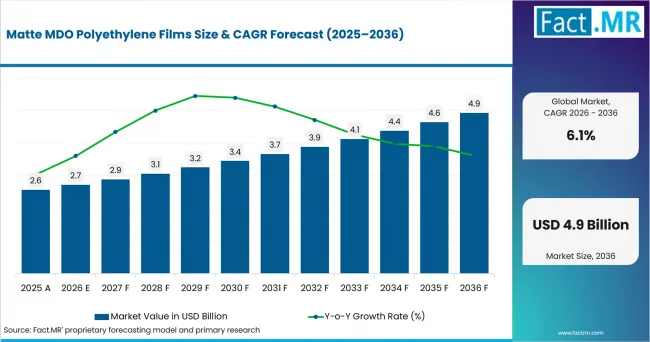
Matte Mdo Polyethylene Films Value Analysis | Source: Fact.MR
What are the defining numbers behind Matte MDO Polyethylene Films Market growth?
The market is projected to create an absolute dollar opportunity of approximately USD 2.2 billion between 2026 and 2036.
- Demand Drivers in the Market
- PE-rich packaging redesign is increasing interest in oriented polyethylene print webs that can replace dissimilar outer layers in flexible laminates.
- The EU Packaging and Packaging Waste Regulation began applying on 12 August 2026, raising the importance of recyclability, material composition and future recycled-content compliance in packaging design.
- Matte surfaces provide a low-gloss appearance for snacks, pet food, frozen food and personal-care packs without requiring the package to move away from a polyethylene-based structure.
- MDO processing improves stiffness and dimensional behavior in the machine direction, helping polyethylene function as a printable web in applications where conventional PE can be too extensible for tight registration.
- Key Segments Analyzed
- By Film Structure: MDO-PE mono-material accounts for 42.0% share in 2026, reflecting the shift toward predominantly polyethylene flexible structures.
- By Matte Route: Matte skin layer holds 34.0% share in 2026, supported by the ability to engineer surface appearance into the film structure.
- By Application: Snack packaging represents 27.0% share in 2026, where graphic coverage, fast converting and shelf differentiation are important purchase criteria.
- By Print Process: Flexographic printing accounts for 46.0% share in 2026, supported by its broad use across high-volume flexible packaging webs.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Senior Consultant, Fact.MR notes that the commercial test for matte MDO-PE is no longer appearance alone. Buyers increasingly want the print web, sealant layer, ink system and recycling design to work as one package specification. Suppliers that can hold matte consistency while controlling heat exposure, web stretch and seal conditions are better positioned to move projects from trial reels into repeat production.
- Strategic Implications
- Film suppliers should treat matte appearance, print treatment and lamination behavior as one qualification package rather than separate product attributes.
- Converters should validate sealing temperature and dwell time early because oriented PE outer layers can be more heat-sensitive than conventional PET print webs.
- Brand owners should assess inks, coatings, adhesives and barrier layers against the intended PE recycling route before a visual redesign is approved.
- Suppliers serving Europe should prepare product documentation for PPWR-era material and recyclability requirements while keeping country-level recovery systems in view.
Country growth differs materially. The UK is forecast at 4.3% CAGR from 2026 to 2036, the USA at 6.6%, Germany at 6.3%, France at 7.8% and Italy at 5.2%. The spread reflects differences in flexible-film collection, recyclability assessment, converter capacity and packaging fee structures.
How does the Matte MDO Polyethylene Films Market break down by segment?
The Matte MDO Polyethylene Films Market is segmented by Film Structure into MDO-PE mono-material, MDO-PE barrier laminate, MDO-PE with recycled content, Coextruded matte MDO-PE and Specialty BOPE/MDO hybrid; by Matte Route into Matte skin layer, Matte masterbatch, Surface embossing, Matte coating and Plasma / surface treatment; by Application into Snack packaging, Personal care, Pet food, Frozen food and Household / other; and by Print Process into Flexographic, Rotogravure, Digital, Offset / specialty and Other.
Why does MDO-PE mono-material lead demand within Film Structure?
MDO-PE mono-material holds 42.0% share in 2026.
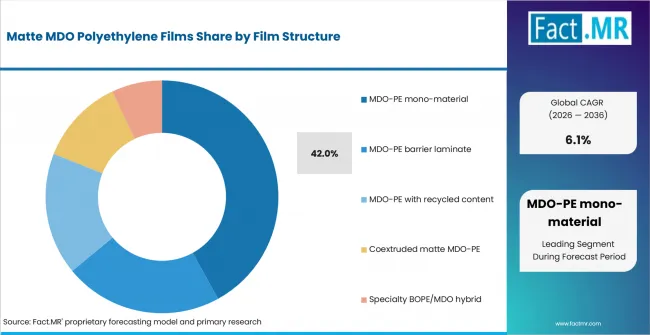
Matte Mdo Polyethylene Films Analysis By Film Structure | Source: Fact.MR
Machine-direction orientation gives a polyethylene web more stiffness and dimensional stability in the production direction. That is useful when the outer web must carry print and then laminate to another PE layer without creating the mixed-polymer structure associated with PET/PE or PA/PE constructions. This operating logic overlaps with the High-Recyclability Mono-Material Flexible Packaging Market, where design simplification must still preserve barrier, sealing and converting performance.
Why does Matte skin layer lead demand within Matte Route?
Matte skin layer holds 34.0% share in 2026.
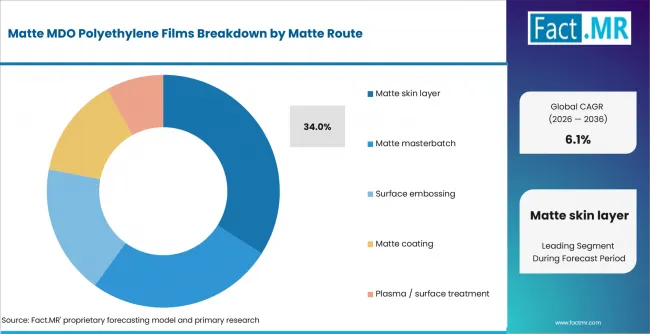
Matte Mdo Polyethylene Films Analysis By Matte Route | Source: Fact.MR
A matte skin layer builds the low-gloss effect into the film surface during extrusion or coextrusion. It can reduce reliance on a separate overprint matte treatment when the required appearance can be achieved directly in the film, while giving the converter a defined surface for printing or lamination.
Commercial development in 2026 shows that matte appearance is being combined directly with MDO-PE structures for food pouches. The key engineering issue is to preserve the desired surface while keeping the structure compatible with low-temperature sealing and the selected PE recycling route.
Why does Snack packaging lead demand within Application?
Snack packaging accounts for 27.0% share in 2026.
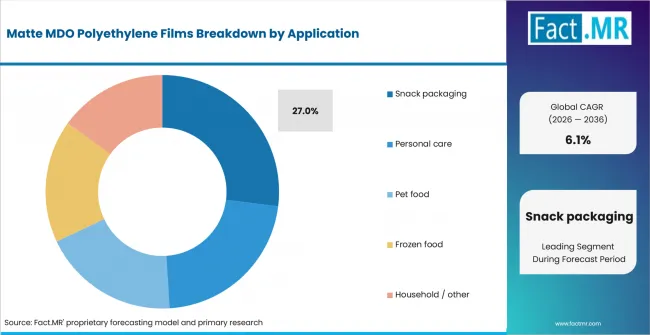
Matte Mdo Polyethylene Films Analysis By Application | Source: Fact.MR
Snack packs combine broad printed areas with high line speeds and frequent artwork changes. Matte MDO-PE can provide a differentiated low-gloss presentation while retaining the moisture resistance and sealing logic associated with polyethylene-based flexible packaging.
The application also intersects with the Plastic-Free Snack Packaging Market, because both markets are being shaped by brand efforts to redesign high-volume snack packs around clearer end-of-life claims.
Why does Flexographic printing lead demand within Print Process?
Flexographic printing accounts for 46.0% share in 2026.
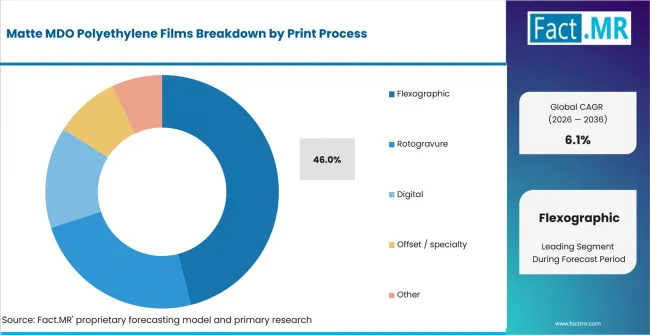
Matte Mdo Polyethylene Films Analysis By Print Process | Source: Fact.MR
Flexography is widely used for high-volume flexible packaging and can run treated PE webs at commercial widths. For matte MDO-PE, stable surface treatment and web tension are important because ink wetting, register and reel handling can change when the film formulation or surface texture changes.
Demand for printable PE webs also sits within the broader Polyfilm Market, where packaging remains a major outlet for polymer films used as printing and lamination substrates.
What is accelerating Matte MDO Polyethylene Films Market adoption, and what is holding it back?
Adoption is being accelerated by recyclable-packaging redesign, commercial availability of oriented PE webs and demand for premium matte presentation. The main constraints are heat sensitivity, surface and ink qualification, barrier design and the uneven collection of flexible plastics.
The impact values below are directional analytical estimates used to compare market mechanisms. They are not additive components of the 6.1% market CAGR.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| PE-rich recyclable packaging redesign | +1.2% | Europe, North America | Medium term (2-4 years) |
| PPWR and recyclability-design pressure | +0.9% | EU | Medium term (2-4 years) |
| Matte shelf differentiation in flexible packs | +0.7% | Global | Short term (<= 2 years) |
| Improved MDO-PE print-web performance | +0.5% | Europe, North America | Medium term (2-4 years) |
- PE-rich redesign: RecyClass maintains dedicated design-for-recycling guidance for PE flexible films and updates it as new evidence becomes available. That makes inks, adhesives, non-PE layers and coatings part of film qualification rather than secondary details.
- PPWR pressure: Regulation (EU) 2025/40 applies across the EU from 12 August 2026. The framework moves packaging procurement toward documented recyclability and future recycled-content requirements, increasing the value of structures that can remain within one polymer family where performance permits.
- Matte presentation: Brand teams continue to use matte surfaces to create a lower-gloss pack appearance. The opportunity for MDO-PE is to deliver that visual effect without forcing a return to a dissimilar print web.
- Print-web performance: Commercial MDO-PE platforms demonstrate that oriented PE can provide the stiffness needed for printing and lamination. This expands the addressable applications for mono-PE structures beyond simpler blown-film formats.
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Replacement of PET or PA outer webs with oriented PE | +0.9% | Europe, North America | Medium term (2-4 years) |
| PCR-compatible MDO-PE structures | +0.7% | UK, EU, USA | Long term (>= 4 years) |
| Snack, pet food and frozen-food pouch conversion | +0.6% | Global | Short term (<= 2 years) |
| Short-run and versioned matte graphics | +0.4% | USA, UK, France | Short term (<= 2 years) |
- Outer-web substitution: The clearest growth route is replacing conventional print webs while keeping the package predominantly PE. The conversion case is strongest when stiffness, print register and sealing can be maintained on existing equipment.
- That substitution theme is central to the Sustainable Plastic Packaging Market, where mono-material flexible formats are part of the wider move toward packaging designed for recovery.
- Recycled-content compatibility: Recycled-content targets increase interest in structures that can accept PCR in selected layers without undermining print quality or seal integrity. The practical constraint is that recycled resin, food-contact status and optical appearance cannot be treated as interchangeable specifications.
- Application conversion: Snack, dry pet food and frozen-food pouches are logical targets because they already use flexible laminates and can benefit from the stiffness of an oriented outer web. Each conversion still requires product-specific barrier and seal validation.
- The broader policy and procurement context is also reflected in the Sustainable Packaging Market, where recyclability and circular material use are influencing packaging investment across material types.
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Heat sensitivity and sealing-window constraints | -0.8% | Global | Short term (<= 2 years) |
| Ink, coating and adhesive recyclability qualification | -0.6% | Europe, North America | Medium term (2-4 years) |
| Barrier-performance trade-offs in PE-rich structures | -0.5% | Food and pet food packaging | Medium term (2-4 years) |
| Flexible-film collection and recycling gaps | -0.4% | UK, USA, selected markets | Long term (>= 4 years) |
- Heat sensitivity: Oriented PE outer layers can have a narrower thermal operating window than PET. Packaging trials therefore need to verify sealing temperature, dwell time and jaw conditions before a laminate is approved for full production.
- Recycling qualification: RecyClass guidance treats the entire PE flexible structure as relevant to recyclability. Inks, pigments, adhesives and barrier layers can change the result even when the main film is polyethylene.
- Barrier trade-offs: Moisture protection is natural territory for PE, but higher oxygen or aroma barrier can require additional layers or coatings. Those additions must be balanced against recycling compatibility and package economics.
- Collection gaps: Design for recycling does not guarantee that a flexible package is collected at scale. This remains especially important in markets where household flexible-film collection is still limited.
Which countries are scaling the Matte MDO Polyethylene Films Market through 2036?
Growth is strongest where flexible-packaging redesign is paired with a clear policy or recovery mechanism. France leads the country set at 7.8% CAGR, followed by the USA at 6.6% and Germany at 6.3%. Italy grows at 5.2%, while the UK expands at 4.3% as its recyclability-fee framework advances against a still-limited household collection base for flexible plastics.
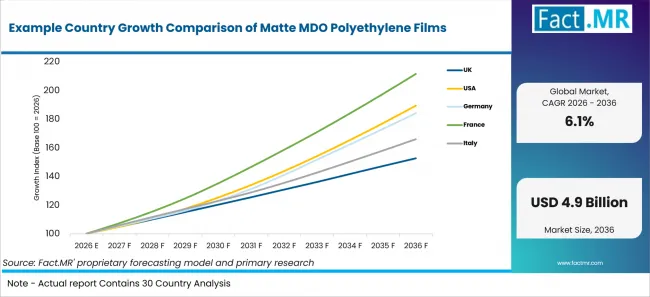
Example Country Growth Comparison Of Matte Mdo Polyethylene Films | Source: Fact.MR
| Country | CAGR |
|---|---|
| UK | 4.3% |
| USA | 6.6% |
| Germany | 6.3% |
| France | 7.8% |
| Italy | 5.2% |
What supports UK adoption?
4.3% CAGR through 2036, shaped by recyclability assessment and the limits of current flexible-plastic collection.
PackUK requires large producers to assess household packaging recyclability under the Recyclability Assessment Methodology. Ratings affect fee modulation, which makes material composition and recovery evidence visible in packaging procurement. At the same time, UK guidance notes that flexible plastics do not yet meet the widely collected threshold for kerbside recycling. Matte MDO-PE therefore has a design incentive, but the end-of-life route remains a practical constraint.
What supports USA growth?
6.6% CAGR through 2036, supported by food-contact qualification and commercial MDO-PE converting capability.
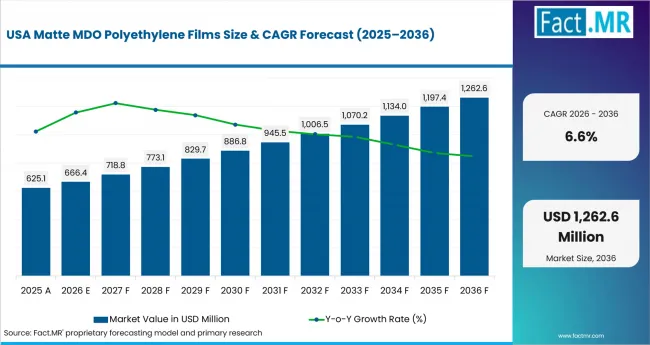
Matte Mdo Polyethylene Films Country Value Analysis | Source: Fact.MR
The U.S. Food and Drug Administration regulates substances used in food-contact packaging and reviews intended use and migration where authorization is required. For MDO-PE food packaging, that keeps resin, additive, adhesive and coating choices within the qualification process. The market also benefits from commercial experience with oriented PE print webs, including the Entour platform developed by the former Berry Global business and now within Amcor.
How is Germany scaling demand?
6.3% CAGR through 2036, with packaging design increasingly tested against real sorting and recycling routes.
Germany's Zentrale Stelle Verpackungsregister published the 2026 edition of its minimum standard for recycling-friendly packaging in August 2026. The methodology considers actual sorting and recovery practices and is being aligned with future PPWR classification logic. That favors film structures whose PE content, decoration and ancillary components can be explained against a defined recycling pathway.
What supports France growth?
7.8% CAGR through 2036, the fastest rate among the five countries assessed.
France combines broad household sorting of plastic packaging with continued investment in recycling capacity. ADEME notes that polyethylene flexible packaging is among the plastic formats with an operational recycling route, while France 2030 projects are adding regeneration capacity for flexible LDPE and other thermoplastics. This creates a stronger commercial case for PE-rich film structures when converters can preserve print and barrier performance.
What supports Italy adoption?
5.2% CAGR through 2036, influenced by differentiated packaging fees and an established converting base.
CONAI continues to differentiate environmental contributions for plastic packaging by category and adjusted the 2026 fee schedule as recycling-system costs changed. That gives converters and brand owners a direct economic signal to consider how a package fits sorting and recycling categories. Matte MDO-PE benefits when an all-PE or PE-rich structure can reduce material complexity without creating a new converting problem.
Who leads the Matte MDO Polyethylene Films Market?
Competition centers on oriented PE print-web capability, matte-surface control, mono-material laminate design and the ability to support converters through printing, lamination and sealing trials. Jindal Films, Amcor, Mondi and Coveris all participate in flexible-film platforms relevant to recyclable or PE-rich packaging. Taghleef Industries remains an important adjacent oriented-film competitor where converters compare PE-based designs with polypropylene-based alternatives.
Corporate structure matters in this market. Amcor completed its combination with Berry Global on 30 April 2025, and Berry shares were delisted. The former Berry flexible-film portfolio should therefore be treated as part of Amcor in a current 2026 competitive assessment rather than as an independent peer.
Berry's Entour MDO-PE/PE laminate work, now within Amcor, provides a commercial example of an oriented polyethylene print web for recyclable flexible packaging. Mondi offers MDO PE-based flexible laminates, while Coveris lists machine-direction orientation among its extrusion capabilities. Jindal Films offers oriented polyethylene films with matte-finish options and PE-laminate applications.
Which companies are active in the competitive landscape?
The competitive assessment covers the following current company groups and relevant legacy portfolio coverage:
- Amcor, including the former Berry Global business
- Jindal Films
- Mondi
- Coveris
- Taghleef Industries
Bibliography
- European Commission, Directorate-General for Environment. Packaging and Packaging Waste Regulation implementation materials, 2026.
- EUR-Lex. Regulation (EU) 2025/40 on packaging and packaging waste.
- RecyClass. Design for Recycling Guidelines for PE flexible films, 2026 updates.
- RecyClass. Recyclability Evaluation Protocol for PE Films, version 6.1, 2026.
- U.S. Food and Drug Administration. Food Packaging and Food Contact Substances.
- PackUK and Department for Environment, Food & Rural Affairs. Recyclability Assessment Methodology 2027 and supporting guidance.
- Zentrale Stelle Verpackungsregister. Minimum Standard for Determining the Recyclability of Packaging, 2026 edition.
- ADEME. Public guidance and France 2030 material on plastic packaging recycling and flexible PE regeneration.
- CONAI. Environmental Contribution for Packaging and 2026 plastic-packaging contribution updates.
- Amcor plc. Completion of the combination with Berry Global, April 2025, and 2026 annual reporting.
- Mondi. re/cycle FlexiBag and MDO PE-based flexible packaging information.
- Coveris. Extrusion capabilities including Machine Direction Orientation.
- Jindal Films. Ethy-Lyte oriented polyethylene flexible-packaging portfolio and 2026 product information.
- Walki and Dow. Mono-material MDO-PE packaging with matte finish, June 2026.
- Charter Next Generation. Matte-finish MDO-PE print film product announcement, September 2025.
This Report Answers
- How large is the Matte MDO Polyethylene Films Market in 2025, 2026 and 2036?
- Which Film Structure, Matte Route, Application and Print Process categories lead demand in 2026?
- How do the UK, USA, Germany, France and Italy differ in forecast growth through 2036?
- Which technical factors support the substitution of conventional print webs with MDO-PE?
- How do recyclability rules, inks, coatings, adhesives and barrier layers affect film qualification?
- Which current company groups participate in the competitive landscape, including the former Berry Global portfolio now within Amcor?
What does the Matte MDO Polyethylene Films Market cover?
The market covers commercial revenue from machine-direction-oriented polyethylene films and PE-rich laminate structures sold with an intentional matte surface for flexible packaging. The film may function as a printable outer web, a barrier-bearing web or part of a mono-material laminate, provided that MDO-PE is central to the structure and the matte finish is a specified product attribute.
Applications include snack packaging, personal care, pet food, frozen food and other household or consumer packs. Print-process coverage includes flexographic, rotogravure, digital and specialty methods used on treated or otherwise print-ready film surfaces.
What is included in the scope?
Included structures are MDO-PE mono-material films, MDO-PE barrier laminates, MDO-PE structures containing recycled content, coextruded matte MDO-PE and specialty BOPE/MDO hybrid constructions used in the defined packaging applications.
Matte routes include skin layers, masterbatch, embossing, coatings and plasma or surface treatment where the resulting film is sold for the specified flexible-packaging use. Revenue is counted at the film or converted-film level rather than at the value of the packaged product.
What is excluded from the scope?
The scope excludes conventional polyethylene films that are neither machine-direction oriented nor part of a defined specialty BOPE/MDO hybrid structure. Gloss-only MDO-PE sold without a matte specification is excluded from the core market boundary.
Rigid polyethylene packaging, finished consumer goods, converting machinery, printing presses, standalone inks, standalone adhesives and general-purpose polyethylene resin are outside the market. Other oriented-film markets such as BOPP are included only as competitive context, not as Matte MDO Polyethylene Films revenue.
How Was the Analysis Built?
- Primary Research: Inputs consider film extrusion, matte-surface control, printing, lamination, sealing, application qualification and packaging-recovery requirements across the value chain.
- Desk Research: Public evidence covers packaging regulation, food-contact controls, recyclability guidance, country recovery systems and current company participation.
- Market Sizing and Forecasting: The assessment uses the approved 2025, 2026 and 2036 market values, segment shares and country growth rates for the 2026 to 2036 forecast period.
- Data Validation and Update Cycle: Company status, regulatory developments and public technical evidence are checked for current relevance before publication.
What is the report’s scope and coverage?
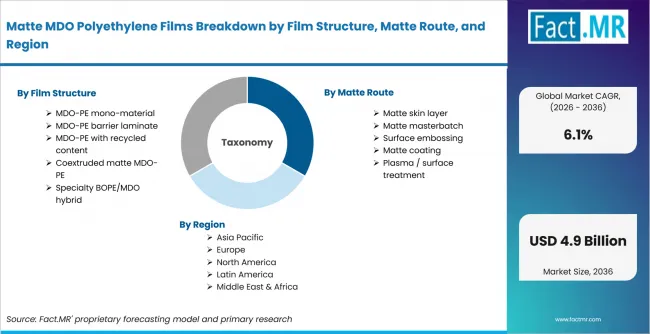
Matte Mdo Polyethylene Films Breakdown By Film Structure, Matte Route, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Machine-direction-oriented polyethylene films and PE-rich laminate structures sold with an intentional matte surface for flexible packaging. |
| Film Structure | MDO-PE mono-material; MDO-PE barrier laminate; MDO-PE with recycled content; Coextruded matte MDO-PE; Specialty BOPE/MDO hybrid |
| Matte Route | Matte skin layer; Matte masterbatch; Surface embossing; Matte coating; Plasma / surface treatment |
| Application | Snack packaging; Personal care; Pet food; Frozen food; Household / other |
| Print Process | Flexographic; Rotogravure; Digital; Offset / specialty; Other |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | UK; USA; Germany; France; Italy |
| Competitive Set | Amcor including former Berry Global business; Jindal Films; Mondi; Coveris; Taghleef Industries |
| Forecast Period | 2026 to 2036 |
| Approach | Market sizing, segment analysis and country growth assessment, supported by packaging regulation, recycling guidance and film-converting evidence. |
How is the market segmented?
-
By Film Structure
- MDO-PE mono-material
- MDO-PE barrier laminate
- MDO-PE with recycled content
- Coextruded matte MDO-PE
- Specialty BOPE/MDO hybrid
-
By Matte Route
- Matte skin layer
- Matte masterbatch
- Surface embossing
- Matte coating
- Plasma / surface treatment
-
By Application
- Snack packaging
- Personal care
- Pet food
- Frozen food
- Household / other
-
By Print Process
- Flexographic
- Rotogravure
- Digital
- Offset / specialty
- Other
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa

