- Market Value (2025): USD 4.2 Bn
- Estimated Value (2026): USD 4.5 Bn
- Forecast Value (2036): USD 8.5 Bn
- CAGR (2026-2036): 6.7%
What is the Aerosol Tube Non-BPA Linings Market forecast to be worth by 2036?
USD 4.5 billion in 2026 to USD 8.5 billion by 2036 at a 6.7% CAGR.
- As per Fact.MR analysis, the aerosol tube Non-BPA linings market reached USD 4.2 billion in 2025.
- Demand is projected to increase from USD 4.5 billion in 2026 to USD 8.5 billion by 2036.
- The aerosol tube Non-BPA linings market is forecast to record a 6.7% CAGR from 2026 to 2036.
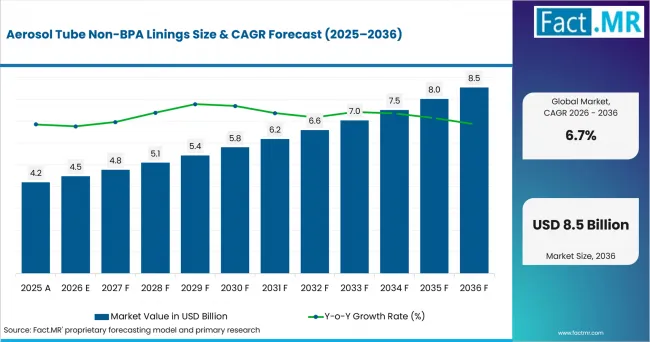
Aerosol Tube Non Bpa Linings Value Analysis | Source: Fact.MR
What are the defining numbers behind Aerosol Tube Non-BPA Linings Market growth?
According to Fact.MR analysis, an absolute opportunity of USD 4.1 billion is projected between 2026 and 2036.
- Demand Drivers in the Market
- Food and drink can makers need inner coatings that keep the product away from the metal. The EU BPA restriction started on 20 January 2025 and covers food-contact materials, including coatings and varnishes, with transition periods for some products [1].
- Coating makers need approved materials for metal food packaging. FDA Food Contact Notification 2408 took effect in February 2025 for a material used in polyester and polyester/polyurethane coatings on metal, with a maximum level of 46.1% in the final coating [2].
- Coatings need to protect the metal after material changes. FDA Food Contact Notification 2401 took effect in March 2025 for a barrier ingredient used in metal coatings, with a maximum use level of 10 g/m² [3].
- Aerosol and tube makers need coatings that stay strong during forming and filling. The coating must remain flexible, prevent corrosion, and work with the packed product during storage and handling.
- Key Segments Analyzed
- By Coating Chemistry: Polyester will hold 34.0% share in 2026 since it combines flexibility with chemical resistance across internal metal-packaging applications.
- By Package Type: Beverage cans will account for 31.0% share in 2026 as high-speed production lines need thin, even, and reliable internal coatings.
- By Coating Position: Internal lining will capture 36.0% share in 2026 because it provides the main barrier between the packed product and the metal surface.
- By Performance: Corrosion resistance will represent 29.0% share in 2026 since metal packages need protection throughout filling, storage, and normal product use.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Product approval takes time because new coatings need safety checks and production testing. Demand is higher for suppliers that provide clear safety, forming, and heat-testing results.”
- Strategic Implications
- Can makers should test more than one approved coating because food and drinks can have different filling needs. Aerosol and tube makers can also keep suitable coating options for different products.
- Coating suppliers should give clear drying and coating thickness details. In April 2025, Sherwin-Williams highlighted its valPure V70 non-BPA epoxy technology for metal food and drink packaging [9].
- Brands should set the same packaging requirements across regions before production tests begin. This can reduce repeated testing when the same package is sold in different markets.
- Tube and aerosol makers should test the inner coating after forming and sealing. This helps check whether the coating stays flexible and firmly attached before filling and storage.
As per Fact.MR analysis, China is forecast at 7.7% CAGR through 2036 and Japan follows at 6.6%. The USA and France each reach 6.2%, while Germany records 6.0% as package rules and converting scale shape country demand.
How does the Aerosol Tube Non-BPA Linings Market break down by segment?
Polyester leads Coating Chemistry at 34.0%; Internal lining leads Coating Position at 36.0%.
Which Coating Chemistry leads?
Polyester is expected to hold 34.0% share of coating chemistry in 2026.
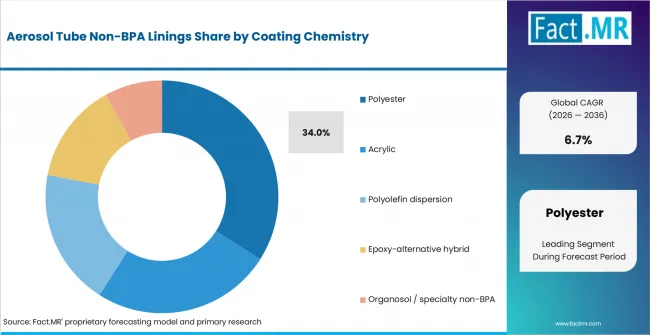
Aerosol Tube Non Bpa Linings Analysis By Coating Chemistry | Source: Fact.MR
Polyester is expected to lead because it sticks well to metal and stays flexible during forming. Acrylic coatings are used inside beverage cans, while polyolefin coatings provide protection for selected uses. These options give manufacturers several non-BPA coatings for surfaces that come in contact with the product.
What leads the Package Type segment?
Beverage cans are projected to account for 31.0% share in 2026.
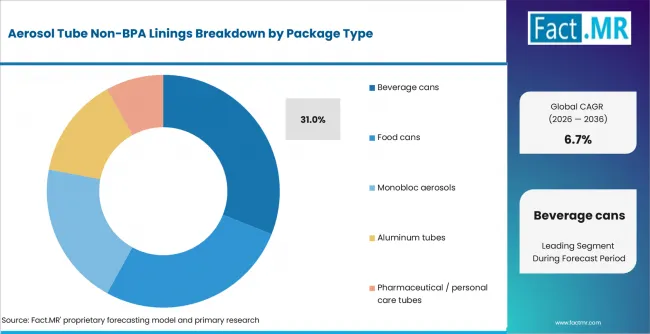
Aerosol Tube Non Bpa Linings Analysis By Package Type | Source: Fact.MR
Beverage cans are anticipated to capture as coatings need to work evenly on fast production lines. In July 2025, PPG added three BPA-NI coating options for aluminum beverage can ends, covering both inside and outside coating needs [8].
How does Coating Position shape demand?
Internal lining is anticipated to capture 36.0% share in 2026.
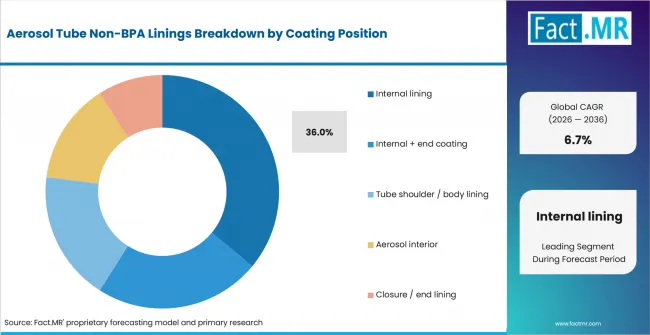
Aerosol Tube Non Bpa Linings Analysis By Coating Position | Source: Fact.MR
Internal linings are anticipated to lead since they keep the packed product away from the metal. End and closure coatings protect smaller areas, while tube linings need to stay strong during shaping and forming.
What supports Corrosion Resistance within Performance?
Corrosion resistance is estimated to represent 29.0% share in 2026.
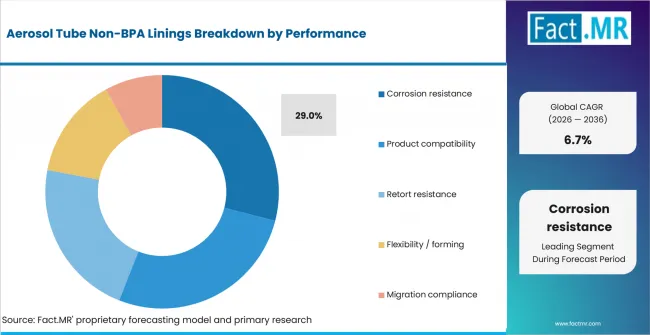
Aerosol Tube Non Bpa Linings Analysis By Performance | Source: Fact.MR
Corrosion resistance is expected to lead because coatings need to protect the metal during filling and storage. Suppliers must also check if the coating works safely with the packed product and meets safety rules for each type of packaging.
What is accelerating Aerosol Tube Non-BPA Linings Market adoption, and what is holding it back?
BPA restrictions increase demand for new coatings, while approval time and cost can slow the change.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| EU BPA restrictions on food-contact coatings | +1.6% | Western Europe | Short term (<= 2 years) |
| Qualification of non-BPA polyester and acrylic systems | +1.1% | Global | Medium term (2-4 years) |
| Beverage can and aluminum package conversion | +0.9% | North America, East Asia | Medium term (2-4 years) |
| Migration and corrosion documentation requirements | +0.7% | Global | Long term (>= 4 years) |
| Aerosol and tube use in personal care and pharma | +0.5% | Global | Medium term (2-4 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Polyester systems for food-contact metal | +0.9% | North America, Europe | Short term (<= 2 years) |
| Flexible linings for monobloc aerosols and tubes | +0.7% | Europe, East Asia | Medium term (2-4 years) |
| Low-VOC waterborne coating conversion | +0.6% | North America, Europe | Long term (>= 4 years) |
| Cross-regional compliance portfolios | +0.4% | Global | Medium term (2-4 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Long customer qualification cycles | -0.9% | Global | Medium term (2-4 years) |
| Forming and retort failures during reformulation | -0.7% | Global | Short term (<= 2 years) |
| Different regional food-contact requirements | -0.6% | Global | Long term (>= 4 years) |
| Higher testing and documentation cost | -0.4% | Global | Medium term (2-4 years) |
Which countries are scaling the Aerosol Tube Non-BPA Linings Market through 2036?
- China is projected to keep a 1.1-point lead over Japan as food and beverage manufacturing supports a broad metal-packaging base.
- Japan is expected to post 6.6% CAGR as its food-contact positive-list system raises the value of clear material records and controlled coating chemistry.
- The USA is forecast at 6.2% CAGR with demand shaped by FDA food-contact pathways and large beverage-can production.
- France is anticipated to record 6.2% CAGR as EU food-contact rules speed the shift toward non-BPA coating platforms.
- Germany is projected to reach 6.0% CAGR with packaged-food output and metal-packaging know-how supporting coating qualification.
Full coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific and Middle East & Africa.
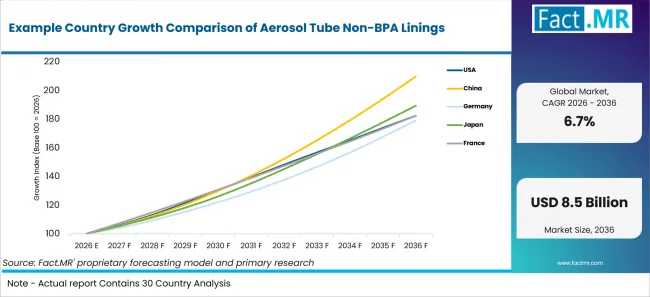
Example Country Growth Comparison Of Aerosol Tube Non Bpa Linings | Source: Fact.MR
| Country | CAGR (2026 to 2036) |
|---|---|
| China | 7.7% |
| Japan | 6.6% |
| USA | 6.2% |
| France | 6.2% |
| Germany | 6.0% |
What supports China adoption?
7.7% CAGR, supported by a large manufacturing base and metal-package conversion.
China has a large food and drink manufacturing industry that supports demand for non-BPA coatings. In February 2026, the National Bureau of Statistics reported that manufacturing grew 6.4% in 2025, while raw chemical manufacturing grew 7.8% [5]. Metal packaging companies need coatings that work consistently and have clear material information.
How is Japan scaling demand?
6.6% CAGR, shaped by the food-contact positive-list system.
Japan’s packaging companies check coating materials before approving them for food packaging. Japan’s revised positive-list requirements for food utensils, containers, and packaging took effect on June 1, 2025, following the end of the five-year transitional period [4]. This supports coatings with clear material information that stay stable during forming.
What supports the USA outlook?
6.2% CAGR, supported by active beverage-can coating development.
Demand for acrylic and other non-BPA coatings is expected to grow in U.S. metal food packaging. FDA Food Contact Notification 2451 took effect in January 2026 for acrylic coatings used on metal for single-use food packaging [10]. This gives packaging companies clear information for choosing coatings that meet food-contact rules.
How is France developing adoption?
6.2% CAGR, supported by aluminum package and aerosol coating conversion.
France is expected to benefit more use of coatings for aluminum bottles and aerosol packaging. In February 2025, PPG launched HOBA Pro 2848 at Paris Packaging Week as a non-BPA inner coating for aluminum drink bottles [7]. Companies need coatings that stay strong, work well with the packed product, and apply evenly to shaped aluminum packaging.
What supports Germany growth?
6.0% CAGR, supported by packaged-food production and coating qualification.
Germany’s food packaging industry is expected to support demand for protective metal coatings. In January 2026, Destatis reported that Germany produced 1.7 million tonnes of ready meals worth EUR 5.9 billion in 2024 [6]. This supports demand for food can coatings that prevent corrosion and remain strong during heat processing.
Who leads the Aerosol Tube Non-BPA Linings Market?
PPG Industries and AkzoNobel have broad non-BPA packaging-coating portfolios, while Sherwin-Williams, and ACTEGA add metal-package chemistry and application support.
AkzoNobel introduced its Accelshield™ BPAni range in Brazil in November 2025. These inner can coatings are made for fast beverage can lines. PPG and Sherwin-Williams also offer coatings for food and beverage cans.
Sherwin-Williams offers valPure® acrylic, polyester, and non-BPA epoxy coatings. ACTEGA offers coatings for metal packaging. Buyers can compare coating quality, ease of use, forming, safety rules, and technical support before choosing a coating.
Which companies are the key providers?
Key companies include PPG Industries; AkzoNobel; Sherwin-Williams (including Valspar heritage); and ACTEGA.
- PPG Industries
- AkzoNobel
- Sherwin-Williams (including Valspar heritage)
- ACTEGA
Bibliography
- [1] European Commission. (2025, December 17). Note for guidance on the implementation of Commission Regulation (EU) 2024/3190 on the use of bisphenol A (BPA) and other bisphenols and bisphenol derivatives with harmonised classification for specific hazardous properties in certain materials and articles intended to come into contact with food.
- [2] U.S. Food and Drug Administration. (2025, February 4). Inventory of effective food contact substance (FCS) notifications: FCN No. 2408.
- [3] U.S. Food and Drug Administration. (2025, March 12). Inventory of effective food contact substance (FCS) notifications: FCN No. 2401.
- [4] Consumer Affairs Agency & Ministry of Health, Labour and Welfare, Japan. (2025, May 23).[Questions and answers concerning the positive list system for food utensils, containers, and packaging].
- [5] National Bureau of Statistics of China. (2026, February 28). Statistical communiqué of the People's Republic of China on the 2025 national economic and social development.
- [6] Statistisches Bundesamt (Destatis). (2026, January 14). Produktion von Fertiggerichten binnen fünf Jahren mengenmäßig um 25,6 % gestiegen [Production of ready meals increased by 25.6% in volume within five years].
- [7] PPG. (2025, February 3). PPG launches non-BPA PPG HOBA coatings for aluminum bottles at Paris Packaging Week.
- [8] PPG. (2025, July 21). PPG adds BPA-NI beverage can end coatings to PPG INNOVEL and PPG iSENSE series.
- [9] Sherwin-Williams. (2025, April 16). Discovering a new epoxy coating – How valPure® V70 changed the game [Video].
- [10] U.S. Food and Drug Administration. (2026, January 8). Inventory of effective food contact substance (FCS) notifications: FCN No. 2451.
This Report Answers
- The report explains how non-BPA linings fit beside can coating technologies used on food and beverage cans. It also compares the coating boundary with wider metal packaging coatings used across metal packages.
- Segment analysis reviews beverage cans beside beverage can formats that require internal barrier performance.
- Package analysis covers aluminum tubes beside tube packaging formats used for cosmetics, pharmaceuticals and food products. The study also checks where metal can applications share similar corrosion and compatibility requirements.
- Application analysis includes selected pharmaceutical tubes and related pharmaceutical packaging where product contact and material control are central. It also considers pharmaceutical plastic packaging where resin and closure choices affect package performance.
- Material context includes aluminum foil packaging only where aluminum barrier use overlaps with the same end markets. The scope stays separate from rigid bulk packaging because large industrial containers use a different coating and package boundary.
What does the Aerosol Tube Non-BPA Linings Market cover?
The market covers non-BPA internal protective coatings for metal packages where the lining separates the product from aluminum or steel. It includes polyester, acrylic, polyolefin dispersion, epoxy-alternative hybrid, and specialty systems used on cans, aerosols, aluminum tubes, and selected closures.
The scope is narrower than full metal-packaging coatings because it centers on non-BPA product-contact linings. Decorative inks, external varnishes, adhesives, container equipment, and stand-alone sealants are excluded unless sold as part of the defined internal lining system.
What is included in the scope?
The scope includes non-BPA linings for beverage cans, food cans, monobloc aerosols, aluminum tubes, and pharmaceutical or personal-care tubes.
It covers internal lining, end coating, tube body lining, aerosol interiors, and closure lining. Performance includes corrosion resistance, compatibility, retort resistance, flexibility, and migration compliance.
What is excluded from the scope?
The scope leaves out BPA-based epoxy linings, external decorative coatings, printing inks, adhesives and stand-alone sealants.
Finished metal containers fall outside the revenue boundary because the assessment measures the lining material itself.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report’s scope and coverage?
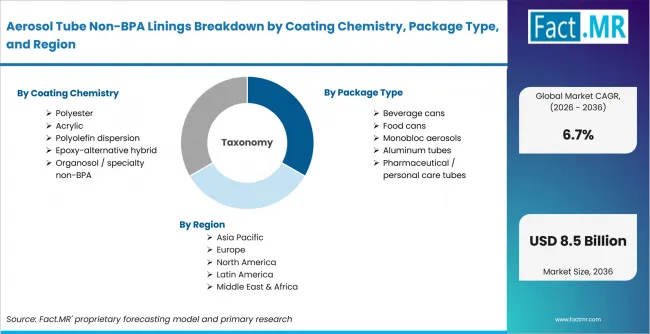
Aerosol Tube Non Bpa Linings Breakdown By Coating Chemistry, Package Type, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Non-BPA protective linings for metal cans, monobloc aerosols, aluminum tubes and related package surfaces used for food, beverages, personal care and pharmaceutical products. |
| Coating Chemistry | Polyester; Acrylic; Polyolefin dispersion; Epoxy-alternative hybrid; Organosol / specialty non-BPA |
| Package Type | Beverage cans; Food cans; Monobloc aerosols; Aluminum tubes; Pharmaceutical / personal care tubes |
| Coating Position | Internal lining; Internal + end coating; Tube shoulder / body lining; Aerosol interior; Closure / end lining |
| Performance | Corrosion resistance; Product compatibility; Retort resistance; Flexibility / forming; Migration compliance |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | China; Japan; USA; France; Germany |
| Key Companies Profiled | PPG Industries; AkzoNobel; Sherwin-Williams (including Valspar heritage); ACTEGA |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using coating chemistry mix, package conversion, country regulation, company portfolios, food-contact approvals, and converter qualification review. |
How is the market segmented?
-
By Coating Chemistry:
- Polyester
- Acrylic
- Polyolefin dispersion
- Epoxy-alternative hybrid
- Organosol / specialty non-BPA
-
By Package Type:
- Beverage cans
- Food cans
- Monobloc aerosols
- Aluminum tubes
- Pharmaceutical / personal care tubes
-
By Coating Position:
- Internal lining
- Internal + end coating
- Tube shoulder / body lining
- Aerosol interior
- Closure / end lining
-
By Performance:
- Corrosion resistance
- Product compatibility
- Retort resistance
- Flexibility / forming
- Migration compliance
-
By Region:
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa