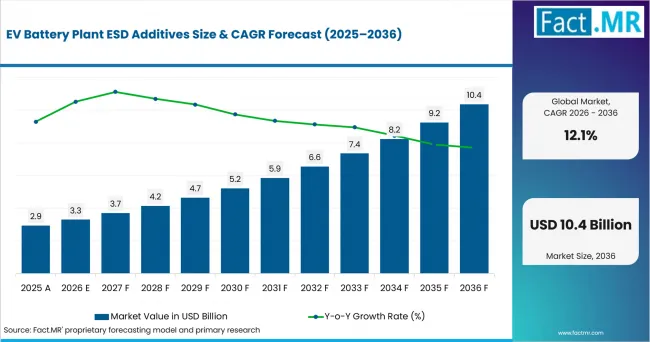
- Market Value (2025): USD 2.9 Bn
- Estimated Value (2026): USD 3.3 Bn
- Forecast Value (2036): USD 10.4 Bn
- CAGR (2026-2036): 12.1%
What is the EV Battery Plant ESD Additives Market forecast to be worth by 2036?
USD 3.3 Billion in 2026 to USD 10.4 Billion by 2036, at a 12.1% CAGR.
- The EV Battery Plant ESD Additives Market reached USD 2.9 Billion in 2025.
- Demand is projected to increase from USD 3.3 Billion in 2026 to USD 10.4 Billion by 2036.
- The market is forecast to grow at a 12.1% CAGR from 2026 to 2036.
Ev Battery Plant Esd Additives Value Analysis | Source: Fact.MR
What are the defining numbers behind EV Battery Plant ESD Additives Market growth?
The absolute opportunity is USD 7.1 Billion by 2036. Carbon black, antistatic systems, and chip fabs are key parts of the forecast.
- Demand Drivers in the Market
- Battery plant teams need a safe ohm range. Static charge near cells, modules, and power gear can raise quality and handling risks.
- Coating teams need ESD additive packs that keep floors strong. The same floor must meet antistatic or static-dissipative goals across large work areas.
- Cleanroom teams need low-dust ESD floors. The charge path must stay stable after cleaning, cart traffic, and process changes.
- Electronics teams need a good ground path near automated tools. Sensitive controls and test gear often sit beside fast production lines.
- Key Segments Analyzed
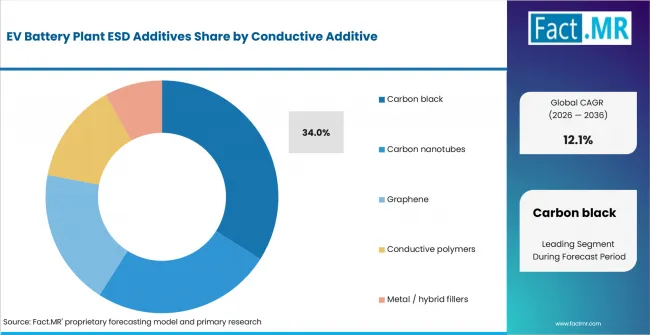
- By Conductive Additive: Carbon black is expected to hold 34.0% share in 2026. It is a common way to add a charge path in resin and floor coats.
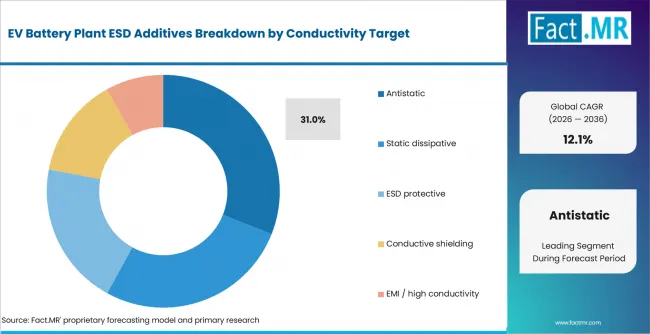
- By Conductivity Target: Antistatic is projected to account for 31.0% share in 2026. Many plant zones need less static charge without full shielding.
- By End-use Facility: Semiconductor fabs are anticipated to capture 36.0% share in 2026. ESD control is common in clean chip plants.
- By Coating System: Epoxy is estimated to represent 29.0% share in 2026. It is common in hard floors that need ESD control and chemical resistance.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Conductivity is only one part of the issue. A floor must keep a set ohm range after use and cleaning. Demand is expected to favor ESD systems that are easier to test in each resin. Suppliers can add value with good mixing, clear test data, and site support.”
- Strategic Implications
- Additive makers should report the floor ohm range after cure. They should also show results after the cleaning cycles used at the plant.
- Flooring teams should match filler load with resin flow. This can meet the ESD goal while keeping good coat quality and film strength.
- Plant teams should split antistatic zones from zones that need a lower ohm range. The material should match the risk in each work area.
- Coat crews should check the ground path across joints, repairs, and floor changes. The full floor must work as one ESD system.
China is projected to record 13.1% CAGR through 2036 as battery output grows. Japan is anticipated to post 12.0%. The USA and France are each forecast at 11.6%. Germany is expected to record 11.4%.
How does the EV Battery Plant ESD Additives Market break down by segment?
Carbon black leads Conductive Additive at 34.0%; semiconductor fabs lead End-use Facility at 36.0%.
Which Conductive Additive dominates?
Carbon black is expected to hold 34.0% share in 2026.
Ev Battery Plant Esd Additives Analysis By Conductive Additive | Source: Fact.MR
Carbon black is a common ESD filler. Teams can tune its load in epoxy and other resins. Carbon nanotubes can reach an ESD goal at a lower filler load. Graphene and conductive polymers serve other charge-control needs. Metal and hybrid fillers can give a stronger charge path or shielding.
What leads the Conductivity Target segment?
Antistatic is projected to account for 31.0% share in 2026.
Ev Battery Plant Esd Additives Analysis By Conductivity Target | Source: Fact.MR
Antistatic systems lead because many work zones need less static charge. Static-dissipative systems serve tighter ohm ranges near sensitive work. ESD systems also rely on good grounding. Conductive shielding and EMI systems serve areas with stronger signal-control needs. The final choice depends on the work area and target ohm range.
How does End-use Facility shape demand?
Semiconductor fabs are anticipated to capture 36.0% share in 2026.
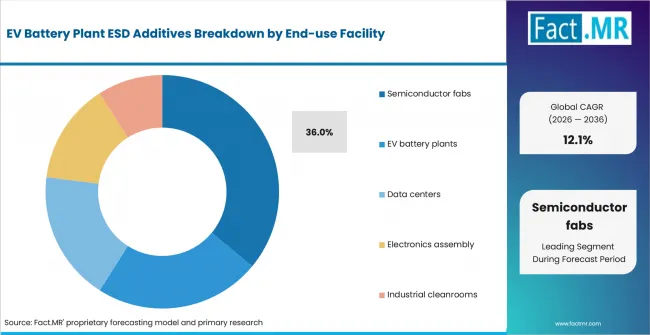
Ev Battery Plant Esd Additives Analysis By End Use Facility | Source: Fact.MR
Chip fabs lead because ESD control is part of clean plant work. EV battery plants add demand in dry rooms, module lines, and power-electronics areas. Data centers and electronics plants also use ESD floors near sensitive gear. Industrial cleanrooms need both dust control and ESD control. The IEA reports that global lithium-ion battery nameplate capacity exceeded 4 TWh at the end of 2025.
What supports Epoxy within Coating System?
Epoxy is estimated to represent 29.0% share in 2026.
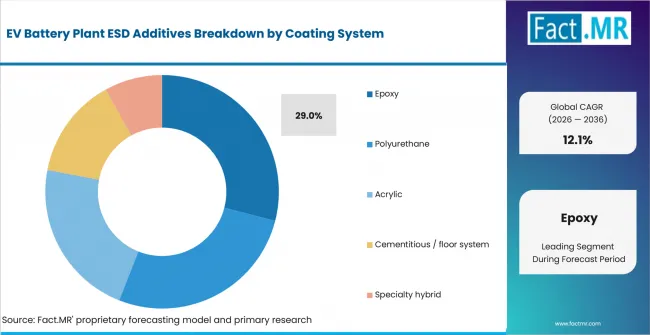
Ev Battery Plant Esd Additives Analysis By Coating System | Source: Fact.MR
Epoxy leads where plant owners need a hard ESD floor. Polyurethane can suit zones that need more flex or wear life. Acrylic can help a floor return to use faster. Cement systems can give a thicker build. Hybrid resins can serve tougher zones. PPG lists ESD flooring in its EV battery plant range.
What is accelerating EV Battery Plant ESD Additives Market adoption, and what is holding it back?
Battery-plant growth supports demand. Test and site work can slow a material change.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Battery manufacturing capacity expansion | +2.2% | China, North America, Europe | Short term (<= 2 years) |
| Cleanroom and electronics ESD controls | +1.7% | Global | Medium term (2-4 years) |
| Data-center and power-electronics buildout | +1.3% | USA, China, Europe | Medium term (2-4 years) |
| Resinous flooring refurbishment cycles | +0.9% | Global | Long term (>= 4 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Low-loading conductive additive packages | +1.4% | Global | Medium term (2-4 years) |
| Battery dry-room flooring systems | +1.1% | China, USA, Europe, Japan | Short term (<= 2 years) |
| Hybrid ESD and EMI formulations | +0.8% | Electronics hubs | Long term (>= 4 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Tight resistance-window qualification | -0.8% | Global | Short term (<= 2 years) |
| Dispersion and viscosity tradeoffs | -0.6% | Global | Medium term (2-4 years) |
| Plant investment volatility | -0.5% | USA, Europe, Japan | Medium term (2-4 years) |
Which countries are scaling EV Battery Plant ESD Additives Market fastest?
- China leads at 13.1% CAGR. Japan follows at 12.0%. The USA and France each record 11.6%. Germany records 11.4%.
- The displayed country range spans 1.7 percentage points from 2026 to 2036.
- China remains 1.1 percentage points above Japan. Its large battery plant base gives more context for ESD floor demand.
- Japan remains 0.4 percentage point above the USA. Battery policy and electronics output support its market base.
- The USA and France both record 11.6% CAGR. Their demand paths differ across battery spending and EV use.
- Germany closes the displayed range at 11.4%. EV output and plant upgrades support its market base.
Similar CAGRs can still mean different market conditions. Battery plant scale, electronics output, and test rules vary by country. Full report coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, and Middle East & Africa.
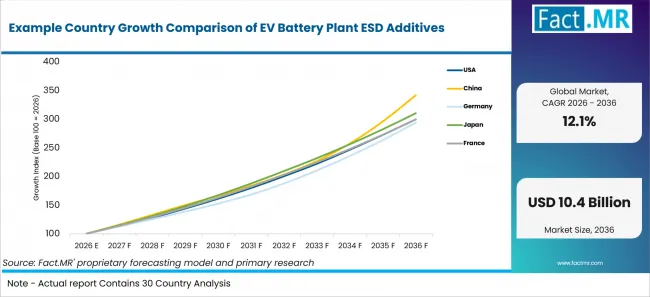
Example Country Growth Comparison Of Ev Battery Plant Esd Additives | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| China | 13.1% |
| Japan | 12.0% |
| USA | 11.6% |
| France | 11.6% |
| Germany | 11.4% |
How is China scaling demand?
13.1% CAGR, supported by battery output and plant growth.
China has a large battery plant base. ESD additives can be used in dry rooms, build lines, and electronics zones. The National Bureau of Statistics reported in February 2026 that new-energy vehicle output reached 16.524 million units in 2025, up 25.1%. Carbon black can suit low-cost floors. Nanotube and hybrid fillers can help where a low filler load is needed.
How is Japan scaling demand?
12.0% CAGR, supported by battery policy and electronics output.
Japan combines battery policy with a mature electronics base. The Ministry of Economy, Trade and Industry revised the Battery and Power Industry Strategy in June 2026. It set a target for a 150 GWh-per-year domestic manufacturing base from 2030 to the mid-2030s.
What supports USA adoption?
11.6% CAGR, supported by battery-plant spending and large cell plants.
The USA is adding battery capacity in several states. The U.S. Department of Energy reported in May 2025 that USD 1.8 billion had been disbursed to Ultium Cells for lithium-ion battery plants in Ohio and Tennessee before early repayment.
How is France scaling demand?
11.6% CAGR, supported by EV use and battery-related plant activity.
France has a growing EV base. The Service des données et études statistiques reported in February 2026 that battery-electric vehicles represented 19.9% of new passenger-car registrations in 2025. ESD additive demand is expected to focus on resin floors that keep a stable ohm range after cleaning.
What supports Germany's adoption?
11.4% CAGR, supported by EV activity and plant upgrades.
Germany has a large auto base and a strong electronics sector. Destatis reported in January 2026 that 30.0% of newly registered passenger cars in 2025 had an electric drive, equal to more than 856,500 vehicles. Carbon black is expected to keep broad use. Nanotube and hybrid systems can suit jobs that need less filler or a tighter ohm range.
Who leads the EV Battery Plant ESD Additives Market?
BASF, PPG Industries, AkzoNobel, Cabot Corporation, Avient, and Techmer PM form the profiled supplier group in the EV Battery Plant ESD Additives Market. Their relevance spans conductive additives, ESD-control materials, resinous flooring systems, and related coating technologies used across battery and controlled-electronics facilities.
PPG Industries participates through ESD flooring solutions associated with EV battery plant environments. Such systems must combine controlled electrical resistance with durable floor performance, chemical resistance, cleaning tolerance, and reliable grounding across production areas.
Cabot Corporation, Avient, and Techmer PM broaden the competitive field around conductive-filler and additive technologies. Market requirements extend across carbon black, carbon nanotubes, graphene, conductive polymers, and metal or hybrid fillers, giving formulators several routes to reach antistatic, static-dissipative, ESD-protective, or shielding targets.
BASF and AkzoNobel complete the profiled set alongside the coating and additive suppliers. Competition therefore depends on dispersion quality, resin compatibility, stable resistance after curing and cleaning, floor durability, grounding performance, and application support. Suppliers also need to match each formulation with the electrical-control requirement of the specific plant zone.
Which companies are the key providers?
Key companies include BASF; PPG Industries; AkzoNobel; Cabot Corporation; Avient; and Techmer PM.
- BASF
- PPG Industries
- AkzoNobel
- Cabot Corporation
- Avient
- Techmer PM
Bibliography
- International Energy Agency. (2026, May 20). Electric vehicle batteries. In Global EV Outlook 2026.
- International Energy Agency. (2026, May 20). Trends in electric cars. In Global EV Outlook 2026.
- National Bureau of Statistics of China. (2026, February 28). Statistical communiqué of the People’s Republic of China on the 2025 national economic and social development.
- U.S. Department of Energy. (2025, May 13). DOE receives early, voluntary repayment in full of Ultium Cells loan.
- U.S. Energy Information Administration. (2026, May 19). Data center server energy use grows across the commercial building stock.
- Statistisches Bundesamt (Destatis). (2026, January 22). E-Autos und Plug-in-Hybride: Ausstattung in Haushalten hängt stark vom Einkommen ab [E-cars and plug-in hybrids: Equipment in households depends strongly on income].
- Federal Ministry for Economic Affairs and Energy. (2025, December 19). 170 Millionen Euro für Transformationsprojekte in den Kohleregionen im Rahmen des Bundesförderprogramms STARK (Stärkung der Transformationsdynamik und Aufbruch in den Revieren und an den Kohlekraftwerkstandorten) [€170 million for transformation projects in coal regions under the STARK federal funding programme].
- Federal Network Agency. (2026, May 22). Electricity grid reserve capacity requirements confirmed.
- Service des données et études statistiques. (2026, February 11). Immatriculations de voitures en 2025 : le marché du neuf baisse, celui de l’occasion résiste [Car registrations in 2025: New market declines, used market resists].
- RTE. (2026, March 3). Annual Electricity Review 2025: Consumption.
- Institut national de la statistique et des études économiques. (2026, August 5). En juin 2026, la production manufacturière baisse de nouveau nettement (-1,1 % après -1,0 %) [In June 2026, manufacturing production declined sharply again (-1.1% after -1.0%)].
- Ministry of Economy, Trade and Industry. (2026, June 2). “Battery Industry Strategy” revised as the “Battery and Power Industry Strategy”.
- Japan Electronics and Information Technology Industries Association. (n.d.). December 2025 production by the Japanese electronics industry.
- PPG. (2025, May 19). PPG to showcase advanced coatings, EV total system solutions at The Battery Show Europe.
- Akzo Nobel N.V. (2026, February 24). Report 2025.
- Parker Hannifin Corporation, Chomerics Division. (2026, September). Electrically conductive elastomers and coatings: Volume resistivity and surface resistance measurement procedures (CEPS-0002).
This Report Answers
-
- The report explains where EV battery plant ESD additives are used across Conductive Additive, Conductivity Target, End-use Facility, and Coating System. It also covers regional demand across controlled manufacturing environments.
- Segment analysis identifies the leading subsegments and explains the operational reasons plant teams prioritize different conductive fillers, resistance targets, facility types, and resinous coating systems.
- Country analysis examines the USA, China, Germany, Japan, and France together with the battery-production, EV, electronics, and plant-development factors shaping ESD additive demand.
- Competitive analysis reviews current providers across conductive additives, ESD-control materials, resinous flooring systems, battery-related coatings, and supporting formulation technologies.
- Application analysis assesses how electrical resistance, grounding, dispersion, resin compatibility, cleaning durability, and floor performance influence material selection across battery plants and other controlled electronics facilities.
What does the EV Battery Plant ESD Additives Market cover?
The market covers ESD additives used in coats and floors for EV battery plants and clean electronics sites. It includes carbon black, carbon nanotubes, graphene, conductive polymers, and metal or hybrid fillers. Related demand also links with conductive carbon black and conductive plastic compounds.
The report covers antistatic, static-dissipative, ESD-protective, and shielding goals. It also covers epoxy, polyurethane, acrylic, and special floor systems. Site demand is viewed with industrial floor coats and resin floors where ESD performance is part of the final spec.
What is included in the scope?
The scope includes additives used in antistatic, static-dissipative, conductive, and shielding coats. It also covers resin floors where ESD performance is a set need. This includes new builds, plant growth, and approved floor repair.
Demand is counted only when the additive controls ohms or shielding. Battery-pack dielectric materials appear only in the rival set. They stay outside ESD additive demand unless they also control ohms or shielding.
What is excluded from the scope?
The scope excludes floor coats with no ESD role and raw battery active materials. It also excludes separate grounding hardware, ESD clothes, wrist straps, and test tools.
General EMI shield parts are excluded when sold without a coat or additive role. Battery heat-control products are also excluded when they only move heat or control flame.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report’s scope and coverage?
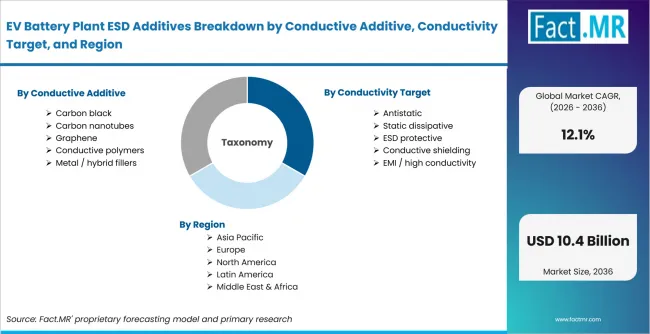
Ev Battery Plant Esd Additives Breakdown By Conductive Additive, Conductivity Target, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD Billion in 2026 to USD Billion by 2036 at a CAGR |
| Market Definition | Conductive and static-control additive systems used in coatings and flooring for EV battery plants and related controlled electronics facilities. |
| Conductive Additive | Carbon black; Carbon nanotubes; Graphene; Conductive polymers; Metal / hybrid fillers |
| Conductivity Target | Antistatic; Static dissipative; ESD protective; Conductive shielding; EMI / high conductivity |
| End-use Facility | Semiconductor fabs; EV battery plants; Data centers; Electronics assembly; Industrial cleanrooms |
| Coating System | Epoxy; Polyurethane; Acrylic; Cementitious / floor system; Specialty hybrid |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | USA; China; Germany; Japan; France |
| Key Companies Profiled | BASF; PPG Industries; AkzoNobel; Cabot Corporation; Avient; Techmer PM |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up assessment using battery-plant capacity signals, ESD coating specifications, end-use facility activity, country evidence and provider portfolio review. |
How is the market segmented?
-
By Conductive Additive
- Carbon black
- Carbon nanotubes
- Graphene
- Conductive polymers
- Metal / hybrid fillers
-
By Conductivity Target
- Antistatic
- Static dissipative
- ESD protective
- Conductive shielding
- EMI / high conductivity
-
By End-use Facility
- Semiconductor fabs
- EV battery plants
- Data centers
- Electronics assembly
- Industrial cleanrooms
-
By Coating System
- Epoxy
- Polyurethane
- Acrylic
- Cementitious / floor system
- Specialty hybrid
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa