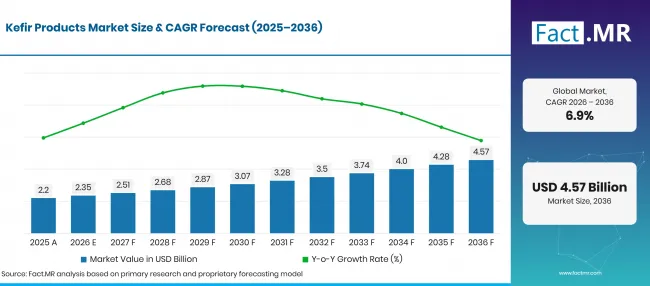
- Market Value (2025): USD 2.2 Bn
- Estimated Value (2026): USD 2.35 Bn
- Forecast Value (2036): USD 4.57 Bn
- CAGR (2026-2036): 6.9%
What is the Kefir Products Market forecast to be worth by 2036?
USD 2.35 billion in 2026 to USD 4.57 billion by 2036 at a 6.9% CAGR.
- As per Fact.MR analysis, the kefir products market reached USD 2.2 billion in 2025.
- Demand is projected to increase from USD 2.35 billion in 2026 to USD 4.57 billion by 2036.
- The kefir products market is forecast to record 6.9% CAGR from 2026 to 2036 as consumers add fermented dairy and probiotic drinks to regular food routines.
Kefir Products Market Breakdown Application (10) | Source: Fact.MR
What are the defining numbers behind Kefir Products Market growth?
An absolute opportunity of USD 2.2 billion is projected between 2026 and 2036.
- Demand Drivers in the Market
- Dairy companies need a steady milk supply and controlled fermentation to keep kefir consistent in texture and live cultures. USDA NASS reported in April 2026 that U.S. milk production reached 232 billion pounds in 2025, up 2.6% from 2024 [1].
- Health-focused shoppers are adding fermented foods to breakfast and snack choices because they fit easily into daily meals. Kefir requires little preparation and can be consumed directly or added to smoothies.
- Online stores and specialty retailers give smaller kefir brands more ways to reach buyers. In June 2025, Lifeway Foods announced new kefir placements in 61 Amazon Fresh stores and more than 1,400 Publix stores [4].
- Key Segments Analyzed
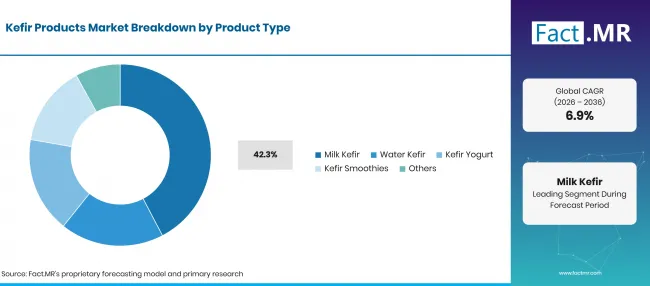
- By Product Type: Milk Kefir is projected to hold 42.3% share in 2026 because it matches the traditional product format and fits established chilled-dairy production.
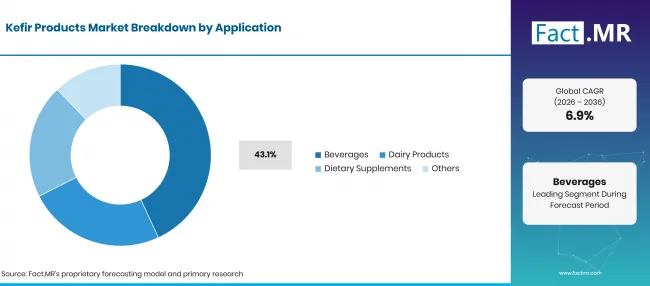
- By Application: Beverages are anticipated to account for 43.1% share in 2026 as ready-to-drink bottles make kefir easy to use at breakfast or between meals.
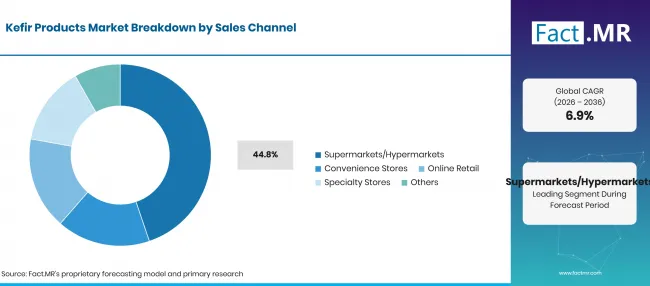
- By Sales Channel: Supermarkets/Hypermarkets are estimated to capture 44.8% share in 2026 owing to wide chilled-shelf access and easy comparison with yogurt and probiotic drinks.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Kefir gains more interest when shoppers see it as an easy part of their regular dairy purchases. Sales can increase as brands offer simpler formats and make products available through more stores and online channels. Suppliers also need reliable cultures, familiar flavors, and pack sizes that suit everyday household use.”
- Strategic Implications
- Kefir manufacturers need familiar flavors and a consistent texture while keeping live cultures stable during filling and cold storage. In January 2026, Danone said Activia Kefir mild was entering German food retail in two varieties [2].
- Retailers can place kefir near yogurt and functional drinks, where shoppers already look for chilled dairy products. Clear shelf information also helps buyers quickly see whether the product is made for drinking or eating with a spoon.
- Brands benefit from offering different pack sizes for first-time and regular buyers. Single-serve bottles make trial easier, while larger packs suit households that use kefir often for breakfast or smoothies.
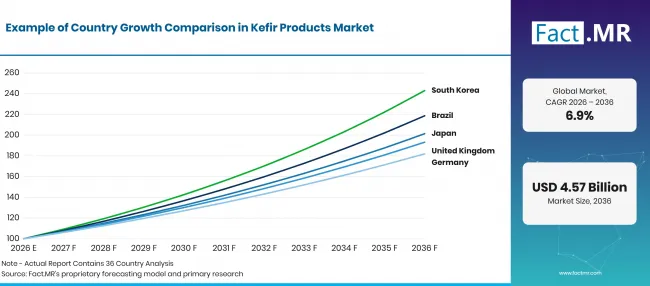
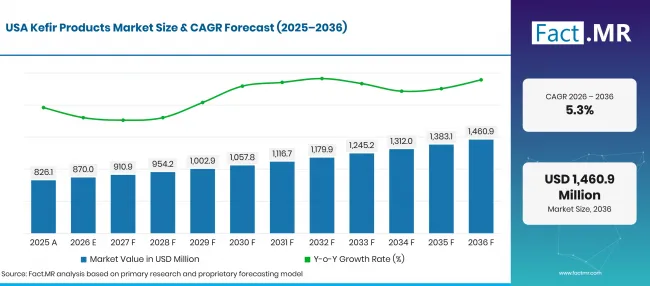
Brazil leads the five countries with an 8.1% CAGR through 2036, supported by growing milk supply. Japan follows at 7.3% as fermented dairy already fits local food habits. The UK records 6.8%, helped by wide availability of chilled dairy products. Germany grows at 6.2% with consumers already familiar with cultured dairy, while the United States reaches 5.3% as specialist kefir brands expand their store presence.
How does the Kefir Products Market break down by segment?
Milk Kefir is projected to lead Product Type at 42.3%; Beverages are anticipated to lead Application at 43.1%; Supermarkets/Hypermarkets are estimated to lead Sales Channel at 44.8%.
Which Product Type dominates?
Milk Kefir is projected to hold 42.3% share in 2026.
Kefir Products Market Breakdown Application (2) | Source: Fact.MR
Milk kefir is likely to lead because probiotic dairy products are already familiar to many shoppers, and bottled kefir comes in both plain and flavored options. Water kefir offers a dairy-free choice for people who prefer lighter fermented drinks. Kefir yogurt provides a thicker texture for breakfast bowls, while kefir smoothies combine cultured dairy with fruit flavors that are easy for shoppers to recognize.
What leads the Application segment?
Beverages are anticipated to account for 43.1% share in 2026.
Kefir Products Market Breakdown Application (1) | Source: Fact.MR
Beverages are projected to lead as functional beverages suit direct consumption at home, work, or while traveling. Dairy applications use kefir in cultured products served with regular meals and snacks. Dietary supplements target consumers looking for more specific nutrition options. Food companies and restaurants also add kefir to recipes where its fermented taste and texture suit the final dish.
How does Sales Channel shape demand?
Supermarkets/Hypermarkets are estimated to capture 44.8% share in 2026.
Kefir Products Market Breakdown Application (3) | Source: Fact.MR
Regular grocery trips put supermarkets and hypermarkets in a strong position for kefir sales, especially when several pack sizes are available in one store. Convenience stores serve a different buying pattern, with single bottles suited to quick purchases. Specialist brands often use online retail to reach customers beyond their physical store network. The U.S. Census Bureau reported in March 2026 that e-commerce sales reached USD 1,233.7 billion in 2025, rising 5.4% from 2024 [3]. For smaller kefir brands, this wider online buying base creates another source of repeat household sales.
What is accelerating Kefir Products Market adoption, and what is holding it back?
Wider availability in regular grocery stores is helping kefir reach more buyers. Keeping products chilled adds cost, while a shorter shelf life requires stores to manage stock and sales carefully.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Mainstream retail access to fermented dairy | +1.4% | Global | Short term (<= 2 years) |
| Consumer interest in live-culture foods | +1.2% | North America, Europe, East Asia | Medium term (2-4 years) |
| Product expansion into drinkable and spoonable formats | +1.0% | Global | Medium term (2-4 years) |
| Online discovery and repeat ordering | +0.7% | North America, Europe | Short term (<= 2 years) |
| Wider milk supply in key producing countries | +0.5% | North America, Latin America, Europe | Long term (>= 4 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| High-protein and low-added-sugar kefir formats | +0.8% | North America, Europe | Medium term (2-4 years) |
| Water kefir and non-traditional fermented drinks | +0.6% | North America, Europe, East Asia | Medium term (2-4 years) |
| Single-serve convenience packs | +0.5% | Global | Short term (<= 2 years) |
| Specialty and online expansion for smaller brands | +0.4% | Global | Short term (<= 2 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Cold-chain and shelf-life handling | -0.8% | Global | Short term (<= 2 years) |
| Milk and food price pressure | -0.6% | Europe, East Asia, Latin America | Medium term (2-4 years) |
| Competition from yogurt and other probiotic drinks | -0.5% | Global | Long term (>= 4 years) |
| Limited category familiarity in some markets | -0.3% | Latin America, parts of Asia | Medium term (2-4 years) |
Which countries are scaling the Kefir Products Market through 2036?
- Brazil is projected to keep a 0.8-point lead over Japan as milk production and formal dairy collection expand.
- Japan is forecast to stay 0.5 points ahead of the United Kingdom as fermented dairy remains familiar in everyday food routines.
- The United Kingdom is anticipated to remain 0.6 points above Germany as chilled dairy brands broaden functional product ranges.
- Germany is estimated to remain 0.9 points above the United States owing to long-standing use of cultured milk products.
- The United States is projected to close the five-country range as specialist kefir brands widen supermarket and online distribution.
Comparable CAGRs create different entry conditions because dairy habits and retail structure vary by country. Coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, and Middle East & Africa.
According to Fact.MR analysis, kefir overlaps with health-focused foods and functional beverages. The category reaches consumers through familiar chilled-food routines, yet it competes for space beside larger yogurt and wellness-drink ranges.
Kefir Products Market Breakdown Application (12) | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| Brazil | 8.1% |
| Japan | 7.3% |
| United Kingdom | 6.8% |
| Germany | 6.2% |
| United States | 5.3% |
What supports Brazil adoption?
8.1% CAGR, supported by expanding milk supply and modern chilled retail.
Brazil’s growing milk supply gives kefir companies more room to increase local production. In March 2026, the Brazilian Institute of Geography and Statistics reported that inspected dairies purchased 27.51 billion litres of raw milk in 2025, up 8.5% from 2024 [5]. Placing kefir near yogurt and cultured milk can improve its visibility in supermarkets. Familiar fruit flavors also give first-time buyers an easier way to try the product.
How is Japan developing demand?
7.3% CAGR, shaped by established fermented-dairy habits and convenience-led retail.
Japan’s familiarity with fermented dairy gives kefir a natural place in the chilled food market. In July 2025, the Ministry of Agriculture, Forestry and Fisheries reported that raw milk production reached 627,859 tonnes in June 2025, up 1.9% from a year earlier [6]. Smaller bottles suit shoppers looking for quick and convenient options. Familiar cultured flavors also make kefir easier for first-time buyers to understand and try.
What is supporting the United Kingdom’s adoption?
6.8% CAGR, supported by higher milk output and broad chilled grocery distribution.
Wide supermarket coverage and a growing number of specialist brands are making kefir more visible across the UK. In September 2026, the Department for Environment, Food & Rural Affairs reported that milk production for human consumption reached 15.8 billion litres in 2025, up 5.0% from 2024 [7]. Drinkable and spoonable kefir can share the same chilled sections as yogurt, making the product easier to include in regular grocery purchases.
What supports Germany’s growth?
6.2% CAGR, backed by established cultured-dairy habits and a mature dairy supply chain.
Kefir is already familiar to many German shoppers as part of the country’s cultured dairy range. Federal agriculture statistics reported in April 2026 that drinking-milk consumption averaged about 45.1 kilograms per person in 2025, down 2.2% from 2024 [8]. Brands can separate kefir from regular milk through its fermented taste and live cultures. Existing chilled sections for yogurt and fresh dairy also give the product an established route to shoppers.
How is the United States scaling demand?
5.3% CAGR, driven by specialist brand scale and wider supermarket access.
Kefir Products Market Breakdown Application (11) | Source: Fact.MR
Specialist kefir brands already have a presence in the United States, supported by wide access to chilled retail space. In February 2026, the U.S. Bureau of Labor Statistics reported that food-at-home prices in January 2026 were 2.1% higher than a year earlier [9]. With grocery costs rising, pack size and price play an important role in repeat purchases. Wider supermarket availability also helps kefir reach buyers beyond health-food stores.
Who leads the Kefir Products Market?
Competition includes specialist kefir brands as well as large dairy companies with cultured products in several markets. Lifeway Foods has a strong focus on kefir, while Danone sells Activia Kefir as part of its cultured dairy range.
Nestlé and Arla Foods bring wider dairy distribution, while Biotiful focuses on kefir drinks, yogurt, and other kefir-based products. Companies compete through chilled distribution, familiar products, and enough variety to meet different consumer needs.
Emmi also keeps kefir within its current dairy portfolio. In its February 2026 annual-results presentation, the company included kefir among products linked with growing consumer interest in digestion and gut health [10]. Its 2025 Annual Report also highlighted Kaiku’s kefir range in Spain within this area. This shows how a larger dairy group continues to include fermented dairy products in its growth plans.
Which companies are the key providers?
Key companies include Lifeway Foods, Inc.; Danone S.A.; Nestlé S.A.; Arla Foods; Emmi Group; Valio Ltd.; Biotiful Dairy Ltd.; and Babushka’s Kefir.
- Lifeway Foods, Inc.
- Danone S.A.
- Nestlé S.A.
- Arla Foods
- Emmi Group
- Valio Ltd.
- Biotiful Dairy Ltd.
- Babushka’s Kefir
Bibliography
- [1] U.S. Department of Agriculture, National Agricultural Statistics Service. (2026, April 30). Milk Production, Disposition, and Income 2025 Summary.
- [2] Danone. (2026, January 14). Activia erweitert sein Sortiment: Cremig-milder Kefir für ein gutes Bauchgefühl.
- [3] U.S. Census Bureau. (2026, March 10). Quarterly Retail E-Commerce Sales: 4th Quarter 2025.
- [4] Lifeway Foods, Inc. (2025, June 4). Lifeway Foods Expands Retail Footprint with Thousands of New Lifeway Kefir and Farmer Cheese Placements Across Major U.S. Retailers in 2025.
- [5] Brazilian Institute of Geography and Statistics (IBGE). (2026, March 18). In 2025, Brazil registers the highest production of milk, leather and eggs in history; slaughter of cattle, chickens and pigs also hits record.
- [6] Ministry of Agriculture, Forestry and Fisheries of Japan. (2025, July 29). 牛乳乳製品統計(令和7年6月分) [Milk and Dairy Products Statistics: June 2025].
- [7] Department for Environment, Food & Rural Affairs. (2026, September 3). Agriculture in the United Kingdom 2025: Chapter 8: Livestock.
- [8] Federal Ministry of Agriculture, Food and Regional Identity (BMLEH). (2026, April 15). Versorgungsbilanzen Milch und Milchprodukte 2025 [Supply balances for milk and dairy products 2025].
- [9] U.S. Bureau of Labor Statistics. (2026, February 13). Consumer Price Index – January 2026.
- [10] Emmi Group. (2026, February 26). Annual results 2025 [Presentation].
This Report Answers
- The report explains how kefir products are sold by product type, application and sales channel.
- Segment analysis identifies the leading subsegment and the operating reason behind its 2026 share.
- Country analysis compares five markets through milk supply, consumer spending, retail access and local dairy habits.
- Competitive analysis reviews active kefir brands and larger dairy companies with current direct kefir products.
- Channel analysis explains how supermarkets, convenience stores, online retail and specialty stores shape product discovery and repeat purchase.
What does the Kefir Products Market cover?
The Kefir Products Market covers finished fermented products sold for direct consumption. It includes milk kefir, water kefir, kefir yogurt and kefir smoothies across grocery, specialty and online channels.
The assessment connects kefir with functional beverages and functional foods where fermented dairy is positioned around everyday nutrition and digestive wellness. These adjacent categories help explain how kefir competes for the same chilled shelf space and household spending.
What is included in the scope?
The scope includes milk kefir, water kefir, kefir yogurt and kefir smoothies sold through grocery, convenience, specialty and online channels. Product formats that overlap with drinkable yogurt are included when kefir positioning is clear.
Finished kefir products made with live cultures are included. Upstream cultures and fermentation ingredients are used only to explain product formulation and supply context.
What is excluded from the scope?
The scope excludes plain yogurt sold without kefir positioning and stand-alone probiotic supplements. Starter cultures sold only as manufacturing inputs remain outside the revenue boundary. Plant-based beverages are outside the core scope unless they are clearly sold as water kefir.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report’s scope and coverage?
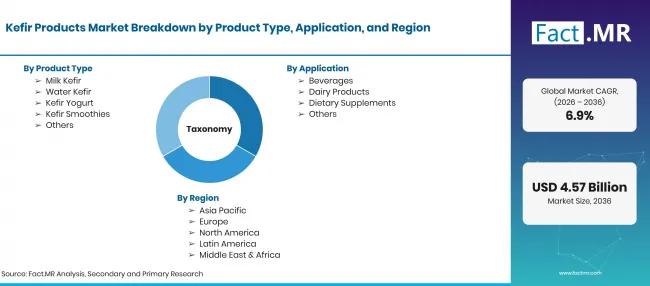
Kefir Products Market Breakdown Application (17) | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion in 2026 to USD billion by 2036 at a CAGR |
| Market Definition | Fermented kefir products sold as milk kefir, water kefir, kefir yogurt, kefir smoothies and related finished products through retail and online channels. |
| Product Type | Milk Kefir; Water Kefir; Kefir Yogurt; Kefir Smoothies; Others |
| Application | Beverages; Dairy Products; Dietary Supplements; Others |
| Sales Channel | Supermarkets/Hypermarkets; Convenience Stores; Online Retail; Specialty Stores; Others |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | Brazil; Japan; United Kingdom; Germany; United States |
| Key Companies Profiled | Lifeway Foods, Inc.; Danone S.A.; Nestlé S.A.; Arla Foods; Emmi Group; Valio Ltd.; Biotiful Dairy Ltd.; Babushka’s Kefir |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using retail availability, dairy production, channel access, company portfolios, country growth and product-format adoption. |
How is the market segmented?
-
By Product Type
- Milk Kefir
- Water Kefir
- Kefir Yogurt
- Kefir Smoothies
- Others
-
By Application
- Beverages
- Dairy Products
- Dietary Supplements
- Others
-
By Sales Channel
- Supermarkets/Hypermarkets
- Convenience Stores
- Online Retail
- Specialty Stores
- Others
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa