- Market Value (2025): USD 2.1 Bn
- Estimated Value (2026): USD 2.3 Bn
- Forecast Value (2036): USD 5.9 Bn
- CAGR (2026-2036): 9.8%
What is the Clean Mouthfeel Protein Alternatives Market forecast to be worth by 2036?
USD 2.3 billion in 2026 to USD 5.9 billion by 2036, at a 9.8% CAGR.
- The Clean Mouthfeel Protein Alternatives Market was valued at USD 2.1 billion in 2025.
- Demand is projected to increase from USD 2.3 billion in 2026 to USD 5.9 billion by 2036.
- The market is forecast to record a 9.8% CAGR from 2026 to 2036 as food teams pursue protein enrichment while preserving creaminess and a clean taste finish.
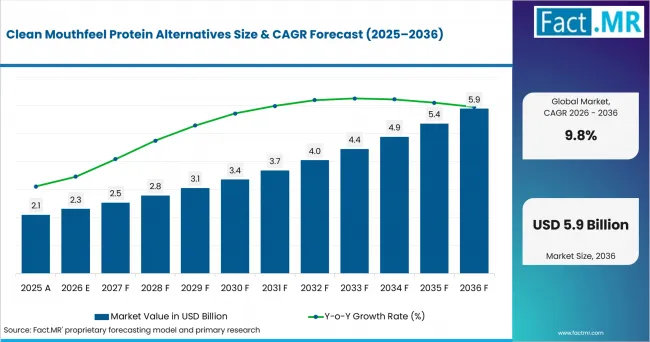
Clean Mouthfeel Protein Alternatives Value Analysis | Source: Fact.MR
What are the defining numbers behind Clean Mouthfeel Protein Alternatives Market growth?
The market offers USD 3.6 billion in absolute opportunity by 2036.
- Demand Drivers in the Market
- Dairy food teams need proteins that raise nutrition while preserving a creamy texture in reduced-fat yoghurts, desserts, drinks, and dairy alternatives. The main need is simple.
- Beverage teams need soluble protein systems that control sediment and viscosity build-up while maintaining a smooth finish as protein levels rise in ready-to-drink recipes.
- Bakery and nutrition-food teams need protein formats that retain softness and reduce dry or gritty eating quality across the intended shelf life.
- Plant-based product teams need neutral-tasting proteins that reduce beany notes and support a smoother texture with fewer masking ingredients.
- Key Segments Analyzed
- By Protein Platform: Whey proteins are expected to hold 34.0% share in 2026 due to their established nutrition quality and broad function in dairy and nutrition uses.
- By Functional Role: Lubrication / creaminess is projected to account for 31.0% share in 2026 as food teams use protein systems to restore body and smoothness in lower-fat products.
- By Application: Dairy / alternatives are expected to capture 36.0% share in 2026. Protein enrichment and fat reduction both make mouthfeel a key recipe need.
- By Format: Powder concentrate is estimated to represent 29.0% share in 2026 owing to flexible dosing, storage, blending, and use across dry and wet food systems.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “The commercial test is whether added protein still feels familiar in the finished food. Demand is expected to favor systems that control roughness and afterfeel. Suppliers need protein function and use support.”
- Strategic Implications
- Dairy-alternative food teams should screen protein source and particle profile together because taste roughness often appears before nutrition targets are reached.
- Beverage teams should test solubility and sediment control across pH and heat-treatment conditions before scaling a clean-mouthfeel claim into commercial production.
- Ingredient distributors should organize portfolios by functional outcome such as creaminess or emulsion support so product teams can shortlist systems more efficiently.
China is projected to record 10.7% CAGR through 2036 as food processing expands. Japan is anticipated to post 9.6% through health-oriented foods. The USA is estimated at 9.2% across broad protein uses. France is forecast at 9.2% as dairy processing supports demand. Germany is expected to record 9.0% as convenience-food recipe updates support texture-sensitive proteins.
How does the Clean Mouthfeel Protein Alternatives Market break down by segment?
Whey proteins lead Protein Platform at 34.0%; dairy / alternatives lead Application at 36.0%.
Which Protein Platform dominates?
Whey proteins are expected to hold 34.0% share in 2026.
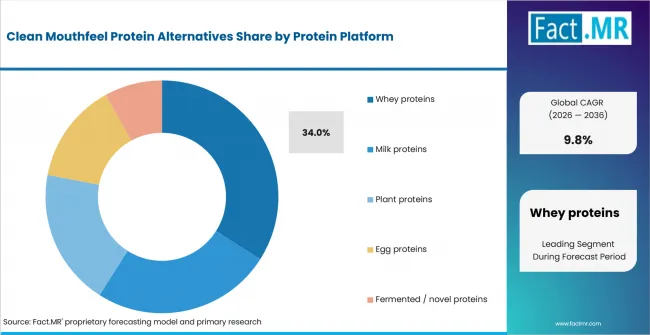
Clean Mouthfeel Protein Alternatives Analysis By Protein Platform | Source: Fact.MR
Whey proteins are expected to lead because they combine high protein quality with functional results in dairy and nutrition foods. Milk proteins support familiar body and stable texture in dairy formats. Plant proteins widen the recipe base for dairy alternatives and drinks where taste control remains central. Egg proteins support structure in bakery uses. Fermented and novel proteins expand the range of systems available for specialized nutrition and alternative-protein products. These proteins work in many food types and are easy to test at bench scale. That broad fit supports steady use in both dairy and nutrition foods.
In November 2025, Arla Foods Ingredients announced five new high-protein food and beverage concepts showcasing its portfolio of milk and whey protein ingredients. The concepts combine protein enrichment with taste and functional results, which aligns closely with demand for smoother high-protein recipes.
What leads the Functional Role segment?
Lubrication / creaminess is projected to account for 31.0% share in 2026.
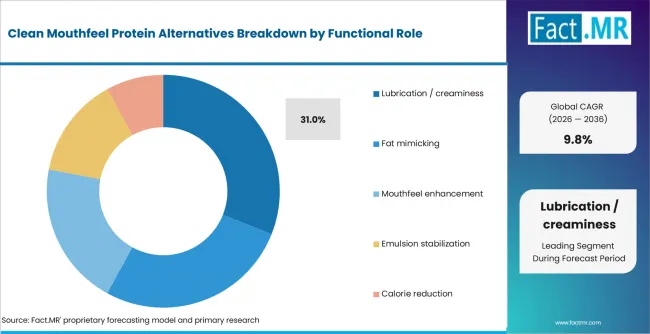
Clean Mouthfeel Protein Alternatives Analysis By Functional Role | Source: Fact.MR
Lubrication and creaminess are projected to lead because higher protein levels and lower fat content can change body and eating quality. Fat-mimicking systems restore fullness in reduced-fat products while mouthfeel enhancers improve flow and smoothness. Emulsion stabilization supports consistent texture across dairy and sauce uses. Calorie-reduction recipes use these functions to preserve a fuller taste profile while meeting nutrition targets. A fuller feel can make a lean recipe seem richer during eating. That link between texture and taste keeps this role close to product design.
How does Application shape demand?
Dairy / alternatives are expected to capture 36.0% share in 2026.
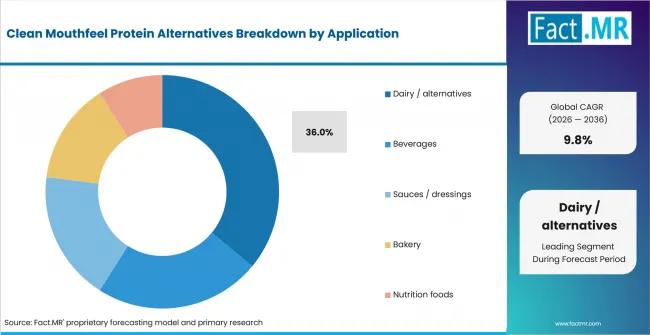
Clean Mouthfeel Protein Alternatives Analysis By Application | Source: Fact.MR
Dairy and dairy alternatives are anticipated to lead because creaminess remains a defining taste cue in drinks and spoonable products. Beverage recipes require low sediment and a clean finish at higher protein levels. Sauces need stable emulsions and bakery products need softness across shelf life. Nutrition foods place similar pressure on food teams because high protein content must remain compatible with familiar taste and texture. Creamy texture is easy for people to notice in drinks and spoonable foods. A smooth finish can help a protein-rich product feel more familiar.
What supports Powder Concentrate within Format?
Powder concentrate is expected to represent 29.0% share in 2026.
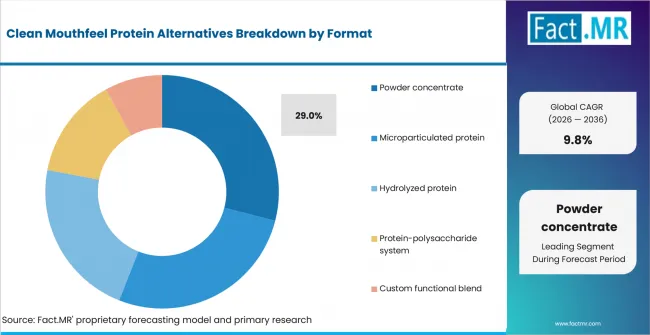
Clean Mouthfeel Protein Alternatives Analysis By Format | Source: Fact.MR
Powder concentrate is estimated to lead because it supports efficient storage and flexible dosing across dry and wet recipes. Microparticulated protein targets a smoother fat-like perception in dairy systems. Hydrolyzed protein supports solubility where rapid dispersion is needed. Protein-polysaccharide systems combine nutrition with texture control. Custom functional blends bring protein results and process tolerance into one recipe route. Powders also give food teams more control over dose and batch size. That makes early trials easier before a recipe moves to full production.
What is accelerating Clean Mouthfeel Protein Alternatives Market adoption, and what is holding it back?
Protein enrichment drives adoption; taste roughness and recipe cost restrain wider use.
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Protein enrichment with sensory retention | +1.9% | Global | Short term (<= 2 years) |
| Dairy and dairy-alternative reformulation | +1.5% | North America, Europe, East Asia | Medium term (2-4 years) |
| High-protein beverages and nutrition foods | +1.2% | Global | Medium term (2-4 years) |
| Lower-fat formulations needing creaminess | +0.9% | North America, Europe | Long term (>= 4 years) |
| Cleaner-tasting plant protein systems | +0.7% | Europe, East Asia | Long term (>= 4 years) |
Opportunity Impact Analysis
| Opportunity | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Microparticulated protein systems | +1.0% | Europe, North America | Medium term (2-4 years) |
| Acid-stable plant protein beverages | +0.8% | North America, East Asia | Short term (<= 2 years) |
| Protein-polysaccharide functional blends | +0.6% | Global | Medium term (2-4 years) |
| Application-specific sensory validation | +0.5% | Global | Long term (>= 4 years) |
Restraints Impact Analysis
| Restraint | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Chalkiness, grittiness, or off-notes | -0.8% | Global | Short term (<= 2 years) |
| Higher cost of specialty protein systems | -0.6% | Global | Medium term (2-4 years) |
| Heat, pH, and shear sensitivity | -0.4% | Global | Medium term (2-4 years) |
| Label and allergen constraints | -0.3% | North America, Europe, East Asia | Long term (>= 4 years) |
Which countries are scaling Clean Mouthfeel Protein Alternatives Market fastest?
- The country comparison spans 1.7 percentage points and forms three practical growth bands across the forecast period.
- China remains 1.1 percentage points above Japan as dairy output and a large processed-food base support wider use of proteins with milder taste and controlled texture.
- Japan remains 0.4 percentage point above the USA as food-processing activity and demand for compact nutrition formats support protein systems with smooth texture and reliable dispersion.
- The USA and France both record 9.2% CAGR, with the USA supported by its broad food-production base and protein-rich applications, while France benefits from its established dairy-processing base and continued recipe updates.
- · France remains 0.2 percentage point above Germany as dairy-processing expertise supports texture-led protein formulation across desserts, drinks, and lower-fat products.
- Germany closes the displayed range through convenience-food output and recurring recipe updates that support proteins designed to raise nutrition value while preserving familiar texture.
Comparable CAGRs can create different entry conditions due to dairy and food-processing activity, protein-enrichment needs, recipe formats, sensory requirements, and local product-development priorities. Full report coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Middle East & Africa.
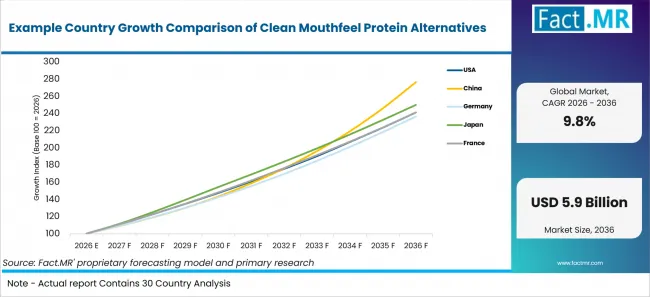
Example Country Growth Comparison Of Clean Mouthfeel Protein Alternatives | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| China | 10.7% |
| Japan | 9.6% |
| USA | 9.2% |
| France | 9.2% |
| Germany | 9.0% |
What supports USA adoption?
9.2% CAGR, supported by a broad food-production base and protein-rich dairy uses.
U.S. food teams work across a large food economy that supports continuous product renovation in dairy, drinks, bakery, and nutrition foods. The USDA Economic Research Service reported in June 2026 that total U.S. food spending reached USD 2.51 trillion in 2025. The USA is anticipated to record a 9.2% CAGR through 2036 as product teams place greater value on protein systems that combine nutrition with smoother texture and controlled afterfeel. Food teams therefore have room to test several protein routes before scale-up.
How is China scaling market demand?
10.7% CAGR, driven by dairy output and a large processed-food production base.
China combines large-scale dairy production with a broad food-process system that creates multiple routes for milk and plant protein use. The National Bureau of Statistics reported in February 2026 that milk output reached 40.91 million tons in 2025. China is projected to record a 10.7% CAGR by 2036 as drink and dairy-alternative food teams increase their focus on protein systems with milder taste and more controlled texture. This mix favors proteins that keep drinks mild and smooth.
What underpins Germany’s growth?
9.0% CAGR, shaped by convenience-food output and recipe updates across established food categories.
Germany’s prepared-food base creates recurring recipe work across meals, bakery products, sauces, and dairy-linked uses. Destatis reported in January 2026 that Germany produced 1.7 million tonnes of ready meals in 2024. Germany is forecast to record a 9.0% CAGR from 2026 to 2036 as food makers use functional proteins to raise nutrition value while maintaining the texture expected in established product formats. Recipe work often starts with familiar foods where texture standards are already clear.
How does Japan perform?
9.6% CAGR, supported by dairy supply and compact nutrition formats that reward smooth texture.
Japan’s food teams work in a market where taste and controlled viscosity matter in drinks and nutrition products. A USDA Foreign Agricultural Service report published on April 1, 2026 estimated Japan’s food processing output at USD 174 billion in 2025. Japan is anticipated to post a 9.6% CAGR through 2036 as food teams favor protein systems with mild flavor and reliable dispersion.
What supports the France outlook?
9.2% CAGR, supported by a large dairy base and continued recipe updates of desserts and drinks.
France has a deep dairy-process base that supports protein use across yoghurt, desserts, drinks, and hybrid recipes. Agreste reported on January 22, 2026 that 23.1 billion litres of cow milk were collected in metropolitan France during 2024. France is estimated to record a 9.2% CAGR through 2036 as food teams use protein systems that preserve creaminess and body in enriched or lower-fat products. Dairy know-how gives local teams a strong base for texture-led protein work.
Who leads the Clean Mouthfeel Protein Alternatives Market?
Kerry Group and Arla Foods Ingredients cover dairy and functional protein needs, while Ingredion and Roquette strengthen plant-protein taste options.
Kerry addresses dairy and plant-protein formulation needs through taste, nutrition, protein, and functional ingredient solutions used across beverages and other nutrition applications. Ingredion supplies VITESSENCE® pea protein isolates that support protein enrichment while providing smooth texture, solubility, and dispersibility. Arla Foods Ingredients supplies whey-protein solutions for high-protein dairy applications, including its patented microparticulated Nutrilac® ProteinBoost range, which is designed to maintain taste, texture, and stability as protein levels increase.
Roquette competes through its NUTRALYS® pea protein portfolio, including ingredients designed to deliver cleaner and more neutral taste profiles in plant-based formulations. Cargill offers pea proteins for dairy alternatives and hybrid dairy formulations alongside functional systems that support texture, stabilization, thickening, and emulsification. IFF offers SUPRO® soy proteins and TRUPRO® pea proteins together with texturant solutions that can manage viscosity, suspension, texture, and mouthfeel across food and beverage applications.
These suppliers therefore provide different routes for balancing protein enrichment with taste, texture, and processing requirements. Competitive differentiation is expected to center on sensory performance, formulation stability, application support, and the ability to reach protein targets while maintaining the desired finished-product texture. Supplier selection can vary according to the protein source, processing conditions, target nutrition profile, and sensory requirements of each application.
Which companies are the key providers?
Kerry Group and Ingredion are key providers. Arla Foods Ingredients and Roquette are also profiled. Cargill and IFF complete the company set.
- Kerry Group
- Ingredion
- Arla Foods Ingredients
- Roquette
- Cargill
- IFF
Bibliography
- Zeballos, E., & Sinclair, W. (2026, June 11). Total U.S. food spending reached $2.51 trillion in 2025. U.S. Department of Agriculture, Economic Research Service.
- National Bureau of Statistics of China. (2026, February 28). Statistical communiqué of the People’s Republic of China on the 2025 national economic and social development.
- Statistisches Bundesamt (Destatis). (2026, January 14). Produktion von Fertiggerichten binnen fünf Jahren mengenmäßig um 25,6 % gestiegen [Production of ready meals increased by 25.6% in volume within five years].
- U.S. Department of Agriculture, Foreign Agricultural Service. (2026, April 1). Food processing ingredients annual (Report No. JA2026-0012).
- Calvino, A. (2026, March 10). Enquête annuelle laitière 2024 [Corrected version]. Agreste.
- Roquette. (2026, February 23). Launch of breakthrough clean-tasting pea protein isolate.
- Arla Foods Ingredients. (2025, November 11). Arla Foods Ingredients showcases innovation expertise with new high-protein concepts.
- Cargill. (2025, March 4). Cargill showcases full range of innovative food solutions at AAHAR 2025.
- Kerry Group. (2026, March 19). Kerry publishes 2025 Annual Report: A year defined by impact, innovation and purpose.
This Report Answers
- The report explains where clean mouthfeel protein alternatives are used across Protein Platform and Functional Role. It also covers Application and Format together with regional demand.
- Segment analysis identifies the leading subsegments and the functional reasons food teams prioritize specific protein platforms, texture roles, applications, and delivery formats.
- Country analysis examines China, Japan, the USA, France, and Germany together with the food-processing, dairy, nutrition, and recipe-development conditions supporting demand.
- Competitive analysis reviews current providers across whey and milk proteins, plant proteins, functional protein systems, microparticulated proteins, and texture-support solutions.
- Application analysis assesses how creaminess, smoothness, lubrication, emulsion stability, solubility, and afterfeel influence protein selection. It also considers process tolerance and sensory performance in finished foods and drinks.
What does the Clean Mouthfeel Protein Alternatives Market cover?
Whey, milk, plant, egg, and fermented or novel protein systems used to improve mouthfeel in food and drinks.
The market covers protein ingredients and protein systems chosen to improve creaminess, smooth flow, and emulsion stability while adding protein. The focus remains on how the finished food feels and tastes.
The boundary is narrower than the full protein ingredients category. General nutrition proteins are included only when their process or functional behavior directly improves mouthfeel. This keeps the market tied to texture-led protein use in finished food.
What is included in the scope?
Clean mouthfeel protein systems used in dairy, dairy alternatives, drinks, sauces, bakery, and nutrition foods.
Included protein types are whey, milk, plant, egg, and fermented or novel proteins. The main roles are creaminess, fat mimicking, mouthfeel support, emulsion stability, and calorie reduction. Nearby ingredient categories are discussed only when protein function directly affects taste or texture.
What is excluded from the scope?
General protein ingredients used only for nutrition are covered in broader protein categories. Standalone texture systems remain outside this market scope.
The scope centers on proteins selected for texture or mouthfeel results in finished food and drink recipes. Flavor systems and non-protein texturants remain adjacent categories when protein function is absent from the recipe role.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report’s scope and coverage?
Clean Mouthfeel Protein Alternatives Breakdown By Protein Platform, Functional Role, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion in 2026 to USD billion by 2036 at a CAGR. |
| Market Definition | Protein ingredients and protein-centered systems selected to improve creaminess, lubrication, smoothness, emulsion stability, or fat-like body in finished food and drink applications. |
| Protein Platform | Whey proteins; Milk proteins; Plant proteins; Egg proteins; Fermented / novel proteins. |
| Functional Role | Lubrication / creaminess; Fat mimicking; Mouthfeel enhancement; Emulsion stabilization; Calorie reduction. |
| Application | Dairy / alternatives; Beverages; Sauces / dressings; Bakery; Nutrition foods. |
| Format | Powder concentrate; Microparticulated protein; Hydrolyzed protein; Protein-polysaccharide system; Custom functional blend. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa. |
| Countries Covered | United States; China; Germany; Japan; France. |
| Key Companies Profiled | Kerry Group; Ingredion; Arla Foods Ingredients; Roquette; Cargill; IFF. |
| Forecast Period | 2026 to 2036. |
| Approach | Market assessment using end-use demand, protein format, country growth, recipe requirements, supplier activity, specialty-protein use, official country data, active company portfolios, and first-party product records. |
How is the market segmented?
-
By Protein Platform
- Whey Proteins
- Milk Proteins
- Plant Proteins
- Egg Proteins
- Fermented / Novel Proteins
-
By Functional Role
- Lubrication / Creaminess
- Fat Mimicking
- Mouthfeel Enhancement
- Emulsion Stabilization
- Calorie Reduction
-
By Application
- Dairy / Alternatives
- Beverages
- Sauces / Dressings
- Bakery
- Nutrition Foods
-
By Format
- Powder Concentrate
- Microparticulated Protein
- Hydrolyzed Protein
- Protein-Polysaccharide System
- Custom Functional Blend
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa