- Market Value (2025): USD 6.15 Bn
- Estimated Value (2026): USD 6.74 Bn
- Forecast Value (2036): USD 16.9 Bn
- CAGR (2026-2036): 9.6%
What is the SSD Controllers Market forecast to be worth by 2036?
USD 6.7 billion in 2026 to USD 16.9 billion by 2036, at a 9.6% CAGR.
- The SSD Controllers Market reached USD 6.15 billion in 2025, with controller spending tied to NAND-based drives for business systems and personal computers.
- The market is projected to reach from USD 6.74 billion in 2026 to USD 16.9 billion in 2036 as controller specifications change alongside NAND flash and host interface generations.
- A 9.6% CAGR covers the 2026 to 2036 forecast period, with data center systems placing particular pressure on predictable throughput and power consumption.
| Year | Basis | Market Value (USD Billion) |
|---|---|---|
| 2025 | Actual | 6.15 |
| 2026 | Estimate | 6.74 |
| 2036 | Forecast | 16.9 |
| CAGR 2026 to 2036 | Forecast period | 9.6% |
Source: Fact.MR analysis. Updated Nov 11, 2026
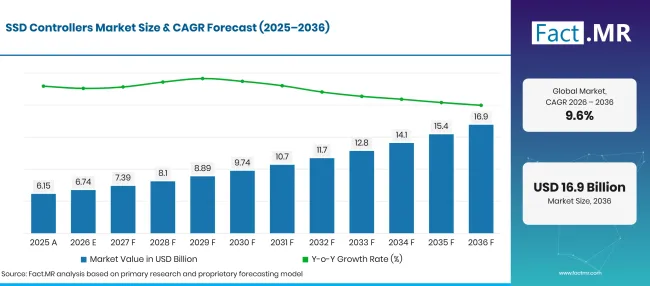
Ssd Controllers Market Forecast Global 1 | Source: Fact.MR
What are the defining numbers behind SSD Controllers Market growth?
Between 2026 and 2036, market value is projected to rise by USD 10.2 billion.
- Demand Drivers in the Market
- Data center storage teams need controllers with stable latency during mixed read and write loads. Silicon Motion introduced its SM8388 eight-channel PCIe Gen5 enterprise controller in November 2025 for high-capacity QLC drives and nearline storage, indicating the value of power-aware architecture in server storage.
- Client SSD manufacturers assess controller power consumption because thin laptops have limited heat budgets.
- Semiconductor purchasing teams monitor the NAND supply chain when qualifying a controller. The Semiconductor Industry Association reported USD 791.7 billion in global semiconductor sales for 2025, up 25.6% from 2024.
- Enterprise buyers review security features and steady write behavior before accepting a drive design. Micron introduced a new data center SSD portfolio in July 2025 that included PCIe Gen6 and high-capacity products, showing how faster interfaces increase the requirements placed on storage electronics.
- Key Segments Analyzed
- By Types: Controllers classified by supported NAND configuration are estimated to have a 42.5% Multi Level Cell share in 2026.
- By Application: Data Center is estimated to represent 36.0% of 2026 revenue. Enterprise teams compare controllers against latency targets and endurance requirements before selecting a drive platform.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “The next phase of SSD controller competition will depend less on headline interface speed and more on how consistently firmware manages real NAND behavior under sustained workloads. Enterprise buyers are increasingly sensitive to latency stability, power draw and qualification time. Vendors that simplify NAND validation while maintaining dependable error recovery can shorten design cycles for SSD manufacturers.”
- Strategic Implications
- Controller designers can validate firmware against the actual NAND packages and host interfaces selected by SSD manufacturers. Qualification evidence becomes especially useful when firmware must manage frequent background maintenance.
- NAND manufacturers need early coordination with controller partners on memory characterization before a drive enters system testing. Interface timing and error recovery behavior can directly influence server-side performance.
- Enterprise SSD manufacturers benefit from separating boot-drive requirements from heavy-write applications because each workload places different demands on controller architecture and firmware.
- Server operators can test steady-state performance under realistic workloads and document power behavior, rather than relying on peak bandwidth as the main indicator of production suitability.
Germany is forecast to achieve 11.3% CAGR on enterprise digital infrastructure demand. Brazil follows at 10.3% as data center investment broadens. The USA is estimated at 9.3% alongside established server design activity. The UK is forecast at 8.3% amid digital infrastructure investment.
How does the SSD Controllers Market break down by segment?
Multi Level Cell holds 42.5% of Types; Data Center accounts for 36.0% of Application in 2026.
Which controller Types segment holds the largest share?
Multi Level Cell represents 42.5% of 2026 value.
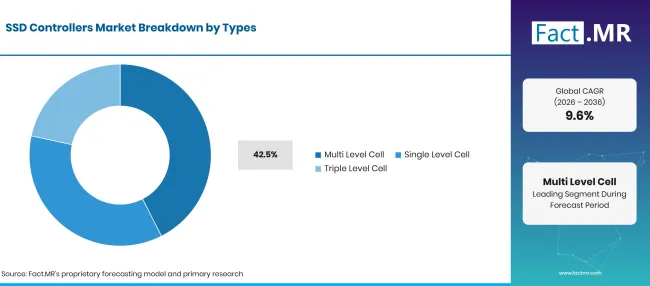
Ssd Controllers Market Breakdown Types | Source: Fact.MR
| Types | Share (2026) |
|---|---|
| Multi Level Cell (Leading segment) | 42.5% |
| Other types combined | 57.5% |
| Total | 100.0% |
Source: Fact.MR analysis. Updated Nov 11, 2026
Multi Level Cell (MLC) NAND stores two bits per cell, compared with one in Single Level Cell (SLC), three in Triple Level Cell (TLC), and four in Quad Level Cell (QLC) NAND. These are NAND memory classifications, not exclusive controller hardware architectures. These designs place different demands on the controller because stored information becomes harder to read reliably as memory cells age. Drive manufacturers compare error correction, wear management and firmware compatibility before qualifying a controller for a particular NAND package.
What leads the Application segment?
Data Center accounts for 36.0% of 2026 market value.
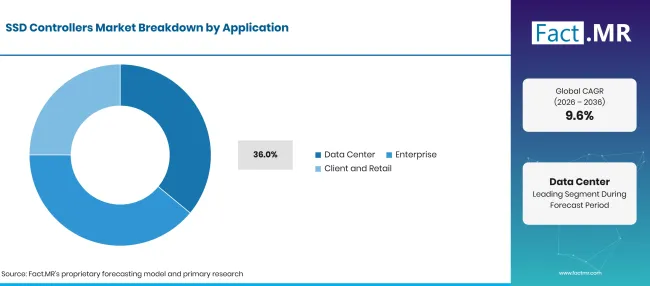
Ssd Controllers Market Breakdown Application | Source: Fact.MR
| Application | Share (2026) |
|---|---|
| Data Center (Leading segment) | 36.0% |
| Other applications combined | 64.0% |
| Total | 100.0% |
Source: Fact.MR analysis. Updated Nov 11, 2026
Data center operators need storage that responds consistently while servers handle sustained reading and writing. Controller makers must balance response time with error recovery and power consumption, since an improvement in peak speed has limited value if performance changes sharply under regular workloads. Enterprise drives also provide health-monitoring information that helps teams plan replacements. Consumer SSDs place more emphasis on price and laptop power use, while smaller business systems select features according to their own applications.
What is accelerating SSD Controllers Market adoption, and what is holding it back?
Data center qualification and new NAND generations support controller design work; firmware validation and memory supply constraints lengthen product cycles.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Enterprise SSD qualification | +1.4% | North America, East Asia | Medium term |
| PCIe interface migration | +1.1% | Global | Medium term |
| Higher-capacity NAND designs | +0.9% | East Asia, North America | Long term |
| Client power requirements | +0.7% | Global | Short term |
| Cloud storage replacement | +0.5% | Europe, Americas | Long term |
Source: Fact.MR analysis. Updated Nov 11, 2026
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Enterprise boot-drive controllers | +0.8% | North America, Europe | Medium term |
| Efficient nearline SSDs | +0.7% | Global | Long term |
| Portable SSD controllers | +0.5% | Global | Short term |
| Firmware verification services | +0.4% | East Asia, North America | Medium term |
Source: Fact.MR analysis. Updated Nov 11, 2026
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| NAND compatibility testing | -0.7% | Global | Short term |
| Thermal and power limits | -0.6% | Global | Medium term |
| Long enterprise design cycles | -0.5% | North America, East Asia | Medium term |
| Memory supply and pricing | -0.4% | Global | Long term |
Source: Fact.MR analysis. Updated Nov 11, 2026
Which countries are scaling the SSD Controllers Market through 2036?
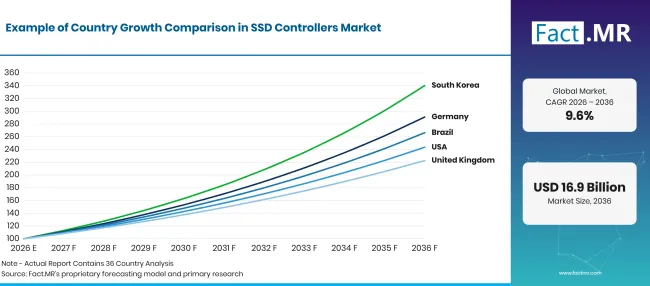
Ssd Controllers Market Growth Index | Source: Fact.MR
| Country | CAGR (2026 to 2036) |
|---|---|
| Germany | 11.3% |
| Brazil | 10.3% |
| USA | 9.3% |
| UK | 8.3% |
| Japan | 7.4% |
Source: Fact.MR analysis. Updated Nov 11, 2026
Why is Germany gaining ground in SSD controller demand?
11.3% CAGR, linked to industrial computing and enterprise storage requirements.
Germany’s industrial computers and business servers require SSD controllers that can work reliably with selected NAND packages. Eurostat’s enterprise cloud computing dataset records that 53.91% of German enterprises used paid cloud computing services in 2025. Enterprise storage suppliers must plan firmware support alongside component availability.
How is data center expansion influencing Brazil’s controller market?
10.3% CAGR, linked to new data center systems and local digital services.
Brazil’s data center building activity gives server makers a wider setting in which to offer enterprise SSD systems. In November 2025, BNDES approved R$ 200 million for equipment purchases by Scala Data Centers. Power availability and construction schedules affect when new server rooms begin purchasing storage.
What is driving SSD controller adoption in the USA?
9.3% CAGR, connected to server engineering and controller qualification.
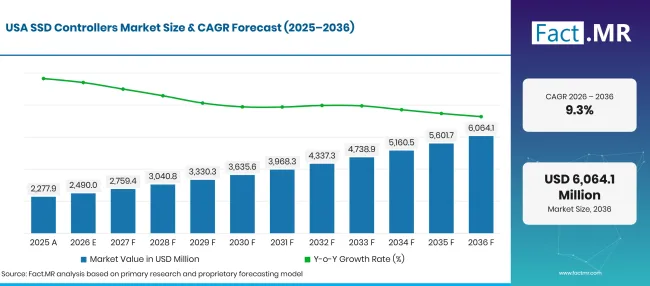
Ssd Controllers Market Forecast Usa | Source: Fact.MR
Server design activity and large cloud fleets shape SSD controller requirements in the USA. The Semiconductor Industry Association reported that the American semiconductor industry spent USD 76.8 billion on research and development in 2025. Data center operators test drive performance over sustained workloads and check energy use across installed systems.
How is digital infrastructure investment shaping UK demand?
8.3% CAGR, tied to investment in digital infrastructure and storage services.
UK data center operators compare server and storage equipment within larger facility budgets. The Office for National Statistics estimated that annual digital infrastructure investment in the UK reached £11.2 billion in 2025. Power limits across server racks shape the choice of flash storage and controller design.
Where is Japan seeing stronger demand for advanced SSD controllers?
7.4% CAGR, shaped by NAND engineering and domestic enterprise equipment.
Japan has a developed NAND and SSD engineering base, giving controller suppliers close links to memory design and device testing. In July 2025, Kioxia announced a 245.76 TB enterprise NVMe SSD in its LC9 series. Engineers evaluate flash endurance and error recovery before selecting a controller for the final product.
Who leads the SSD Controllers Market?
SSD controller suppliers compete through different business models. Independent chip designers sell controller silicon and firmware tools to drive manufacturers, while memory producers develop controllers inside their own SSD products. The difference affects how a customer compares price and support. An independent vendor may offer a controller that works with several NAND suppliers. A vertically integrated manufacturer can tune the controller and flash together for a finished drive. Both approaches demand careful device testing before high-volume production.
Phison Electronics Corporation serves SSD manufacturers across consumer and enterprise designs. At CES in January 2025, Phison introduced its PS5028-E28 PCIe Gen5 controller and described support for faster client storage. Silicon Motion Technology Corporation develops controller families for personal computers and enterprise applications. Its May 2025 announcement covered the SM2504XT client SSD controller and the SM2324 portable storage controller.
Marvell Technology, Inc. has a controller portfolio directed at enterprise and cloud storage. Its Bravera family includes functions for managing flash errors and maintaining steady drive response. In 2026 Marvell announced the Bravera SC6 PCIe 6.0 controller, with sampling planned for the fourth quarter. InnoGrit Corporation and Maxio Technology (Hangzhou) Co., Ltd. Compete in specialist controller applications, where software support and compatibility testing influence design selection.
Which companies are the key providers?
Key companies include Phison Electronics Corporation; Silicon Motion Technology Corporation; Marvell Technology, Inc.; Samsung Electronics Co., Ltd.; SK hynix Inc.; Micron Technology, Inc.; Kioxia Corporation; Sandisk Corporation; InnoGrit Corporation; Maxio Technology (Hangzhou) Co., Ltd.
- Phison Electronics Corporation
- Silicon Motion Technology Corporation
- Marvell Technology, Inc.
- Samsung Electronics Co., Ltd.
- SK hynix Inc.
- Micron Technology, Inc.
- Kioxia Corporation
- Sandisk Corporation
- InnoGrit Corporation
- Maxio Technology (Hangzhou) Co., Ltd.
Bibliography
- Banco Nacional de Desenvolvimento Econômico e Social. (2025, November 27). BNDES aprova R$ 200 mi para Scala adquirir máquinas e equipamentos para data centers.
- Eurostat. (2026, February 3). 53% of EU enterprises used paid cloud services in 2025.
- Kioxia Corporation. (2025, July 22). KIOXIA announces industry’s first 245.76 TB NVMe SSD built for the demands of generative AI environments.
- Marvell Technology, Inc. (2026, August 4). Marvell advances AI memory infrastructure portfolio to accelerate agentic AI inference.
- Micron Technology, Inc. (2025, July 29). Micron unveils portfolio of industry-first SSDs to power the AI revolution.
- National Institute of Standards and Technology. (2026, June 30). Innovations in advanced processes and systems for semiconductor manufacturing.
- Office for National Statistics. (2026, August 24). Redefining investment in digital infrastructure in the UK: 2026.
- Phison Electronics Corporation. (2025, January 7). CES 2025: Phison unveils lightning-fast Gen5 storage, expanding suite of high-performance solutions.
- Silicon Motion Technology Corporation. (2025, May 15). Silicon Motion showcases next generation PCIe Gen5 SSD controller and USB4 portable SSD controller at Computex 2025.
- Silicon Motion Technology Corporation. (2025, November 14). Silicon Motion announces SM8388, the industry’s leading power-efficient PCIe Gen5 8-channel enterprise SSD controller, delivering 14.4GB/s performance at under 5W power for Nearline SSDs.
- U.S. Department of Commerce, National Institute of Standards and Technology. (2026, July 29). Department of Commerce announces letters of intent with 7 companies for $874 million to accelerate semiconductor R&D for the compute supply chain.
This Report Answers
- The report explains the technical distinction between controller designs for different NAND cell configurations and the implications for firmware testing.
- Segmentation compares data center systems with enterprise storage and client retail drives on their purchasing and operating requirements.
- Country analysis examines industrial computing in Germany, data center construction in Brazil and storage engineering activity across other profiled economies.
- Competitive analysis separates merchants selling controller silicon from NAND vendors developing controllers within finished SSD products.
- The outlook examines how thermal limits and compatibility testing affect commercial release schedules for different storage platforms.
What does the SSD Controllers Market cover?
The report covers controller semiconductors used in NAND-based solid-state drives. Controller functions include host communication, flash translation, error correction, wear management and data integrity support.
What is included in the scope?
Standalone controller chips and controller designs embedded within relevant SSD platforms are within the research boundary.
NAND cell categories are used to explain compatibility and system design. Data center demand is distinguished from other enterprise and client uses.
What is excluded from the scope?
Raw NAND flash revenue is excluded when it is unrelated to controller value.
Hard disk drive controllers and controllers for unrelated embedded memory formats are outside the market boundary. Whole SSD prices should not be treated as controller revenue without an explicit allocation method.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
Segmentation
What is the report’s scope and coverage?
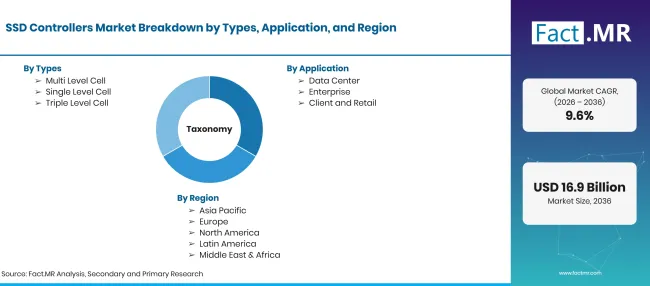
Ssd Controllers Market Taxonomy | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD Billion |
| Market Definition | Semiconductor controller chips and related controller design value used to manage NAND-based solid-state drives. |
| Types | Multi Level Cell; Single Level Cell; Triple Level Cell |
| Application | Data Center; Enterprise; Client and Retail |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | Germany; Brazil; USA; UK; Japan |
| Companies Profiled | Phison Electronics Corporation; Silicon Motion Technology Corporation; Marvell Technology, Inc.; Samsung Electronics Co., Ltd.; SK hynix Inc.; Micron Technology, Inc.; Kioxia Corporation; Sandisk Corporation; InnoGrit Corporation; Maxio Technology (Hangzhou) Co., Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Application-oriented analysis of SSD controller architectures, NAND compatibility, controller design activity and equipment demand. |
Source: Fact.MR analysis. Updated Nov 11, 2026
How is the market segmented?
-
By Types
- Multi Level Cell
- Single Level Cell
- Triple Level Cell
-
By Application
- Data Center
- Enterprise
- Client and Retail
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa
Frequently Asked Questions
How big is the SSD Controllers Market in 2026?
What is the CAGR of the SSD Controllers Market from 2026 to 2036?
Which controller type leads the SSD Controllers Market?
Which application leads the SSD Controllers Market?
Who are the leading companies in the SSD Controllers Market?
Who worked on this report


Preview the report firsthand - request a free sample
Free SampleGet the brochure for pricing and purchase details
Download PDF