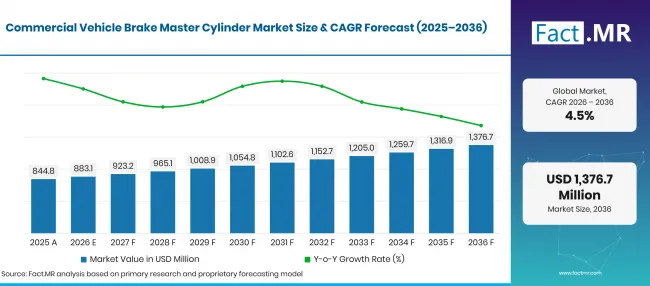
- Market Value (2025): USD 844.8 Mn
- Estimated Value (2026): USD 883.1 Mn
- Forecast Value (2036): USD 1376.7 Mn
- CAGR (2026-2036): 4.5%
What is the Commercial Vehicle Brake Master Cylinder Market forecast to be worth by 2036?
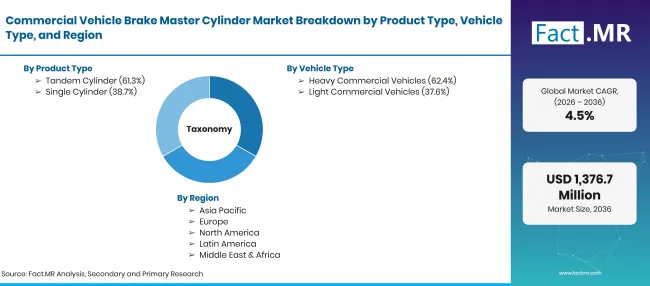
USD 883.1 million in 2026 to USD 1,376.7 million by 2036 at a 4.5% CAGR.
- As per Fact.MR analysis, the commercial vehicle brake master cylinder market crossed a valuation of USD 844.8 million in 2025.
- Demand is projected to increase from USD 883.1 million in 2026 to USD 1376.7 million by 2036.
- The market is expected to record a 4.5% CAGR from 2026 to 2036 as truck fleets replace hydraulic parts and truck makers refine brake actuation systems.
Commercial Vehicle Brake Master Cylinder Market Country Growth (4) | Source: Fact.MR
| Year | Basis | Market value (USD million) |
|---|---|---|
| 2025 | Actual | 844.8 |
| 2026 | Estimate | 883.1 |
| 2036 | Forecast | 1376.7 |
| CAGR, 2026 to 2036 | 4.5% | |
What are the defining numbers behind Commercial Vehicle Brake Master Cylinder Market growth?
USD 493.6 million absolute opportunity by 2036 led by Tandem Cylinder and Heavy Commercial Vehicles with OEM demand.
- Demand Drivers in the Market
- Heavy freight activity increases the use of truck braking systems and supports regular replacement of worn parts. In May 2026, the Bureau of Transportation Statistics reported that trucks moved USD 1.039 trillion of U.S.-Canada and U.S.-Mexico freight in 2025 [1].
- Truck manufacturers use compact master cylinders that fit newer chassis designs while providing steady hydraulic response under different vehicle loads.
- Replacement sales remain important for service workshops because leaks or internal bypass can keep a truck off the road until proper brake pressure is restored.
- Newer trucks are increasing the adoption of master cylinders designed to work with ABS and electronic brake controls while keeping the hydraulic system properly matched with the wider braking system.
- Key Segments Analyzed
- By Product Type: Tandem Cylinder will hold 61.3% share in 2026 since separate hydraulic circuits give commercial vehicles the braking redundancy required for safer operation.
- By Vehicle Type: Heavy Commercial Vehicles will account for 62.4% share in 2026 as higher axle loads and frequent braking place greater demand on durable hydraulic brake components.
- By Sales Channel: OEM will capture 58.9% share in 2026 because master cylinders are matched and tested with the complete braking system during vehicle development.
- By Material Type: Aluminum will represent 45.2% share in 2026 owing to its lower weight and resistance to corrosion in hydraulic brake assemblies.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Master cylinders convert pressure from the brake pedal into hydraulic pressure, making bore size and seal quality important to the overall braking system. Sales remain closely linked to fleet replacement cycles and approval from vehicle manufacturers.”
- Strategic Implications
- Consistent bore size and proper seal fit help component suppliers maintain reliable master-cylinder performance across different truck models. In November 2025, the Driver and Vehicle Standards Agency reported that brake systems and components accounted for 2.06% of HGVs inspected during April to June 2025 [2].
- Vehicle manufacturers can test master cylinders with brake boosters and ABS modulators before making changes to materials or hydraulic design. Testing these parts together helps reduce fitting and performance issues when the truck enters production.
- Aftermarket sales depend on having model-specific replacement units with clear information on bore size and mounting requirements. Accurate product details help workshops choose the correct part while reducing returns and service delays.
- Fleet maintenance staff can use fluid leaks and changes in pedal pressure as signs that the master cylinder requires inspection. Finding these issues early helps maintain steady braking response across the hydraulic system.
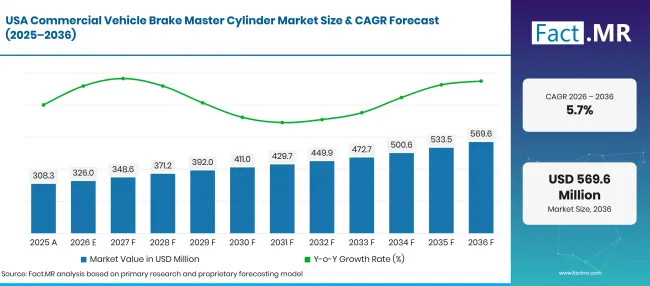
According to Fact.MR analysis, the United States leads with a 5.7% CAGR through 2036, supported by heavy truck use and steady sales to vehicle manufacturers and the replacement market. Germany follows at 5.4%, where a large truck fleet and strong road freight activity keep brake component sales active. Japan records 5.1% as regular vehicle replacement supports the adoption of new brake parts. The United Kingdom grows at 4.3%, backed by ongoing service work across HGV and LGV fleets, while Brazil reaches 3.9% as road freight creates regular aftermarket sales.
How does the Commercial Vehicle Brake Master Cylinder Market break down by segment?
Tandem Cylinder leads at 61.3%; Heavy Commercial Vehicles lead at 62.4%; OEM leads at 58.9%; Aluminum leads at 45.2%.
Which Product Type leads the market?
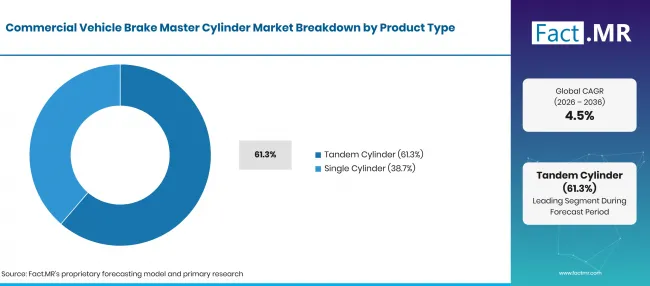
Tandem Cylinder holds 61.3% share in 2026.
Commercial Vehicle Brake Master Cylinder Market Country Growth (13) | Source: Fact.MR
Commercial Vehicle Brake Master Cylinder Market Breakdown by Product Type
| Product Type | Share (2026) |
|---|---|
| Tandem Cylinder (Leading Segment) | 61.3% |
| Other Segments Combined | 38.7% |
| Total | 100.0% |
Source: Fact.MR’s proprietary forecasting model and primary research.
Tandem cylinders lead with a 61.3% share in 2026, as their two brake circuits allow part of the braking system to continue working if one circuit develops a fault. This design is well suited to trucks that carry heavy loads and brake frequently during regular operations. Sales also benefit from the added braking support the design provides for demanding commercial vehicle use.
What leads the Vehicle Type segment?
Heavy Commercial Vehicles account for 62.4% share in 2026.
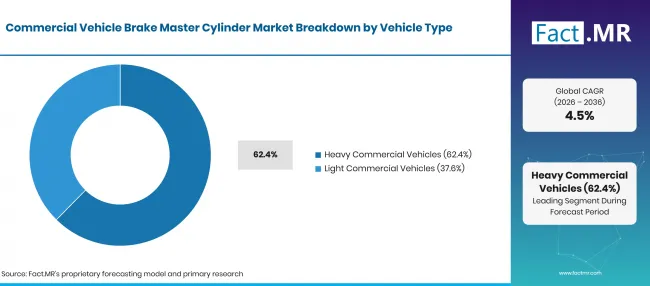
Commercial Vehicle Brake Master Cylinder Market Country Growth (15) | Source: Fact.MR
Commercial Vehicle Brake Master Cylinder Market Breakdown by Vehicle Type
| Vehicle Type | Share (2026) |
|---|---|
| Heavy Commercial Vehicles (Leading Segment) | 62.4% |
| Other Segments Combined | 37.6% |
| Total | 100.0% |
Source: Fact.MR’s proprietary forecasting model and primary research.
Long operating hours and heavier loads put more pressure on braking parts in heavy commercial vehicles. This makes the segment the largest, with a 62.4% share in 2026. Vehicle activity also remains strong in major truck markets. Regular use of these vehicles creates steady sales opportunities for master cylinders used in new trucks and replacement work.
How does Sales Channel shape demand?
OEM holds 58.9% share in 2026.
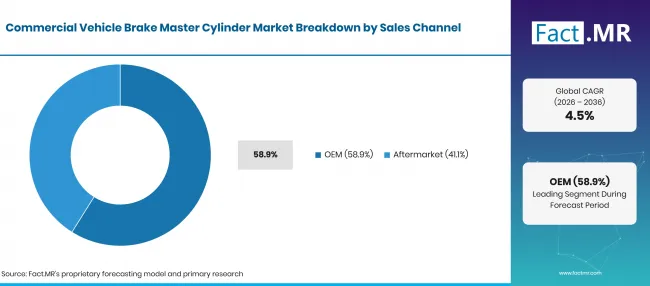
Commercial Vehicle Brake Master Cylinder Market Country Growth (14) | Source: Fact.MR
Commercial Vehicle Brake Master Cylinder Market Breakdown by Sales Channel
| Sales Channel | Share (2026) |
|---|---|
| OEM (Leading Segment) | 58.9% |
| Other Segments Combined | 41.1% |
| Total | 100.0% |
Source: Fact.MR’s proprietary forecasting model and primary research.
A master cylinder becomes part of a truck well before the vehicle reaches the production line. During development, manufacturers choose the bore size and mounting layout to match the complete brake system, followed by vehicle testing to confirm its performance. These early design decisions give OEMs a 58.9% share in 2026. Once a cylinder is approved for a truck platform, the same specification generally continues with regular vehicle production.
What supports Aluminum within Material Type?
Aluminum captures 45.2% share in 2026.
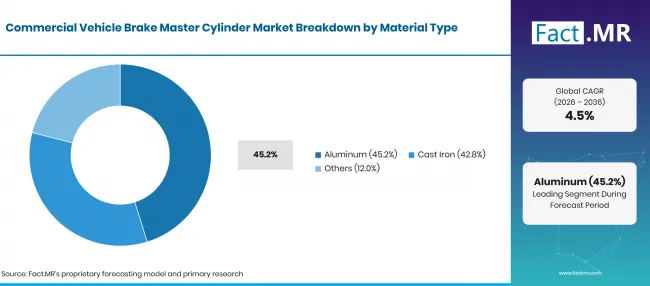
Commercial Vehicle Brake Master Cylinder Market Country Growth (12) | Source: Fact.MR
Commercial Vehicle Brake Master Cylinder Market Breakdown by Material Type
| Material Type | Share (2026) |
|---|---|
| Aluminum (Leading Segment) | 45.2% |
| Other Segments Combined | 54.8% |
| Total | 100.0% |
Source: Fact.MR’s proprietary forecasting model and primary research.
Reducing vehicle weight matters even at the component level, which gives aluminum an advantage in truck master cylinders. The material also handles regular exposure to brake fluid and road conditions without the same concern around rust. According to Fact.MR analysis, the aluminum segment represents 45.2% of the market in 2026. Its use varies by truck design, since manufacturers still have to meet the strength and operating requirements set for the original braking system.
What is accelerating Commercial Vehicle Brake Master Cylinder Market adoption, and what is holding it back?
Regular truck use and replacement of worn brake parts keep master-cylinder sales active across commercial fleets. Growth can slow when truck production and fleet purchases weaken, while wider use of brake-by-wire systems may reduce the role of traditional hydraulic master cylinders over time.
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Commercial fleet replacement | +1.0% | Global | Short term (<= 2 years) |
| Heavy commercial vehicle duty cycles | +0.8% | North America, Europe, East Asia | Medium term (2-4 years) |
| OEM brake-system integration | +0.7% | Germany, Japan, USA | Long term (>= 4 years) |
| Road freight activity | +0.6% | USA, Germany, Brazil, UK | Medium term (2-4 years) |
| Aftermarket repair coverage | +0.5% | Global | Short term (<= 2 years) |
Opportunity Impact Analysis
| Opportunity | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Compact integrated hydraulic modules | +0.7% | Europe, East Asia, North America | Long term (>= 4 years) |
| Lightweight aluminum housings | +0.5% | Global | Medium term (2-4 years) |
| Aftermarket application expansion | +0.5% | Brazil, USA, UK | Short term (<= 2 years) |
| Brake-by-wire compatible hydraulics | +0.4% | Germany, Japan, USA | Long term (>= 4 years) |
Restraints Impact Analysis
| Restraint | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Brake-by-wire architecture shift | -0.7% | Europe, East Asia, North America | Long term (>= 4 years) |
| Commercial vehicle production swings | -0.5% | Brazil, UK, Japan | Short term (<= 2 years) |
| Fitment complexity in aftermarket | -0.4% | Global | Medium term (2-4 years) |
| Raw-material and machining cost pressure | -0.3% | Global | Short term (<= 2 years) |
Which countries are scaling the Commercial Vehicle Brake Master Cylinder Market through 2036?
- The United States is expected to keep a 0.3-point lead over Germany as high truck utilization supports both OEM and replacement demand.
- Germany is projected to remain 0.3 points ahead of Japan because its truck fleet and road-freight network sustain brake-system service activity.
- Japan is anticipated to stay 0.8 points ahead of the United Kingdom as commercial-vehicle renewal keeps hydraulic brake service active.
- The United Kingdom is estimated to remain 0.4 points ahead of Brazil because freight fleets continue to create replacement work for hydraulic brake parts.
- Brazil is forecast to close the five-country range while a large road-freight base keeps workshop demand active across older trucks.
Comparable CAGRs create different entry conditions because fleet age and freight intensity vary by country. Full coverage includes North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; and Middle East & Africa.
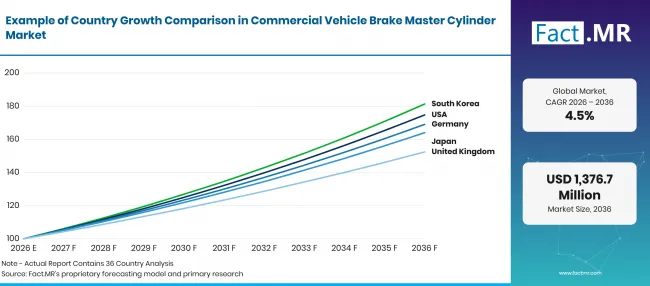
Commercial Vehicle Brake Master Cylinder Market Country Growth (6) | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| United States | 5.7% |
| Germany | 5.4% |
| Japan | 5.1% |
| United Kingdom | 4.3% |
| Brazil | 3.9% |
What supports United States adoption?
5.7% CAGR, led by high commercial-vehicle inspection activity.
Commercial Vehicle Brake Master Cylinder Market Country Growth (5) | Source: Fact.MR
Long freight routes keep U.S. commercial trucks on the road for extended periods, making regular brake checks an important part of fleet maintenance. In August 2026, the Federal Motor Carrier Safety Administration reported 3,131,746 federal and state roadside inspections in FY2025 [4]. This level of inspection helps fleet operators identify brake wear during routine use and replace affected parts before trucks return to regular service.
What supports Germany's growth?
5.4% CAGR, backed by a large truck fleet and established brake engineering.
Germany’s large truck fleet creates regular business for brake parts used in both vehicle production and repair work. Destatis reported in March 2026 that the country had 3.8277 million trucks in its 2025 vehicle stock [5]. With road freight active across the country, these vehicles require ongoing servicing as they remain in use, giving master-cylinder suppliers a broad customer base across new and existing trucks.
How is Japan developing demand?
5.1% CAGR, shaped by commercial-vehicle safety and service needs.
Brake parts used in Japanese trucks go through careful fitting and testing to match the requirements of each vehicle model. MLIT data show that cargo-vehicle registrations reached 25,816 in December 2025, up 19.2% from a year earlier [3]. As more cargo vehicles enter regular use, service workshops handle a wider base of trucks that need routine brake maintenance and replacement parts matched to individual models.
What is supporting United Kingdom adoption?
4.3% CAGR, driven by active HGV freight operations and replacement work.
Heavy goods vehicles handle a large amount of freight across the United Kingdom, keeping brake systems in regular use on domestic routes. The Department for Transport reported in May 2026 that GB-registered HGVs carried 1.53 billion tonnes of goods during 2025 [6]. Regular fleet servicing creates ongoing replacement sales for hydraulic brake parts as components wear with use. Planned maintenance also helps workshops spot fluid leaks and pressure changes before they affect normal vehicle operation.
How does Brazil perform?
3.9% CAGR, shaped by a large registered road-freight vehicle base.
Road transport plays a major role in moving freight across Brazil, creating steady repair work for commercial vehicles. ANTT reported in May 2026 that 2,846,202 vehicles were linked to transporters with active, pending, or suspended RNTRC registrations in December 2025 [7]. A fleet of this size keeps workshops busy with brake maintenance and gives replacement suppliers regular sales opportunities for master cylinders and related parts.
Who leads the Commercial Vehicle Brake Master Cylinder Market?
Brake suppliers compete through product fit, braking performance, and their ability to meet vehicle manufacturers’ requirements. ZF Friedrichshafen, and Bosch bring experience across braking and actuation systems for commercial and light-commercial vehicles.
AISIN, Astemo, HL Mando Corporation, and ADVICS have a strong presence across Asian vehicle programs and add wider brake-system capabilities. Product coverage across different vehicle models also remains important, particularly for suppliers serving both new vehicle production and replacement sales. Brake technology is also moving toward systems that combine more functions in a smaller unit.
Which companies are the key providers?
Key companies include Robert Bosch GmbH; ZF Friedrichshafen; AISIN Corporation; Astemo Ltd.; HL Mando Corporation; and ADVICS.
- Robert Bosch GmbH
- ZF Friedrichshafen
- AISIN Corporation
- Astemo Ltd.
- HL Mando Corporation
- ADVICS
Bibliography
- [1] Bureau of Transportation Statistics. (2026, May 15). Transborder Freight Data Annual Report: 2025.
- [2] Driver and Vehicle Standards Agency. (2025, November 18). Top 10 prohibition defects as a percentage of all HGV vehicles inspected at roadside and operators' premises [Data set].
- [3] Ministry of Land, Infrastructure, Transport and Tourism, Japan. (2026). [Correction table: Newly registered motor vehicles].
- [4] Federal Motor Carrier Safety Administration. (2026, August 28). Roadside Inspection Activity: FY 2025 [Data set].
- [5] Statistisches Bundesamt (Destatis). (2026, March 23). Bestand an Kraftfahrzeugen und Schienenfahrzeugen für die Jahre 2021 bis 2025 [Stock of motor vehicles and rail vehicles for 2021 to 2025].
- [6] Department for Transport. (2026, May 27). Domestic road freight statistics, United Kingdom: 2025.
- [7] Agência Nacional de Transportes Terrestres. (2026). Anuário TRC 2025.
- [8] Continental AG. (2025, April 15). Safe, Exciting, Autonomous: Solutions for Automated Driving and Light Projection Debut at Auto Shanghai.
This Report Answers
- The report explains how commercial vehicle brake master cylinders are assessed by product type, vehicle type, sales channel, and material type.
- Segment analysis identifies the leading subsegment in each category and explains the operating factors behind its 2026 market share.
- Country analysis compares the United States, Germany, Japan, the United Kingdom, and Brazil through fleet activity, road freight, vehicle servicing, and replacement demand.
- Competitive analysis reviews active brake-system suppliers serving commercial-vehicle manufacturers and the replacement market.
- Technology analysis examines how hydraulic design, material choice, brake-system integration, and brake-by-wire development affect master-cylinder demand and future product use.
What does the Commercial Vehicle Brake Master Cylinder Market cover?
The market covers brake master cylinders for light and heavy trucks. It includes tandem and single-cylinder designs sold through OEM and replacement channels. Aluminum, cast-iron and other housings are included when the unit generates hydraulic pressure for the service brake circuit.
What is included in the scope?
The scope includes standalone hydraulic master cylinders and master-cylinder functions inside wider actuation modules. Reservoir interfaces, pistons and seals are included when part of the finished unit. Demand is tracked through OEM and aftermarket channels across the listed commercial-vehicle classes.
What is excluded from the scope?
The scope excludes pads, rotors, calipers, wheel cylinders, hoses and brake fluid sold separately. Fully dry electro-mechanical systems without hydraulic pressure generation are excluded. Passenger-car-only, motorcycle and off-highway brake cylinders also fall outside the revenue boundary.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report’s scope and coverage?
Commercial Vehicle Brake Master Cylinder Market Country Growth (11) | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD million in 2026 to USD million by 2036 at a CAGR |
| Market Definition | Brake master cylinders used in commercial vehicles to convert pedal or actuator input into hydraulic brake pressure. The scope covers standalone and integrated hydraulic master-cylinder functions sold through OEM and replacement channels. |
| Product Type | Tandem Cylinder; Single Cylinder |
| Vehicle Type | Heavy Commercial Vehicles; Light Commercial Vehicles |
| Sales Channel | OEM; Aftermarket |
| Material Type | Aluminum; Cast Iron; Others |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | United States; Germany; Japan; United Kingdom; Brazil |
| Key Companies Profiled | Robert Bosch GmbH; ZF Friedrichshafen; AISIN Corporation; Astemo Ltd.; HL Mando Corporation; ADVICS |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up assessment using commercial-vehicle fleet activity, brake-system architecture, replacement cycles, channel mix, material mix and verified company participation. |
How is the market segmented?
-
By Product Type
- Tandem Cylinder
- Single Cylinder
-
By Vehicle Type
- Heavy Commercial Vehicles
- Light Commercial Vehicles
-
By Sales Channel
- OEM
- Aftermarket
-
By Material Type
- Aluminum
- Cast Iron
- Others
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa