- Market Value (2025): USD 2.8 Bn
- Estimated Value (2026): USD 2.9 Bn
- Forecast Value (2036): USD 4.4 Bn
- CAGR (2026-2036): 4.3%
What is the Nasal Splints Market forecast to be worth by 2036?
USD 2.9 Billion in 2026 to USD 4.4 Billion by 2036 at a 4.3% CAGR.
- The Nasal Splints Market reached USD 2.8 Billion in 2025.
- Demand is projected to increase from USD 2.9 Billion in 2026 to USD 4.4 Billion by 2036.
- The market is forecast to record a 4.3% CAGR from 2026 to 2036 as hospitals and ENT clinics standardize postoperative nasal support products.
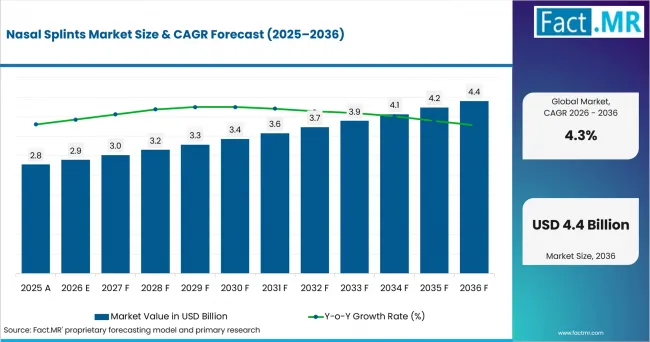
Nasal Splints Market Value Analysis | Source: Fact.MR
What are the defining numbers behind Nasal Splints Market growth?
An absolute opportunity of USD 1.5 Billion is expected between 2026 and 2036.
- Demand Drivers in the Market
- Intranasal septal splints may be used after septal surgery to support septal stability and help reduce postoperative adhesions.
- Hospitals need predictable packs for repeat nasal procedures. NHS England Digital recorded 22.6 million Finished Consultant Episodes in 2024–25, highlighting the scale of admitted-patient activity relevant to hospital consumables planning.
- Specialty clinics need external stabilization after aesthetic nasal surgery, linking nasal splint use with rhinoplasty recovery and related cosmetic procedure workflows.
- Private and public care channels need low-cost devices that fit operating-room routines.
- Key Segments Analyzed
- By Mechanism: Internal is expected to hold 65.40% share in 2026 because septal support splints are used directly after corrective nasal procedures.
- By Product: Malleable is projected to account for 45.20% share in 2026 owing to bendable external and internal formats that support surgeon adjustment.
- By Material: Biodegradable is anticipated to capture 68.90% share in 2026 as clinicians favor materials that reduce removal complexity in selected postoperative settings.
- By End Use: Hospitals are estimated to represent 33.80% share in 2026 due to procedure volume, sterilization control, and repeat ordering by ENT departments.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Nasal splints are selected on handling, patient comfort, and predictable postoperative support. The market is expected to expand steadily because hospitals and clinics want small devices that fit established nasal surgery pathways. Suppliers that combine sterile pack reliability, clear sizing, and material documentation are better placed in repeat purchasing discussions.”
- Strategic Implications
- Manufacturers should document material composition and sterilization status clearly so hospital buyers can compare silicone, aluminum, polymer, and biodegradable options quickly.
- Distributors should keep procedure-specific pack sizes available because septoplasty, rhinoplasty, and trauma repair often require fast replacement stock.
- Hospitals should separate internal septal support from external cosmetic stabilization during product selection so clinical teams match the splint to the recovery need.
- Specialty clinics should train staff on removal timing and patient instructions because comfort after discharge affects repeat surgeon preference.
Germany is projected to record 4.7% CAGR through 2036 because hospital ENT departments maintain structured postoperative pathways. Brazil is expected to post 4.3% CAGR as specialist access programs and private-plan coverage support elective procedure volumes. The USA is forecast to reach 3.9% CAGR through FDA classification clarity and outpatient cost transparency. The U.K. is anticipated to advance at 3.5% CAGR with NHS procedure volume and specialty clinic use. Japan is estimated to register 3.1% CAGR as aging care needs and hospital-based ENT capacity support cautious adoption.
How does the Nasal Splints Market break down by segment?
Internal leads Mechanism at 65.40% share in 2026; while Malleable leads Product at 45.20% share.
Which Mechanism dominates?
Internal is expected to hold 65.40% share in 2026.
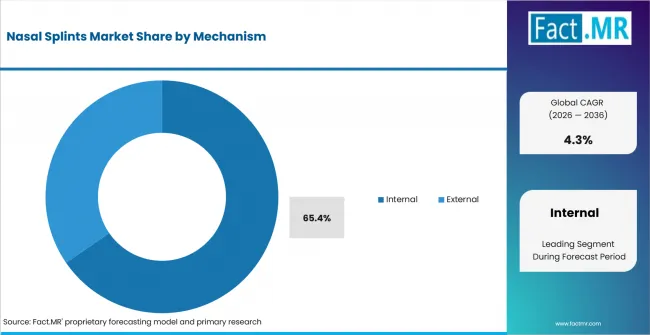
Nasal Splints Market Analysis By Mechanism | Source: Fact.MR
Internal splints lead because septal support is central to many nasal procedures. They help keep the septum stable after correction and protect healing tissue from adhesion during early recovery.
FDA classifies intranasal septal splints under a defined U.S. regulatory category: product code LYA, Class I, under 21 CFR 874.4780. Medtronic plc Xomed listings under product code LYA also confirm established device participation in the category.
What leads the Product segment?
Malleable is projected to account for 45.20% share in 2026.
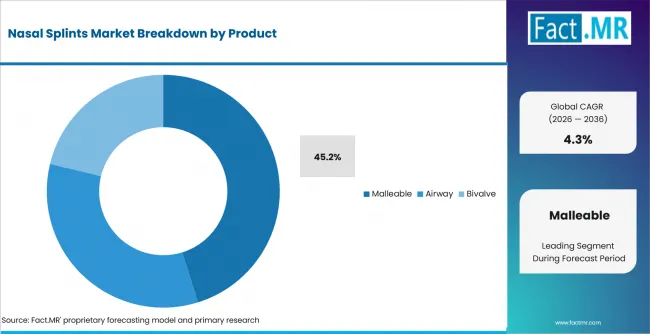
Nasal Splints Market Analysis By Product | Source: Fact.MR
Malleable splints lead because surgeons can shape nasal support during recovery. This makes the format useful in nose reconstruction and postoperative stabilization where fit affects patient comfort.
Summit Medical catalog material from June 2025 lists Denver thermoplastic nasal splints, internal nasal splints, Breeze nasal splints, and bivalve nasal splints. That breadth supports continued use of adjustable and procedure-specific formats.
How does Material shape demand?
Biodegradable is anticipated to capture 68.90% share in 2026.
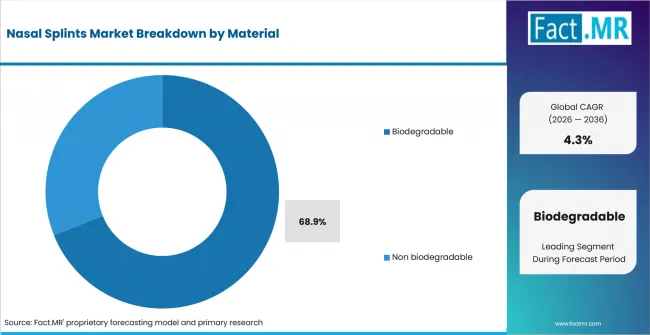
Nasal Splints Market Analysis By Material | Source: Fact.MR
Biodegradable materials lead where clinicians want support that reduces handling during recovery. The category fits selected nasal and sinus procedures where follow-up visits and patient comfort affect clinical preference.
Material choice also connects nasal splints with adjacent ENT medical devices where device comfort, infection control, and surgeon familiarity shape repeat selection. Silicone and polyethylene remain relevant in applications that require familiar handling.
What supports Hospitals within End Use?
Hospitals are estimated to represent 33.80% share in 2026.
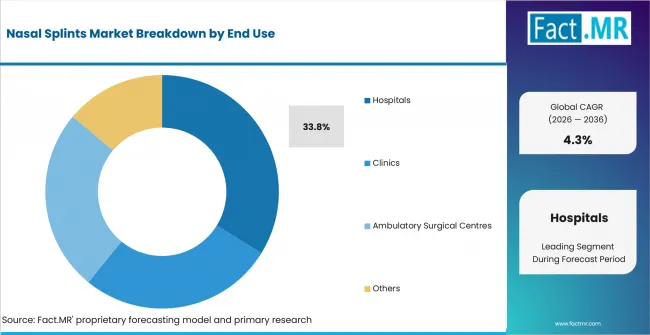
Nasal Splints Market Analysis By End Use | Source: Fact.MR
Hospitals lead because septoplasty, trauma repair, and complex rhinology work are commonly routed through operating rooms with formal product controls. Central stores also make repeat ordering easier than clinic-by-clinic buying.
NHS England Digital reported 13.1 million finished consultant episodes with at least one procedure or intervention for April 2025 to March 2026. The procedural base supports nasal products within surgical equipment planning.
What is accelerating Nasal Splints Market adoption, and what is holding it back?
Demand is expected to rise through ENT procedure volume and postoperative recovery needs. Growth is constrained by price pressure, material familiarity, and procedure-specific buying discipline.
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Hospital ENT procedure volume | +0.8% | Germany, U.K., USA | Short term (<= 2 years) |
| Rhinoplasty and septoplasty recovery needs | +0.7% | Global | Medium term (2-4 years) |
| Clear device classification and pack standardization | +0.5% | USA, Western Europe | Short term (<= 2 years) |
- Hospital ENT procedure volume: Recurring nasal and sinus procedures support stable demand for internal splints, external splints, and airway formats used during postoperative care. Hospitals and ENT centers benefit from standardized products that fit routine surgical and recovery workflows.
- Rhinoplasty and septoplasty recovery needs: Cosmetic and corrective nasal procedures support demand for splints that stabilize tissue, protect surgical sites, and assist healing after discharge. Product selection depends on procedure type, patient comfort, and clinician preference.
- Clear device classification and pack standardization: Established medical-device classification and standardized packaging support clearer catalog management for hospitals and distributors. Consistent product descriptions, labeling, and pack configurations can simplify ordering, inventory control, and clinical selection across ENT care settings.
Opportunity Impact Analysis
| Opportunity | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Biodegradable internal systems | +0.6% | USA, Japan, Germany | Medium term (2-4 years) |
| Clinic-based aesthetic nasal recovery | +0.5% | Brazil, USA, U.K. | Short term (<= 2 years) |
| Procedure-specific sterile packs | +0.4% | Global | Long term (>= 4 years) |
- Biodegradable internal systems: Absorbable and biodegradable formats are expected to gain use where clinicians want smoother postoperative care pathways.
- Clinic-based aesthetic nasal recovery: External malleable splints are projected to benefit from cosmetic surgery clinics that need consistent recovery support after rhinoplasty.
- Procedure-specific sterile packs: Standard packs are anticipated to improve ordering simplicity for hospitals and ambulatory surgical centers managing repeat nasal procedures.
Restraints Impact Analysis
| Restraint | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Low-ticket price pressure | -0.4% | Global | Short term (<= 2 years) |
| Surgeon preference for familiar materials | -0.3% | USA, Europe, Japan | Medium term (2-4 years) |
| Clinic stock discipline | -0.2% | Brazil, U.K. | Short term (<= 2 years) |
- Low-ticket price pressure: Nasal splints are small consumables, so hospitals often compare unit cost closely against material and sterility requirements.
- Surgeon preference for familiar materials: Silicone and aluminum formats remain difficult to displace where surgeons are comfortable with fit and removal behavior.
- Clinic stock discipline: Smaller clinics often limit product variety and keep fewer splint sizes when procedure schedules are uneven.
Which countries are scaling the Nasal Splints Market through 2036?
- The country comparison spans 1.6 percentage points and forms two practical growth bands across the forecast period.
- Germany remains 0.4 percentage point above Brazil through inpatient procedure volume and hospital-based ENT pathways.
- Brazil remains 0.4 percentage point above the USA as specialist access programs and private-plan coverage support elective procedures.
- The USA remains 0.4 percentage point above the U.K. through device classification clarity and ambulatory procedure visibility.
- The U.K. remains 0.4 percentage point above Japan as NHS procedure volume supports hospital and specialty clinic demand.
- Japan closes the displayed range through careful hospital product selection and aging-linked ENT care needs.
Comparable CAGRs can create different entry conditions because device category clarity, surgical volume, reimbursement discipline, and clinic channel depth vary by country. Full report coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Middle East & Africa.
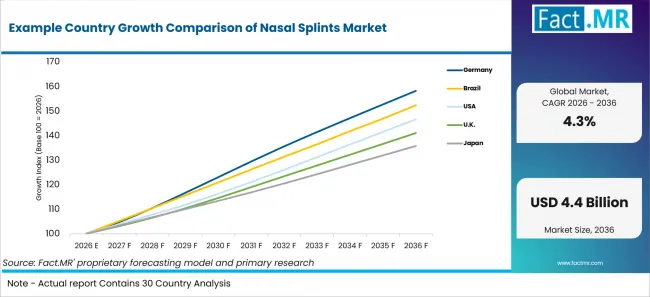
Example Country Growth Comparison Of Nasal Splints Market | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| Germany | 4.7% |
| Brazil | 4.3% |
| USA | 3.9% |
| U.K. | 3.5% |
| Japan | 3.1% |
What supports Germany adoption?
4.7% CAGR, supported by hospital procedure volume and ENT department standardization.
Destatis reported that Germany recorded around 17.5 million inpatient hospital treatment cases in 2024, while OECD reported that Germany’s health expenditure equaled 12.3% of GDP in 2024. This hospital base supports repeat demand for postoperative ENT consumables, including septal support splints. Adoption is shaped by hospital stock discipline, documentation requirements, and careful review of sterility, sizing, material specifications, and newer biodegradable formats.
How is Brazil scaling demand?
4.3% CAGR, driven by specialist access programs and private procedure channels.
Brazil’s ANS reported 52,918,690 medical-plan beneficiaries in December 2025, while the Ministry of Health projected 43.7 million exams in 2025 under Agora Tem Especialistas. These pathways support ENT and aesthetic nasal procedures requiring internal or external splints. Growth is tempered by public reimbursement discipline, smaller clinic inventories, surgeon-specific product preferences, and price comparison between imported specialty splints and locally available silicone or aluminum alternatives.
What supports USA adoption?
3.9% CAGR, backed by FDA classification clarity and outpatient surgical visibility.
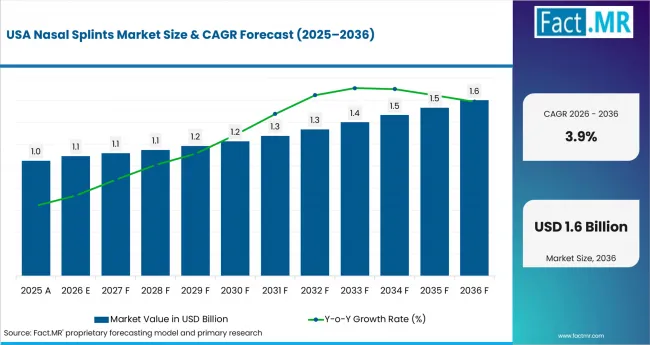
Nasal Splints Market Country Value Analysis | Source: Fact.MR
FDA classifies intranasal septal splints under product code LYA and 21 CFR 874.4780 as Class I devices, while CMS Procedure Price Lookup provides cost and copayment information for approximately 3,900 medical procedures performed in hospital outpatient departments and ambulatory surgical centers. Pre-sized sterile packs fit fast ENT workflows, although price transparency, strong competition from generic silicone and aluminum splints, and surgeon familiarity with established materials influence broader adoption.
What supports the U.K. growth?
3.5% CAGR, supported by NHS procedure volume and specialty clinic use.
NHS England Digital recorded 22.6 million Finished Consultant Episodes in 2024–25, while provisional data for April 2025 to March 2026 recorded 13.1 million Finished Consultant Episodes with at least one procedure or intervention. This activity supports recurring use of postoperative ENT consumables. Internal and external splints fit septoplasty, airway-support and rhinoplasty recovery, while public purchasing pressure, narrow preferred-product lists, and day-case discharge requirements shape supplier selection.
How does Japan perform?
3.1% CAGR, led by aging-linked ENT care needs and careful hospital product selection.
Japan’s Cabinet Office reported 36.24 million people aged 65 years and over as of October 1, 2024, while MHLW recorded 8,060 hospitals in 2024, providing broad institutional context for hospital-based healthcare delivery. Teaching hospitals support internal and bivalve splints for structured postoperative care. Adoption remains measured because hospitals emphasize material familiarity, dependable availability, standard sizing, predictable pack formats, and clear patient instructions before switching to newer product options.
Who leads the Nasal Splints Market?
Medtronic plc is active through FDA-listed Medtronic plc Xomed nasal splint products, including C-Flex Doyle bivalve and Doyle II airway splints that are listed as in commercial distribution.
Boston Medical Products participates through bivalve and nasal airway splints listed in AccessGUDID. Summit Medical, an Innovia Medical company, is active through Breeze, Denver, and internal nasal splints.
Competition is shaped by catalog depth, sterile pack availability, and surgeon trust. Adjacent categories such as nasal implant and ENT surgical devices influence supplier positioning because many buyers evaluate nasal support products with broader ENT portfolios.
Which companies are the key providers?
Key companies include Medtronic plc; Boston Medical Products Inc.; Innovia Medical through Summit Medical; Orfit Industries NV; and Olympus Corporation.
- Medtronic plc
- Boston Medical Products Inc.
- Innovia Medical (Summit Medical / DTR Medical)
- Orfit Industries NV
- Olympus Corporation
Bibliography
- U.S. Food and Drug Administration. (2026, August 31). Product classification [Splint, intranasal septal; product code LYA; 21 CFR 874.4780].
- U.S. Food and Drug Administration. (2026, August 24). Establishment registration & device listing [Medtronic Xomed, Inc.; Nasal Splint].
- NHS England. (2025, September 25). Hospital Admitted Patient Care Activity, 2024-25.
- NHS England. (2026, May 14). Provisional Monthly Hospital Episode Statistics for Admitted Patient Care, Outpatient and Accident and Emergency data, April 2025–March 2026.
- Statistisches Bundesamt (Destatis). (2025, November 6). 2,0 % mehr stationäre Krankenhausbehandlungen im Jahr 2024.
- Statistisches Bundesamt (Destatis). (2025, November 27). Krankenhäuser 2024 nach Trägern und Bundesländern.
- Organisation for Economic Co-operation and Development. (2025, November 13). Health at a Glance 2025: Germany.
- Deutscher Bundestag. (2026, April 1). Entwicklung der Zahl der Krankenhäuser in Deutschland.
- Agência Nacional de Saúde Suplementar. (2026, August 5). Dados Gerais.
- Ministério da Saúde. (2025, September 16). Anexo I da Portaria SAES/MS nº 3.245, de 9 de setembro de 2025.
- Cabinet Office, Government of Japan. (2025, June). Annual report on the ageing society [Summary] FY2025.
- Statistics Bureau of Japan. (2026, May 29). Preliminary counts of the population and households: 2025 Population Census.
- Summit Medical, an Innovia Medical Company. (2025, December 15). Internal nasal splints CE Mark [Instructions for use].
This Report Answers
- The report covers where nasal splints are used by mechanism, product, material, and end use.
- Segment analysis explains why internal splints, malleable products, biodegradable materials, and hospitals lead.
- Country analysis covers Germany, Brazil, the USA, the U.K., and Japan.
- Competitive analysis reviews active providers across internal splints, external splints, bivalve designs, and related ENT diagnostic devices.
- Application analysis covers septoplasty, rhinoplasty, trauma repair, airway maintenance, and links with aesthetic medicine.
What does the Nasal Splints Market cover?
The Nasal Splints Market covers temporary support devices placed inside or outside the nose after surgery or trauma. It includes internal septal support, airway splints, bivalve products, and external malleable splints used after cosmetic surgery or corrective procedures.
The assessment covers hospitals, clinics, ambulatory surgical centres, and other care settings. Demand is reviewed across material categories and linked to procedure use.
What is included in the scope?
The scope includes sterile nasal splints sold for septoplasty, rhinoplasty, trauma repair, and airway support. It includes internal systems, external support products, airway formats, bivalve splints, and devices used with transnasal endoscopy guidance devices in ENT care settings.
The scope also includes supplier portfolio review, product-material mapping, country adoption review, and competitive participation where companies provide identifiable nasal splint products.
What is excluded from the scope?
The scope excludes general nasal dressings, bleeding-control packing, sinus stents outside the nasal splint definition, permanent implants, and broad ENT instruments.
The scope also excludes unrelated orthopaedic splints, retail cosmetic tapes, and general surgical supplies outside postoperative nasal support.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report’s scope and coverage?
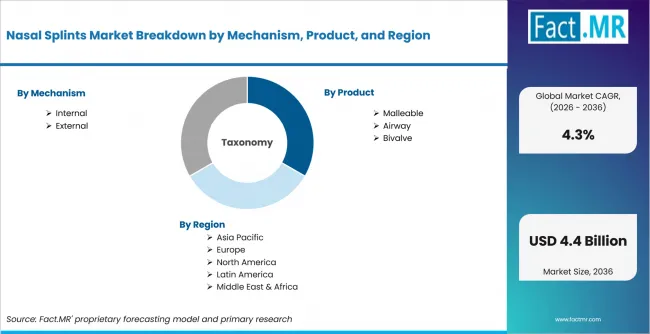
Nasal Splints Market Breakdown By Mechanism, Product, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD Billion |
| Market Definition | Temporary internal or external nasal support devices used after septoplasty, rhinoplasty, trauma repair, airway support, or related procedures. |
| Mechanism | Internal; External |
| Product | Malleable; Airway; Bivalve |
| Material | Biodegradable; Non biodegradable |
| End Use | Hospitals; Clinics; Ambulatory Surgical Centres; Others |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | Germany; Brazil; USA; U.K.; Japan |
| Key Companies Profiled | Medtronic plc; Boston Medical Products Inc.; Innovia Medical (Summit Medical / DTR Medical); Orfit Industries NV; Olympus Corporation |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using procedure indicators, care channels, device listings, product portfolios, country adoption, and provider participation. |
How is the market segmented?
-
By Mechanism
- Internal
- Septal Support Splints
- Airway Maintenance Splints
- Absorbable Internal Systems
- External
- External Nasal Support
- Adhesive External Splints
- Thermoplastic External Systems
- Internal
-
By Product
- Malleable
- Aluminum Based Splints
- Polymer Based Splints
- Adjustable Splints
- Airway
- Single Airway Splints
- Dual Airway Splints
- Ventilated Splints
- Bivalve
- Hinged Bivalve Splints
- Clip Based Bivalve Splints
- Anatomical Bivalve Splints
- Malleable
-
By Material
- Biodegradable
- Polylactic Acid Materials
- Gelatin Based Materials
- Composite Biodegradable Materials
- Non biodegradable
- Silicone Materials
- Polyethylene Materials
- Fluoropolymer Materials
- Biodegradable
-
By End Use
- Hospitals
- General Hospitals
- Specialty Hospitals
- Teaching Hospitals
- Clinics
- ENT Clinics
- Cosmetic Surgery Clinics
- Multispecialty Clinics
- Ambulatory Surgical Centres
- Standalone Surgical Centres
- Hospital Affiliated Centres
- Specialized Ambulatory Centres
- Others
- Military Medical Facilities
- Academic Research Institutes
- Home Healthcare Settings
- Hospitals
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa