- Market Value (2025): USD 657.2 Mn
- Estimated Value (2026): USD 790.0 Mn
- Forecast Value (2036): USD 4973.6 Mn
- CAGR (2026-2036): 20.2%
How does the PHA Extrusion Coatings Market break down by segment?
Paper extrusion grade leads at 35.0%; paperboard leads at 34.0%.
Which PHA Grade dominates?
Paper extrusion grade holds 35.0% share in 2026.
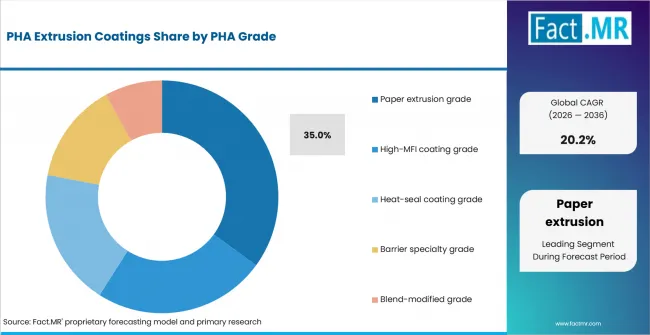
Pha Extrusion Coatings Analysis By Pha Grade | Source: Fact.MR
Paper extrusion grade leads because the coating layer must pass through commercial lines without web breaks or weak adhesion. Paper-cup and tray converters value stable melt flow and liquid control. Coating grades must therefore be tuned for continuous rolls and hot-cup conversion.
What leads the PHA Family segment?
PHBV holds 31.0% share in 2026.
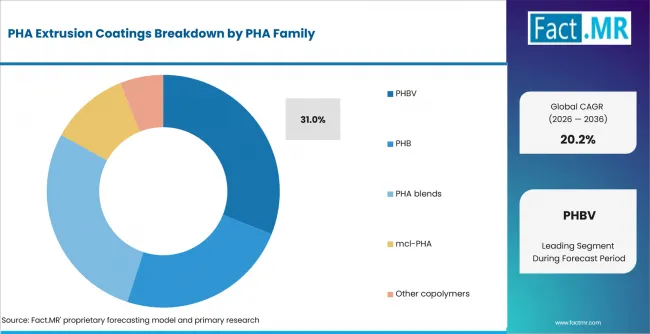
Pha Extrusion Coatings Analysis By Pha Family | Source: Fact.MR
PHBV holds the main position because it gives PHA suppliers a route to barrier performance and compostable-polymer positioning. Coating formulators use it where fiber packaging needs grease or moisture protection without conventional plastic laminates.
How does Substrate shape demand?
Paperboard holds 34.0% share in 2026.
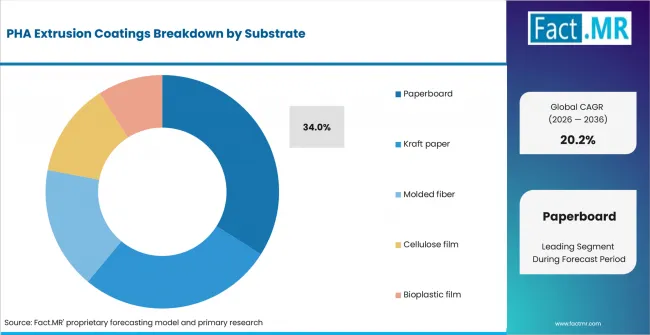
Pha Extrusion Coatings Analysis By Substrate | Source: Fact.MR
Paperboard leads the substrate mix because it is common in cups, lids, folding cartons and takeaway containers. Defra reported that the UK recycled 4,069 kilotonnes of paper and cardboard packaging in 2024. The recovery base makes paperboard a familiar material for converters testing PHA-coated structures.
What supports Foodservice within End-use?
Foodservice holds 31.0% share in 2026.
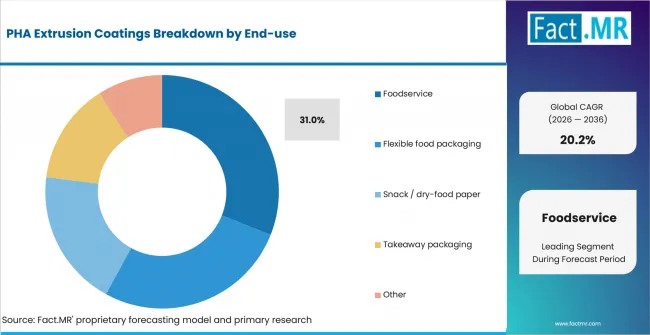
Pha Extrusion Coatings Analysis By End Use | Source: Fact.MR
Foodservice packaging uses coated fiber formats where oil, grease and hot-liquid exposure are daily tests. The U.S. Census Bureau's August 2026 release revised June 2026 retail and food-services sales to USD 768.1 billion. Channel scale supports cup, bowl and takeaway-pack trials where PHA coating grades are positioned to replace plastic linings.
What is accelerating PHA Extrusion Coatings Market adoption, and what is holding it back?
Adoption is rising through foodservice conversion, paperboard coating trials and packaging compliance pressure.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Foodservice fiber-packaging conversion | +2.4% | North America, Europe, Japan | Short term (<= 2 years) |
| Paperboard and kraft coating qualification | +1.8% | Global | Medium term (2-4 years) |
| Packaging waste and recyclability regulation | +1.5% | Europe, UK, Japan | Medium term (2-4 years) |
| Supplier launches in PHA coating compounds | +1.1% | USA, Asia, Europe | Short term (<= 2 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Home-compostable coated paperboard | +1.5% | Europe, North America | Medium term (2-4 years) |
| Repulpable barrier structures | +1.2% | UK, Germany, USA | Long term (>= 4 years) |
| Specialty grades for hot and cold cups | +0.8% | Global | Short term (<= 2 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Coating-line qualification cost | -0.8% | Global | Short term (<= 2 years) |
| Uneven composting and recycling access | -0.7% | USA, Japan, Europe | Medium term (2-4 years) |
| Competition from incumbent coatings | -0.5% | Global | Long term (>= 4 years) |
Which countries are scaling the PHA Extrusion Coatings Market through 2036?
- The country comparison spans 2.8 percentage points and forms three practical growth bands across the forecast period.
- The United Kingdom remains 1.3 percentage points above Italy through packaging-tax pressure and foodservice fiber conversion.
- Italy stays 0.6 percentage point above the USA as compostable-bioplastic recovery supports local qualification.
- The USA remains 0.3 percentage point above Germany through foodservice sales and coated-serviceware trials.
- Germany remains 0.6 percentage point above Japan through PPWR compliance and ready-meal packaging use.
- Japan closes the displayed range through container-recycling duties and packaging recovery discipline.
Comparable CAGRs create different entry conditions due to converter readiness, packaging law and end-of-life access. Full report coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Middle East & Africa.
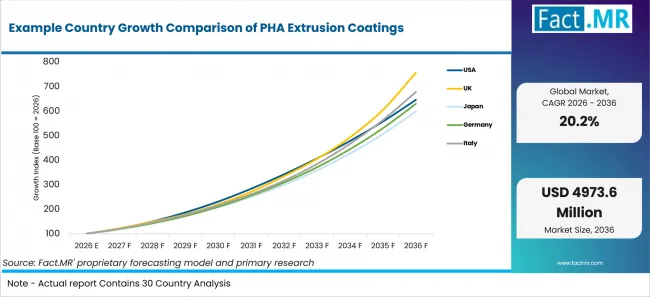
Example Country Growth Comparison Of Pha Extrusion Coatings | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| United Kingdom | 22.4% |
| Italy | 21.1% |
| United States | 20.5% |
| Germany | 20.2% |
| Japan | 19.6% |
What supports the United Kingdom’s growth?
22.4% CAGR, supported by packaging-tax pressure and fiber-packaging substitution.
HMRC reported in August 2026 that 1,388 thousand tonnes of plastic packaging were imported into the UK in 2024 to 2025. The United Kingdom is projected to record 22.4% CAGR through 2036 as plastic-tax exposure encourages brands to review coated-paper alternatives. Paperboard converters gain a practical route where PHA coatings meet heat-seal and grease-resistance requirements.
How is Italy scaling demand?
21.1% CAGR, driven by packaging recycling depth and compostable-bioplastic channels.
Italy has an established packaging recovery base for fiber formats and compostable materials. CONAI reported in June 2025 that Italy recycled 76.7% of packaging placed on the market in 2024. Italy is anticipated to post 21.1% CAGR through 2036 as converters pair paperboard structures with compostable coating claims for takeaway and dry-food formats.
What supports adoption in the USA?
20.5% CAGR, backed by foodservice spending and coated-serviceware conversion.
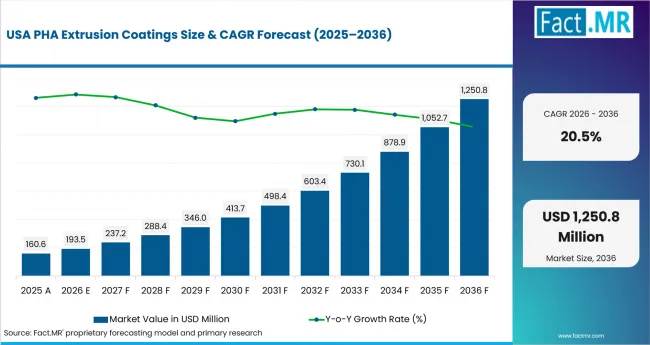
Pha Extrusion Coatings Country Value Analysis | Source: Fact.MR
Foodservice packaging gives the USA a broad application base for coated cups, bowls and takeaway containers. U.S. Census Bureau advance estimates placed May 2026 retail and food-services sales at USD 763.7 billion. The USA is estimated to advance at 20.5% CAGR through 2036 as brands test PHA-coated fiber packs for grease control and compostable positioning.
What is supporting Germany’s adoption?
20.2% CAGR, supported by packaging-waste regulation and paperboard use.
Germany combines policy pressure with a large packaging-waste base. The Federal Environment Agency reported in March 2026 that Germany generated 17.9 million tonnes of packaging waste in 2023. Germany is forecast to reach 20.2% CAGR through 2036 as PPWR requirements push coated-paper formats toward clearer recyclability and material documentation.
How does Japan perform?
19.6% CAGR, led by container-recycling duties and packaging recovery discipline.
Japan’s Containers and Packaging Recycling Act assigns consumers responsibility for sorted disposal, municipalities responsibility for sorted collection and covered business operators responsibility for recycling. Japan’s Ministry of the Environment reported in March 2026 that total municipal solid waste generation reached 38.11 million tonnes in FY2024. Japan is expected to record 19.6% CAGR through 2036 as converters test PHA coatings for food-contact paper formats with controlled disposal claims.
Who leads the PHA Extrusion Coatings Market?
CJ Biomaterials provides a current paper-and-board extrusion-coating reference. Its PHACT platform is positioned around stable melt-curtain performance, foodservice formats and barrier performance against liquids, oils and grease.
Danimer Scientific now operates under Teknor Apex ownership following the June 2025 acquisition. The combination places Danimer’s PHA materials and formulation capabilities within Teknor Apex’s broader compounding and material-science business, supporting wider application-development opportunities.
Competition is centered on coating-grade processability, seal performance, food-contact documentation and end-of-life certification. Suppliers that support converters during trial runs gain an advantage because application proof is needed before commercial paperboard conversion.
Which companies are the key providers?
Key companies include Danimer Scientific / Teknor Apex; CJ Biomaterials; Kaneka; Helian Polymers; PhaBuilder; and Ningbo TianAn Biologic Material Co., Ltd..
- Danimer Scientific / Teknor Apex
- CJ Biomaterials
- Kaneka
- Helian Polymers
- PhaBuilder
- Ningbo TianAn Biologic Material Co., Ltd.
Bibliography
- CJ Biomaterials. (2025, October 1). CJ Biomaterials launches new PHA platform for extrusion coatings.
- CONAI. (2025, June 25). Packaging recycling: Italy reaches 76.7%.
- Department for Environment, Food & Rural Affairs. (2025, July 23). UK statistics on waste.
- Directorate-General for Environment. (2026, August 11). New EU packaging rules start to apply, including restrictions on PFAS in food-contact packaging. European Commission.
- Environment Agency. (2026, May 22). Compliance monitoring and enforcement activity 2025.
- HM Revenue & Customs. (2026, August 27). Plastic Packaging Tax (PPT) statistics commentary.
- Ministry of the Environment, Government of Japan. (2026, March 27). Municipal solid waste generation and disposal in FY2024.
- Paques Biomaterials. (2025, September 8). European collaboration to bring PHA-based barrier coatings to market.
- Paques Biomaterials. (2026a, August 6). First Happy Cup produced from Caleyda®.
- Paques Biomaterials. (2026b, June 4). Start process towards Food-Grade Caleyda.
- Teknor Apex. (2025, June 10). Teknor Apex acquires Danimer Scientific to further diversify sustainable materials portfolio.
- Umweltbundesamt. (2026, March 5). Verpackungsabfälle [Packaging waste].
- U.S. Census Bureau. (2026a, August 14). Advance monthly sales for retail and food services, July 2026.
- U.S. Census Bureau. (2026b, June 17). Advance monthly sales for retail and food services, May 2026.
- Zeballos, E., & Sinclair, W. (2026, June 11). Total U.S. food spending reached $2.51 trillion in 2025. U.S. Department of Agriculture, Economic Research Service.
This Report Answers
- The report explains where PHA extrusion coatings are used across grade, polymer family, substrate and end-use applications.
- Segment analysis identifies the leading subsegments and the operating reasons converters prioritize them.
- Country analysis examines the listed markets and the policy or packaging mechanisms supporting coating qualification.
- Competitive analysis reviews current providers across PHA resin supply, coating compounds and application-development activity.
- Application analysis assesses how heat sealing, grease resistance and end-of-life documentation influence supplier selection.
What does the PHA Extrusion Coatings Market cover?
The PHA Extrusion Coatings Market covers biobased layers that add barrier and heat-seal functions to fiber packaging. The scope connects biobased PHA coatings, compostable heat-seal coatings and paper barrier coatings where the layer contains PHA chemistry.
The assessment covers paper extrusion, high-MFI, heat-seal, barrier specialty and blend-modified grades. It also covers bio-based cartonboard coatings where foodservice packs require grease or liquid resistance.
What is included in the scope?
The scope includes PHA coating compounds, extrusion grades and coating structures used on paperboard, kraft paper, molded fiber and cellulose film. Adjacent resin families include bio-based barrier resins where they overlap with coated fiber packaging.
It includes coated cups, trays, bowls, lids, snack papers and takeaway packaging. The analysis also links to paper packaging materials, next-gen paper-based and fiber-based packaging and bioplastics where PHA-coated substrates overlap with adjacent packaging categories.
What is excluded from the scope?
The scope excludes PE-coated paper, acrylic coatings without PHA content, uncoated paperboard and foodservice articles sold without a PHA extrusion coating layer. It also excludes biodegradable packaging materials where the barrier layer uses PLA, starch blend, wax or waterborne chemistry.
General zero waste packaging claims are excluded when PHA chemistry is absent from the coating layer. PHA films are excluded when they are sold as free-standing films and are outside extrusion-coated substrate applications.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the PHA Extrusion Coatings Market forecast to be worth by 2036?
USD 790.0 million in 2026 to USD 4973.6 million by 2036 at a 20.2% CAGR.
- The PHA Extrusion Coatings Market reached USD 657.2 million in 2025.
- Demand is projected to increase from USD 790.0 million in 2026 to USD 4973.6 million by 2036.
- The market is forecast to record a 20.2% CAGR from 2026 to 2036 as paper converters qualify biobased coating layers for grease control.
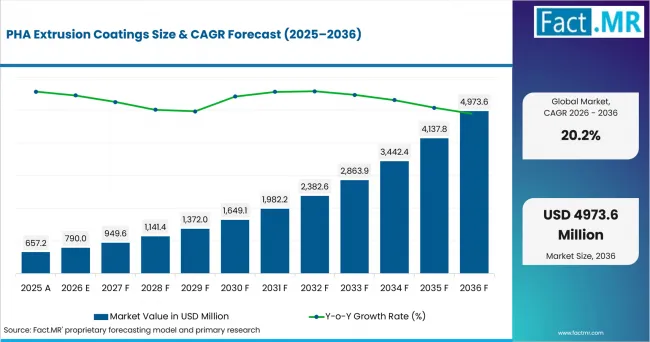
Pha Extrusion Coatings Value Analysis | Source: Fact.MR
What are the defining numbers behind PHA Extrusion Coatings Market growth?
USD 4,183.6 million absolute opportunity by 2036, led by paper extrusion grade, paperboard and foodservice packaging.
- Demand Drivers in the Market
- Paper-cup converters need extrusion grades that form a stable melt curtain, so PHA coating suppliers are judged on runnability before label claims.
- Foodservice brands need grease and liquid resistance on fiber substrates. USDA ERS reported in June 2026 that U.S. food-away-from-home spending reached USD 1.41 trillion in 2025.
- Packaging design teams need coatings that fit recycling and composting routes. The European Commission said in August 2026 that the new EU packaging rules aim to make all packaging recyclable by 2030.
- Mills and converters need certified input materials with food-contact clearance, so supplier documentation becomes part of coating-grade qualification.
- Key Segments Analyzed
- By PHA Grade: Paper extrusion grade is expected to hold 35.0% share in 2026 driven by paper-cup and board formats needing continuous coating runs.
- By PHA Family: PHBV is projected to account for 31.0% share in 2026 supported by its fit with barrier and compostable material positioning.
- By Substrate: Paperboard is anticipated to capture 34.0% share in 2026 owing to its use in cups, trays and takeaway board structures.
- By End-use: Foodservice is estimated to represent 31.0% share in 2026 shaped by coated cups, bowls and trays used in takeaway meals.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “PHA extrusion coating is drawing attention because converters need a plastic-replacement layer that still runs on industrial lines. Demand is expected to move first where paperboard formats need heat sealing and food-contact documentation. Suppliers need resin tuning, coating know-how and credible end-of-life certification.”
- Strategic Implications
- Resin suppliers should publish coating-grade processing windows so converters reduce trial waste during line qualification.
- Paperboard converters should validate seal strength and grease resistance together before offering claims to foodservice accounts.
- Brand teams should separate home-compostable, industrial-compostable and repulpable claims in approval files.
- Certification bodies should align test evidence with real packaging structures because coating thickness changes disintegration behavior.
The United Kingdom is projected to record 22.4% CAGR through 2036 driven by packaging-tax pressure. Italy is anticipated to post 21.1% CAGR supported by compostable-bioplastic recovery. The USA is estimated to advance at 20.5% CAGR because foodservice spending expands coated-serviceware use. Germany is forecast to reach 20.2% CAGR reinforced by PPWR compliance. Japan is expected to record 19.6% CAGR as packaging recovery duties keep coated paper relevant.
What is the report’s scope and coverage?
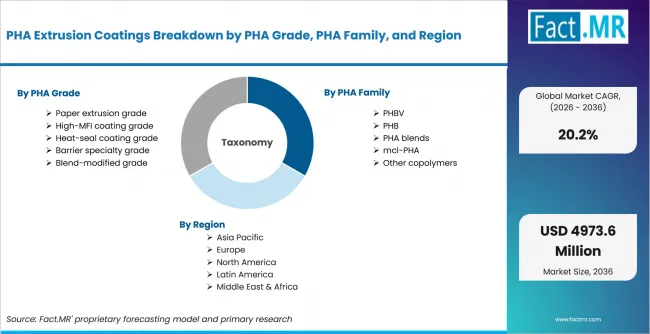
Pha Extrusion Coatings Breakdown By Pha Grade, Pha Family, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD million in 2026 to USD million by 2036 at a CAGR |
| Market Definition | PHA extrusion coatings are biobased coating layers applied to paper, paperboard, kraft paper, molded fiber, cellulose film and bioplastic film to add heat sealing, grease resistance, moisture control or compostable barrier functionality. |
| PHA Grade | Paper extrusion grade; High-MFI coating grade; Heat-seal coating grade; Barrier specialty grade; Blend-modified grade |
| PHA Family | PHBV; PHB; PHA blends; mcl-PHA; Other copolymers |
| Substrate | Paperboard; Kraft paper; Molded fiber; Cellulose film; Bioplastic film |
| End-use | Foodservice; Flexible food packaging; Snack / dry-food paper; Takeaway packaging; Other |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | United States; United Kingdom; Japan; Germany; Italy |
| Key Companies Profiled | Danimer Scientific / Teknor Apex; CJ Biomaterials; Kaneka; Helian Polymers; PhaBuilder; Ningbo TianAn Biologic Material Co., Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using coated-paper demand, PHA resin qualification, foodservice packaging use, substrate mix, country adoption and provider portfolio review. |
How is the market segmented?
-
By PHA Grade
- Paper extrusion grade
- High-MFI coating grade
- Heat-seal coating grade
- Barrier specialty grade
- Blend-modified grade
-
By PHA Family
- PHBV
- PHB
- PHA blends
- mcl-PHA
- Other copolymers
-
By Substrate
- Paperboard
- Kraft paper
- Molded fiber
- Cellulose film
- Bioplastic film
-
By End-use
- Foodservice
- Flexible food packaging
- Snack / dry-food paper
- Takeaway packaging
- Other
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa

