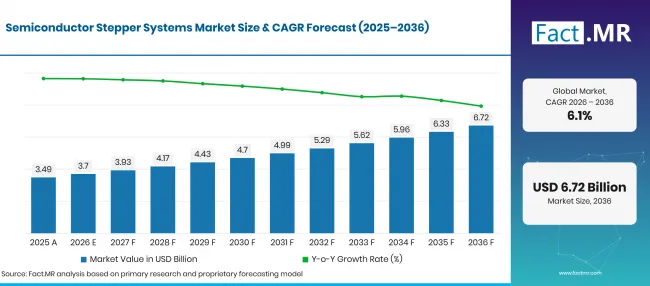
- Market Value (2025): USD 3.49 Bn
- Estimated Value (2026): USD 3.7 Bn
- Forecast Value (2036): USD 6.72 Bn
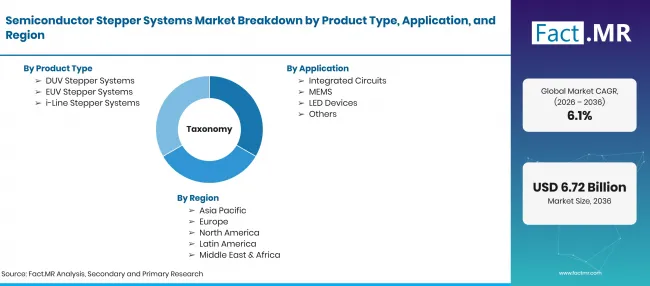
- CAGR (2026-2036): 6.1%
What is the Semiconductor Stepper Systems Market forecast to be worth by 2036?
USD 3.7 billion in 2026 to USD 6.72 billion by 2036 at a 6.1% CAGR.
- The semiconductor stepper systems market reached USD 3.49 billion in 2025.
- Demand is projected to increase from USD 3.7 billion in 2026 to USD 6.72 billion by 2036.
- The semiconductor stepper systems market is expected to record a 6.1% CAGR from 2026 to 2036.
Semiconductor Stepper Systems Market Card (7) | Source: Fact.MR
What are the defining numbers behind Semiconductor Stepper Systems Market growth?
An absolute opportunity of USD 3.0 billion is created between 2026 and 2036.
- Demand Drivers in the Market
- Chip foundries need stepper systems that keep circuit patterns accurately aligned across several layers. In March 2025, ASML and imec extended their partnership for five years to work on 0.55 NA EUV, 0.33 NA EUV and DUV immersion technologies for research on chips below 2 nm [1]. Reliable equipment is important because delays during pattern printing can slow down the next stages of wafer production.
- Chip manufacturers continue to use DUV systems for established chip designs and special products such as power chips and sensors. Canon supplies i-line and DUV equipment for these applications, helping manufacturers maintain regular production without moving every product to newer chip technology.
- Advanced chip packaging requires equipment that can handle larger panels while keeping circuit patterns accurately aligned.
- Key Segments Analyzed
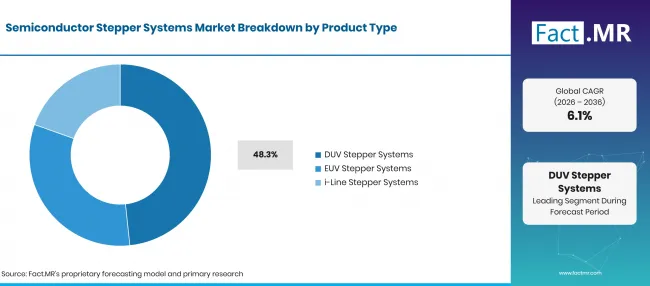
- By Product Type: DUV Stepper Systems are projected to hold 48.3% share in 2026 because deep-ultraviolet tools remain widely used across mature and specialty semiconductor processes.
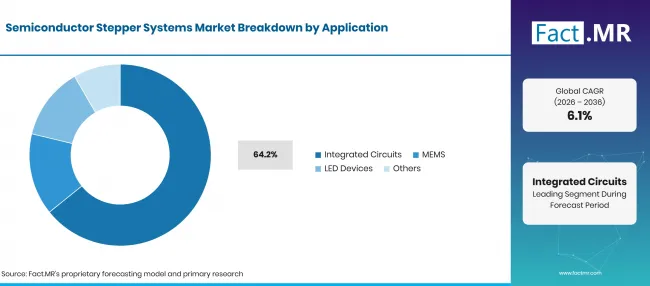
- By Application: Integrated Circuits are expected to account for 64.2% share in 2026 owing to the repeated lithography steps required across logic, and mixed-signal production.
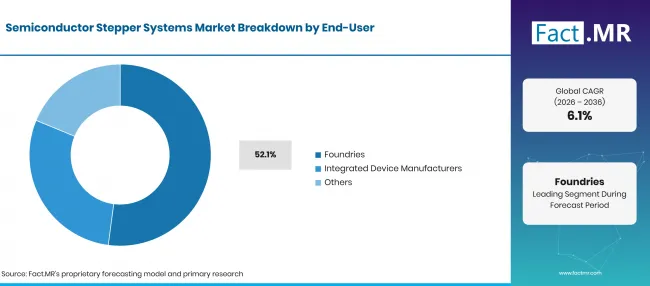
- By End-User: Foundries are anticipated to capture 52.1% share in 2026 as multi-customer fabs run broad device mixes and maintain large lithography tool fleets.
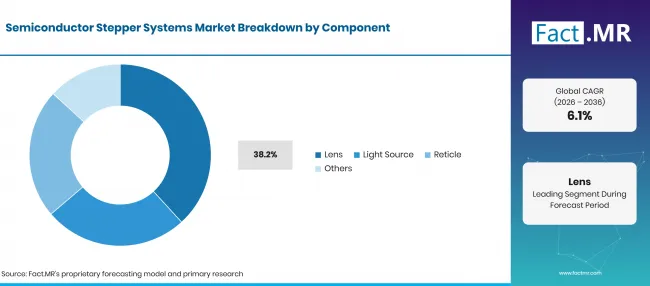
- By Component: Lens is forecast to represent 38.2% share in 2026 since projection accuracy depends on optical performance, and stable imaging over repeated exposures.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Chip manufacturers choose stepper systems based on the type of devices they produce. Advanced chip production requires EUV equipment, while DUV and i-line systems continue to serve established chip designs and specialty devices.”
- Strategic Implications
- Changes in chip production require stepper manufacturers to offer upgrades for optical parts and alignment systems as well as software and wafer handling. Replacing individual parts can help factories use existing machines for longer without buying a completely new system.
- Foundries can plan their equipment needs based on the number and type of circuit layers being produced. They also need to consider how often each machine will be used instead of installing advanced equipment across every production line.
- Stable optical parts and reliable light sources help equipment suppliers maintain consistent chip production. Accurate mask positioning and longer-lasting components also reduce interruptions and help factories produce wafers with fewer variations.
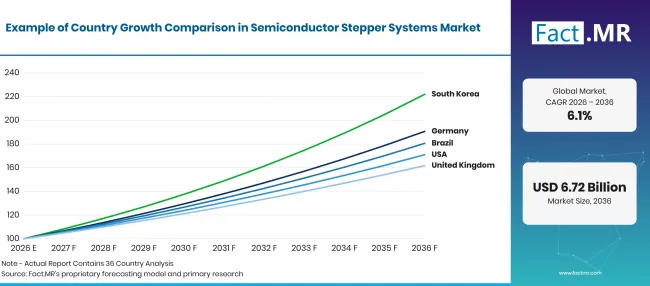
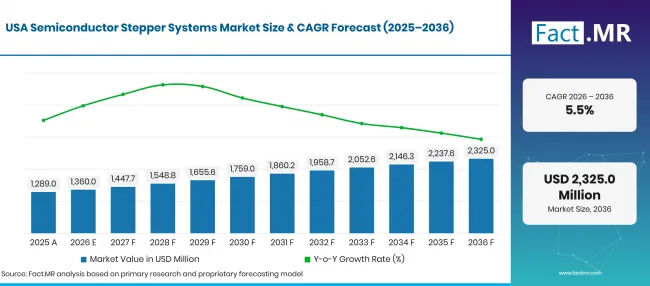
Germany leads with a 6.7% CAGR through 2036, backed by investment in semiconductor factories in Dresden. Brazil follows at 6.1% as government programs help build local chip production capabilities. The United States records 5.5%, with new factories creating more opportunities for stepper equipment suppliers. The United Kingdom grows at 4.9% through public support for semiconductor development, while Japan reaches 4.4% as government policies encourage investment in advanced chip manufacturing.
How does the Semiconductor Stepper Systems Market break down by segment?
DUV Stepper Systems lead Product Type at 48.3%; Integrated Circuits lead Application at 64.2%; Foundries lead End-User at 52.1%; Lens leads Component at 38.2%.
Which Product Type dominates?
DUV Stepper Systems hold 48.3% share in 2026.
Semiconductor Stepper Systems Market Card (18) | Source: Fact.MR
DUV stepper systems remain widely used because chip factories rely on them to print circuit patterns across many production layers. Even factories with EUV equipment continue using DUV for work that does not require the most advanced technology. These machines also help control production costs for established chip designs and specialty devices.
EUV systems handle the smallest and most detailed circuit patterns used in advanced chips. ASML reported EUR 13.2 billion in bookings during Q4 2025, including EUR 7.4 billion for EUV systems [3]. i-line steppers continue to serve specialty chip production where their capabilities meet manufacturing needs.
What leads the Application segment?
Integrated Circuits account for 64.2% share in 2026.
Semiconductor Stepper Systems Market Card (15) | Source: Fact.MR
Integrated circuits account for the largest use of stepper systems because each wafer goes through several rounds of circuit pattern printing. Logic and memory chips require highly accurate patterns, while analog and mixed-signal chips continue to use established manufacturing processes.
MEMS production also uses these machines to create small structures and sensor parts with accurate alignment. LED manufacturing requires patterned wafers as well. Canon includes integrated circuits and image sensors among its lithography applications, along with MEMS and devices used in radio communication, light-based technology and power electronics.
How does End-User shape demand?
Foundries capture 52.1% share in 2026.
Semiconductor Stepper Systems Market Card (17) | Source: Fact.MR
Foundries hold the strongest position as they produce large volumes of chips for different customers. Their factories need a mix of advanced stepper systems and established DUV machines to handle different chip designs and production requirements.
Companies that manufacture their own chips also use steppers for memory and logic production as well as power devices and sensors. In June 2025, the U.S. Department of Commerce reported that Micron planned about USD 200 billion in semiconductor manufacturing and research investment in the United States [4].
What supports demand for Lens within Component?
Lens represents 38.2% share in 2026.
Semiconductor Stepper Systems Market Card (16) | Source: Fact.MR
Lens systems play the vital role in stepper equipment because they help transfer circuit patterns from the mask onto the wafer with high accuracy. Their performance affects image sharpness and focus while keeping patterns properly aligned during repeated printing.
Light sources provide the energy needed for exposure, while reticles hold the circuit designs. In June 2026, Nikon stated that its new digital lithography technology targets 1.5 µm resolution and at least 65 panels per hour, more than 30% above the DSP-100 target [5].
What is accelerating Semiconductor Stepper Systems Market adoption, and what is holding it back?
Investment in new chip factories and more accurate pattern printing is increasing spending on stepper systems, while high equipment costs and complex operating requirements continue to limit purchases.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| New semiconductor fab capacity | +1.4% | North America, Western Europe, East Asia | Medium term (2-4 years) |
| Higher overlay and resolution requirements | +1.1% | East Asia, North America, Western Europe | Long term (>= 4 years) |
| DUV replacement and upgrade cycles | +0.9% | Global | Medium term (2-4 years) |
| Advanced packaging lithography | +0.7% | East Asia, North America | Medium term (2-4 years) |
| Specialty device production | +0.5% | Global | Long term (>= 4 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Back-end panel lithography | +0.8% | East Asia, North America | Medium term (2-4 years) |
| Installed-base optical and control upgrades | +0.6% | Global | Short term (<= 2 years) |
| Mature-node capacity additions | +0.5% | Latin America, South Asia & Pacific | Long term (>= 4 years) |
| Service and uptime programs | +0.4% | Global | Short term (<= 2 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| High capital cost per exposure tool | -0.9% | Global | Long term (>= 4 years) |
| Export-control and licensing limits | -0.6% | North America, East Asia | Medium term (2-4 years) |
| Power and facility operating costs | -0.5% | Western Europe, East Asia | Medium term (2-4 years) |
| Long qualification and installation cycles | -0.4% | Global | Short term (<= 2 years) |
Which countries are scaling the Semiconductor Stepper Systems Market through 2036?
- Germany holds a 0.6-point lead over Brazil as new fab investment in Dresden expands exposure-tool requirements.
- Brazil follows at 6.1%, supported by public semiconductor incentives and domestic capacity programs.
- The United States stands 0.6 points behind Brazil, with large manufacturing projects sustaining demand for lithography tools.
- The United Kingdom follows the United States by 0.6 points as policy support focuses on chip design, hardware, research, and specialist manufacturing.
- Japan closes the five-country range at 4.4%, supported by leading-edge manufacturing investment and a deep domestic equipment base.
Country conditions differ by fab scale, technology mix, public support, energy cost, and trade rules. Coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Middle East & Africa.
Semiconductor Stepper Systems Market Card (9) | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| Germany | 6.7% |
| Brazil | 6.1% |
| United States | 5.5% |
| United Kingdom | 4.9% |
| Japan | 4.4% |
What supports Germany adoption?
6.7% CAGR, supported by semiconductor fab expansion and public investment.
Germany's investment in new chip factories is expected to increase purchases of stepper systems as production lines are prepared and tested before regular manufacturing begins. In February 2025, the Federal Ministry for Economic Affairs and Climate Action reported that Infineon planned to invest about EUR 3.4 billion in its Dresden facility, with up to EUR 920 million set aside for government support [6].
How is Brazil scaling demand?
6.1% CAGR, shaped by industrial policy and domestic semiconductor capability.
Brazil's semiconductor industry is expected to expand gradually as the country builds its chip manufacturing capabilities. This approach creates opportunities for stepper systems used in established chip designs and specialty production. In September 2026, Finep reported that Brazil aims to increase its share of the global semiconductor supply chain from 1% to 2% by 2033 [7].
What supports the United States outlook?
5.5% CAGR, supported by large fab programs and domestic capacity expansion.
Semiconductor Stepper Systems Market Card (8) | Source: Fact.MR
New semiconductor factories in the United States are expected to increase purchases of lithography equipment for memory chips, logic chips and specialty devices. In March 2025, the White House announced that TSMC planned an additional USD 100 billion investment in the United States, bringing its total planned investment to about USD 165 billion [8]. These factories need different types of exposure equipment because DUV systems continue to handle many circuit layers.
How is the United Kingdom developing demand?
4.9% CAGR, supported by specialist manufacturing and semiconductor research.
In the United Kingdom, purchases of stepper systems are likely to remain focused on compound semiconductor production, research facilities and factories making specialty chips. The Department for Science, Innovation and Technology reported in September 2026 that equipment and tools manufacturing accounted for 29.8% of small and medium-sized business activity in the semiconductor supply chain [9]. This industry structure creates opportunities for i-line and DUV systems in small-scale production lines, MEMS, photonics and other specialty devices.
How does Japan perform?
4.4% CAGR, shaped by leading-edge programs and a deep equipment base.
Japan's investment in advanced chip manufacturing and its established equipment industry are creating opportunities for lithography systems. In April 2025, the Ministry of Economy, Trade and Industry announced JPY 802.5 billion in additional support for Rapidus, bringing total support to JPY 1,722.5 billion [10]. While advanced chip factories are adding EUV equipment, DUV and i-line systems remain important for producing memory chips, image sensors, power devices and other specialty semiconductors.
Who leads the Semiconductor Stepper Systems Market?
Major lithography companies lead the semiconductor stepper systems market. ASML supplies advanced DUV and EUV systems, while Nikon offers ArF, KrF and i-line equipment.
Canon provides KrF and i-line systems along with nanoimprint technology. In 2025, Nikon introduced the DSP-100 for advanced chip packaging and larger panels [2]. Smaller circuit patterns also require better quality checks during production. According to Fact.MR analysis, semiconductor defect inspection equipment plays an important role in finding defects and improving chip production results.
Chip manufacturers select equipment based on printing accuracy, pattern alignment and service support. They also consider how easily new machines fit into existing production lines. Fact.MR analysis shows that established supplier relationships influence purchases because factories already have experience operating and maintaining these systems.
Which companies are the key providers?
Key companies include ASML Holding N.V.; Nikon Corporation; Canon Inc.; Onto Innovation Inc.; Veeco Instruments Inc.
- ASML Holding N.V.
- Nikon Corporation
- Canon Inc.
- Onto Innovation Inc.
- Veeco Instruments Inc.
Bibliography
- [1]ASML. (2025, March 11). ASML and imec sign strategic partnership agreement to support semiconductor research and sustainable innovation in Europe.
- [2] Nikon Corporation. (2025, July 16). Orders Begin in July for Digital Lithography System DSP-100.
- [3] ASML. (2026, January 28). ASML reports €32.7 billion total net sales and €9.6 billion net income in 2025.
- [4] U.S. Department of Commerce. (2025, June 12). President Trump Secures $200B Investment from Micron Technology for Memory Chip Manufacturing in the United States.
- [5] Nikon Corporation. (2026, June 5). Development of a 1.5 µm Resolution Digital Lithography System.
- [6] Bundesministerium für Wirtschaft und Klimaschutz (BMWK). (2025, February 20). Europäische Kommission genehmigt weiteres deutsches Chips-Act-Projekt: Infineon baut seine Chip-Produktion in Dresden aus [European Commission approves another German Chips Act project: Infineon expands chip production in Dresden].
- [7] Financiadora de Estudos e Projetos (Finep). (2026, September 3). Finep recebe propostas para inovação em semicondutores até 30/9 [Finep receives proposals for semiconductor innovation until September 30].
- [8] The White House. (2025, March 3). Another Historic Investment Secured Under President Trump.
- [9] Department for Business, Innovation, Science and Trade, & Department for Science, Innovation and Technology. (2026, June 8). Semiconductor sector study 2026.
- [10] Ministry of Economy, Trade and Industry. (2025, April 1). Press Conference by Minister Muto (Excerpt).
This Report Answers
- The report explains segmentation by product type, application, end-user, component, and region.
- Segment analysis identifies each leading subsegment and the factors behind its 2026 share.
- Country analysis compares Germany, Brazil, the United States, the United Kingdom, and Japan through investment, policy, costs, and technology needs.
- Competitive analysis reviews current suppliers and legacy corporate names where ownership has changed.
- Technology analysis assesses how DUV, EUV, and i-line systems fit process layers, device categories, and production economics.
What does the Semiconductor Stepper Systems Market cover?
The Semiconductor Stepper Systems Market covers exposure systems used to transfer patterns onto semiconductor wafers and large packaging substrates. It includes DUV, EUV and i-line platforms used in front-end fabrication and selected back-end lithography workflows. These adjacent patterning methods help explain how exposure requirements change as feature sizes and packaging layouts become more demanding. According to Fact.MR analysis, self-assembled lithography provides additional context for emerging patterning methods beyond conventional steppers.
What is included in the scope?
The scope includes new stepper systems sold to foundries, integrated device manufacturers, research fabs and advanced packaging facilities. It covers lenses, light sources, reticle handling, alignment systems, wafer stages and control assemblies when they are sold as part of the exposure platform. Related process equipment is discussed only when it helps explain lithography demand or fab investment timing. As per Fact.MR analysis, semiconductor chemical vapor deposition equipment is an adjacent fab-equipment category shaped by process integration and capacity additions.
What is excluded from the scope?
The scope excludes stand-alone metrology, inspection, deposition, etch, cleaning and material-handling equipment sold without an exposure function. Mask writers and stand-alone electron-beam systems also remain outside the revenue boundary. These categories are referenced only when they help explain the wider process flow around stepper use.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report’s scope and coverage?
Semiconductor Stepper Systems Market Card (14) | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion in 2026 to USD billion by 2036 at a CAGR |
| Market Definition | Semiconductor stepper systems that project circuit patterns onto wafers or large packaging substrates using controlled exposure and alignment. Scope includes DUV, EUV, and i-line systems for semiconductor production. |
| Product Type | DUV Stepper Systems; EUV Stepper Systems; i-Line Stepper Systems |
| Application | Integrated Circuits; MEMS; LED Devices; Others |
| End-User | Foundries; Integrated Device Manufacturers; Others |
| Component | Lens; Light Source; Reticle; Others |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | Germany; Brazil; United States; United Kingdom; Japan |
| Key Companies Profiled | ASML Holding N.V.; Nikon Corporation; Canon Inc.; Onto Innovation Inc.; Veeco Instruments Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using installed lithography capacity, replacement cycles, segment mix, country growth, fab investment, and manufacturer portfolios. |
How is the market segmented?
-
By Product Type
- DUV Stepper Systems
- EUV Stepper Systems
- i-Line Stepper Systems
-
By Application
- Integrated Circuits
- MEMS
- LED Devices
- Others
-
By End-User
- Foundries
- Integrated Device Manufacturers
- Others
-
By Component
- Lens
- Light Source
- Reticle
- Others
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa