- Market Value (2025): USD 4.7 Bn
- Estimated Value (2026): USD 5.1 Bn
- Forecast Value (2036): USD 11.1 Bn
- CAGR (2026-2036): 8.1%
What is the Alu-Free Barrier Cartons Market forecast to be worth by 2036?
USD 5.1 billion in 2026 to USD 11.1 billion by 2036 at an 8.1% CAGR.
- The Alu-Free Barrier Cartons Market reached USD 4.7 billion in 2025.
- Demand is projected to increase from USD 5.1 billion in 2026 to USD 11.1 billion by 2036.
- The market is forecast to record 8.1% CAGR from 2026 to 2036 as carton converters and liquid-food brands qualify foil-free barrier structures.
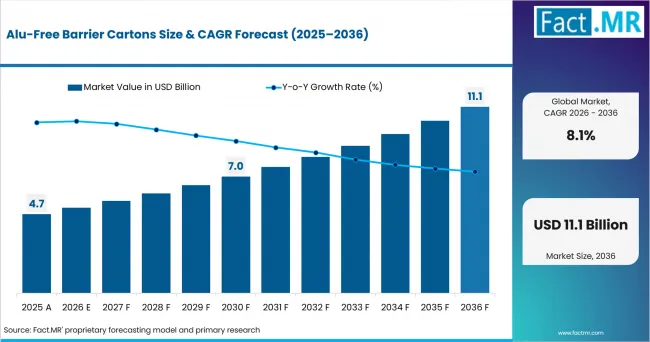
Alu Free Barrier Cartons Value Analysis | Source: Fact.MR
What are the defining numbers behind Alu-Free Barrier Cartons Market growth?
An absolute opportunity of USD 6.0 billion is expected between 2026 and 2036.
- Demand Drivers in the Market
- Beverage brands need foil-free oxygen and light protection for shelf-stable drinks, so aseptic cartons are anticipated to remain the main qualification route.
- Food manufacturers are expected to evaluate polymer-coated paperboard due to its fit with familiar cutting, creasing and filling processes.
- Retail channels need packs that protect liquid foods during transport and storage. Eurostat reported in October 2025 that paper and cardboard formed 40.4% of EU packaging waste in 2023.
- Key Segments Analyzed
- By Barrier Architecture: Polymer-coated paperboard is expected to hold 34.0% share in 2026, supported by converter familiarity and lower changeover risk.
- By Pack Format: Aseptic beverage carton is projected to account for 37.0% share in 2026 since shelf-stable dairy and juice lines need full-barrier performance.
- By Barrier Requirement: Oxygen + light is anticipated to capture 33.0% share in 2026 due to protection needs in milk, alternatives and nutrition drinks.
- By End-use: Dairy / alternatives is estimated to represent 36.0% share in 2026 owing to high use of cartons across milk, plant-based drinks and flavored dairy.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Alu-free cartons are drawing attention where the barrier decision is tied to filling validation and recycling documentation. Demand is expected to expand where brands can retain oxygen and light protection across shelf-stable products. Suppliers need coating depth, aseptic-line compatibility and clear recyclability evidence in the same commercial package.”
- Strategic Implications
- Converters should document coat weight, oxygen barrier and light barrier performance before offering alu-free structures to dairy and beverage brands.
- Carton producers should test foil-free materials on existing aseptic lines so customers see the change as a packaging qualification step.
- Brands should align pack claims with local collection rules given that recyclability language is expected to influence shelf acceptance.
- Coating developers should match barrier chemistry to food-contact rules, filling temperature and the moisture profile of the intended product.
France is forecast to post 8.9% CAGR through 2036, supported by dairy scale and EU packaging design rules. China is projected to record 8.2% CAGR as milk output and shelf-stable beverage channels support aseptic formats. The USA is expected to reach 7.7% CAGR through food manufacturing scale and paperboard container activity. Japan is anticipated to match 7.7% CAGR, reflecting carton use in compact retail formats and domestic board capability. Germany is estimated to record 7.5% CAGR due to ready-meal output and PPWR documentation work.
How does the Alu-Free Barrier Cartons Market break down by segment?
Aseptic beverage carton leads Pack Format at 37.0% share in 2026; Dairy / alternatives leads End-use at 36.0% share.
Which Barrier Architecture dominates?
Polymer-coated paperboard is expected to hold 34.0% share in 2026.
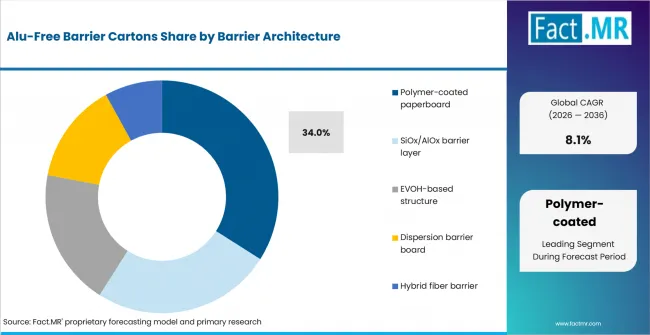
Alu Free Barrier Cartons Analysis By Barrier Architecture | Source: Fact.MR
Polymer-coated paperboard leads by giving converters a familiar way to add barrier performance to carton board. The structure can be cut, creased and sealed with fewer changes than newer multilayer formats. That makes it suitable for early alu-free conversions where brand owners want practical filling trials.
What leads the Pack Format segment?
Aseptic beverage carton is projected to account for 37.0% share in 2026.
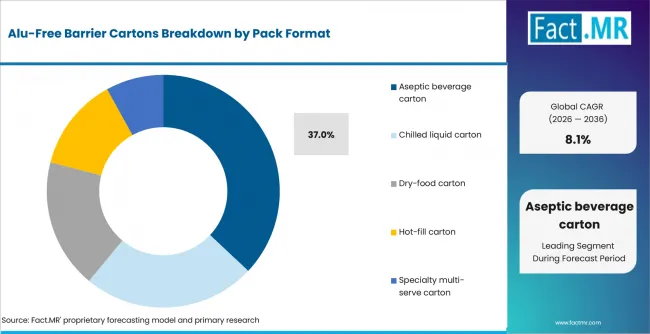
Alu Free Barrier Cartons Analysis By Pack Format | Source: Fact.MR
Aseptic beverage cartons lead through their role in protecting shelf-stable liquids after heat treatment and sealed filling. Their commercial value rises when foil-free structures can protect oxygen-sensitive products while working on existing carton systems. Beverage processors therefore treat alu-free conversion as a package-system decision.
Tetra Pak announced in January 2026 that it is investing EUR 60 million in a new pilot plant in Lund, Sweden, to advance its paper-based barrier technology for aseptic beverage cartons. The facility will support development from barrier creation through packaging material and filled-package production, while the company states that the new solution, when combined with plant-based polymers, can reduce the carton’s carbon footprint by up to 43% compared with the specified reference package.
How does Barrier Requirement shape demand?
Oxygen + light is anticipated to lead with 33.0% share in 2026.
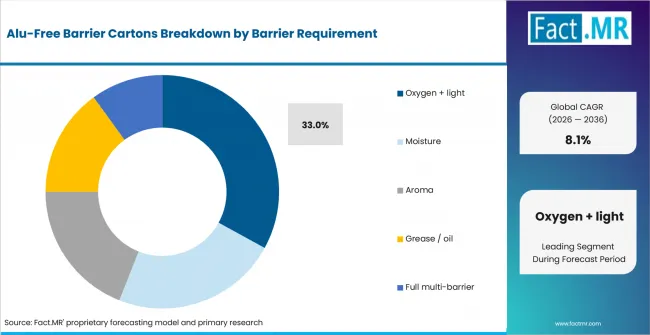
Alu Free Barrier Cartons Analysis By Barrier Requirement | Source: Fact.MR
Oxygen and light protection leads in applications where dairy alternatives, juices and nutrition drinks risk taste or color loss from weak barriers. Aluminum foil historically handled that role in many aseptic cartons. Alu-free designs must therefore prove that polymer, oxide or dispersion layers keep the product stable through storage.
SIG reported on March 17, 2026 that sales of its alu-layer-free aseptic cartons grew 24% year over year in 2025. The growth provides commercial evidence of adoption of aluminum-free aseptic structures, while SIG Terra Alu-free + Full barrier is designed to provide full-barrier protection for oxygen-sensitive beverages and a shelf life of up to 12 months.
What supports Dairy / alternatives within End-use?
Dairy / alternatives is estimated to represent 36.0% share in 2026.
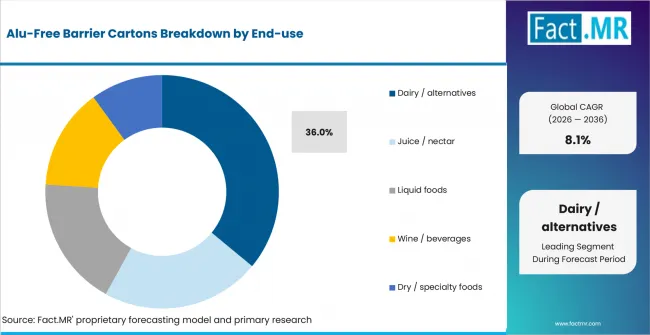
Alu Free Barrier Cartons Analysis By End Use | Source: Fact.MR
Dairy and dairy alternatives lead owing to established carton use across milk, flavored drinks and plant-based beverages. These products need barrier control and clean filling to protect taste. Carton brands can target this end-use first as packaging teams already understand aseptic qualification and retail handling requirements.
Elopak markets Pure-Pak® eSense as an aseptic carton with an aluminium-free barrier for ambient distribution. Elopak lists the format for applications including dairy, plant-based drinks, juice, soup, water and alcoholic beverages, supporting ambient liquid-food applications using an aluminium-free carton structure.
What is accelerating Alu-Free Barrier Cartons Market adoption, and what is holding it back?
Demand is expected to rise through foil removal, recyclability rules and aseptic beverage conversion. Growth is shaped by shelf-life validation, coating cost and recycling-system readiness.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Foil removal in aseptic cartons | +1.4% | Global | Short term (<= 2 years) |
| Recyclability and packaging-design regulation | +1.1% | Europe, North America | Medium term (2-4 years) |
| Dairy and alternative beverage carton conversion | +0.9% | Asia, Europe, North America | Medium term (2-4 years) |
| Paperboard converter investment in barrier coatings | +0.7% | Global | Long term (>= 4 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Full-barrier multi-serve aseptic cartons | +1.0% | Global | Short term (<= 2 years) |
| Dispersion and oxide layers for recyclable board | +0.8% | Europe, East Asia | Medium term (2-4 years) |
| Dry and specialty food carton extensions | +0.5% | Global | Long term (>= 4 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Shelf-life and sensory validation burden | -0.6% | Global | Short term (<= 2 years) |
| Coating and line-qualification cost | -0.4% | Europe, Asia | Medium term (2-4 years) |
| Recycling-claim and collection variation | -0.3% | North America, Europe | Long term (>= 4 years) |
Which countries are scaling the Alu-Free Barrier Cartons Market through 2036?
- The country comparison spans 1.4 percentage points and forms a narrow growth range across the forecast period.
- France remains 0.7 percentage point above China through dairy scale and EU packaging design rules.
- China remains 0.5 percentage point above the USA through milk output and shelf-stable beverage scale.
- The USA and Japan both hold 7.7% CAGR, with the USA linked to food manufacturing and Japan tied to paperboard capability.
- Germany closes the displayed range through ready-meal output and PPWR documentation work.
Comparable CAGRs are expected to create different entry conditions across dairy processing, beverage retail and packaging regulation. Filling-line validation and paperboard availability are expected to shape the entry route by country. Full report coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Middle East & Africa.
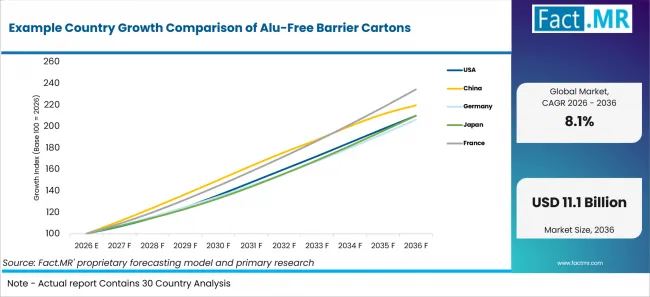
Example Country Growth Comparison Of Alu Free Barrier Cartons | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| United States | 7.7% |
| China | 8.2% |
| Germany | 7.5% |
| Japan | 7.7% |
| France | 8.9% |
What supports USA adoption?
7.7% CAGR, supported by food manufacturing scale and paperboard container activity.
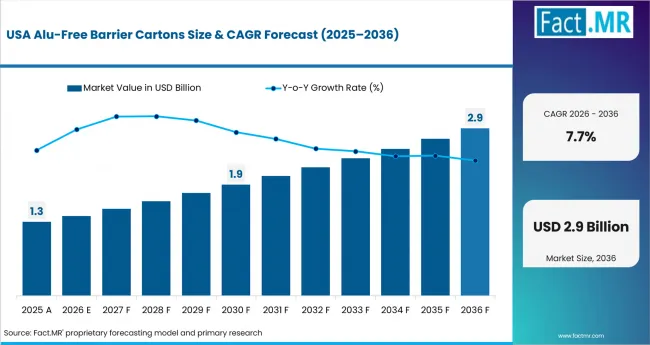
Alu Free Barrier Cartons Country Value Analysis | Source: Fact.MR
The U.S. Census Bureau reported in September 2026 that the estimated value of shipments for U.S. food manufacturing reached USD 1,054.3 billion in 2024. That processing base is expected to support alu-free carton trials across dairy alternatives, shelf-stable beverages and liquid foods where carton formats already fit filling and retail systems.
How is China scaling demand?
8.2% CAGR, driven by milk output and shelf-stable beverage demand.
China’s National Bureau of Statistics reported in February 2026 that milk output reached 40.91 million tons in 2025. That dairy base is expected to support aseptic carton demand as brands evaluate foil-free full-barrier structures for long shelf-life drinks and multipack retail channels.
What supports Germany’s adoption?
7.5% CAGR, backed by prepared-food output and European packaging rules.
Destatis reported in January 2026 that Germany produced 1.7 million tons of ready meals worth EUR 5.9 billion in 2024. That packaged-food activity is expected to support moisture and aroma barrier cartons where converters need fiber-based structures aligned with EU packaging rules.
How does Japan perform?
7.7% CAGR, led by retail scale and domestic paperboard capability.
The Japan Paper Association reported in 2026 that paper and paperboard production reached 21.1 million tons in 2025. That supply base is expected to support compact liquid-food and dry-food cartons where portion size, package handling and shelf stability influence material selection.
What supports France adoption?
8.9% CAGR, supported by dairy collection and beverage manufacturing.
Agreste's revised 2026 annual dairy survey reports that metropolitan France collected 23.1 billion liters of cow milk in 2024. That dairy volume is expected to support alu-free carton evaluation as beverage and dairy processors seek packages that preserve oxygen and light protection under EU recyclability rules.
Who leads the Alu-Free Barrier Cartons Market?
SIG, Tetra Pak, and Elopak are directly relevant through aluminum-layer-free or paper-based-barrier aseptic carton technologies. SIG commercializes alu-layer-free full-barrier aseptic cartons, while Tetra Pak has introduced a paper-based barrier designed to replace the traditional aluminum foil layer in aseptic cartons. Elopak offers its aluminum-free Pure-Pak eSense aseptic carton. Greatview Aseptic Packaging, Nippon Paper Industries, and Ecolean participate more broadly across fiber-based and barrier-packaging materials.
Competition in aluminum-free aseptic cartons is increasingly linked to maintaining barrier performance, shelf life, and compatibility with filling and sealing equipment while increasing the fiber or renewable-material content of the package. Commercial solutions from SIG, Tetra Pak, and Elopak demonstrate different approaches to removing or replacing the conventional aluminum barrier layer while preserving the functionality required for dairy, juice, and other ambient liquid-food applications.
Which companies are the key providers?
Key companies include SIG; Tetra Pak; Elopak; Greatview Aseptic Packaging; Nippon Paper Industries; and Ecolean.
- SIG
- Tetra Pak
- Elopak
- Greatview Aseptic Packaging
- Nippon Paper Industries
- Ecolean
Bibliography
- Calvino, A. (2026, March 10). Enquête annuelle laitière 2024. Agreste.
- Directorate-General for Environment. (2025, February 11). New rules enter into force for a more sustainable and competitive packaging economy. European Commission.
- Eurostat. (2025, October 22). Plastic packaging waste in the EU: 35.3 kg per person.
- National Bureau of Statistics of China. (2026, February 28). Statistical communiqué of the People's Republic of China on the 2025 national economic and social development.
- SIG. (2025, May 20). SIG launches world’s-first alu layer-free full barrier solution for multi-serve aseptic cartons, further reducing carbon footprint by up to 61%.
- SIG. (2026, March 17). 24% sales growth: SIG’s alu-layer-free aseptic cartons gained widespread adoption in 2025.
- Statistisches Bundesamt. (2026, January 14). Produktion von Fertiggerichten binnen fünf Jahren mengenmäßig um 25,6 % gestiegen.
- Stora Enso. (2026, April 30). Stora Enso launches Performa Natura Aqua, a dispersion-coated board for foodservice and bakery packaging.
- Tetra Pak. (2026, January 26). Tetra Pak invests €60 million in This Report Answersowned pilot plant to advance its paper-based barrier technology development.
- U.S. Census Bureau. (2026, September 3). Census Bureau releases new Annual Integrated Economic Survey data.
This Report Answers
- The report explains where alu-free barrier cartons are used across barrier architecture and pack format. It also covers barrier requirement and end-use segmentation.
- Segment analysis identifies the leading subsegments and the operating reasons converters prioritize them.
- Country analysis examines the listed markets and the dairy, beverage, paperboard or policy mechanisms supporting carton conversion.
- Competitive analysis reviews current providers across aseptic cartons, paperboard, barrier coatings and fiber-led packaging materials.
- Application analysis assesses how oxygen, light, moisture and aroma protection influence material qualification decisions.
What does the Alu-Free Barrier Cartons Market cover?
The Alu-Free Barrier Cartons Market covers carton structures that replace aluminum foil with polymer, oxide, dispersion or hybrid fiber barriers. The assessment includes aseptic packaging, paper packaging materials and folding carton packaging where these categories overlap with food and beverage carton conversion.
The assessment covers aseptic beverage cartons, chilled liquid cartons, hot-fill cartons and specialty multi-serve cartons. It also reviews adjacent paper barrier coatings and barrier paper technologies where coating performance affects carton design.
What is included in the scope?
The scope includes aluminum-layer-free barrier cartons used for dairy, plant-based beverages, juices, liquid foods and selected dry foods. It includes coated paperboard structures, oxide barrier layers, EVOH-based structures, dispersion barrier board and hybrid fiber barriers used in carton applications.
It includes suppliers that provide carton systems, board, coatings or paper-led barrier materials. The scope aligns with related coverage of paper coating materials, next-gen paper-based and fiber-based packaging and bio barrier coatings where the material boundary touches fiber cartons.
What is excluded from the scope?
The scope excludes conventional foil-based cartons, metal cans, glass bottles, rigid plastic bottles and flexible pouches where carton board is outside the pack structure. It also excludes generic zero waste packaging claims unless the package uses an alu-free barrier carton format.
It excludes stand-alone coatings sold only for non-carton use and packaging formats centered on bottles or tubs. Adjacent areas such as mono-material barrier bottles and mineral oil barrier coatings are covered only when they inform carton-board barrier choices.
How Was the Analysis Built?
The analysis draws on 120+ public inputs, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational issues, approval requirements, competitive positioning, and factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative material. Every public input used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report’s scope and coverage?
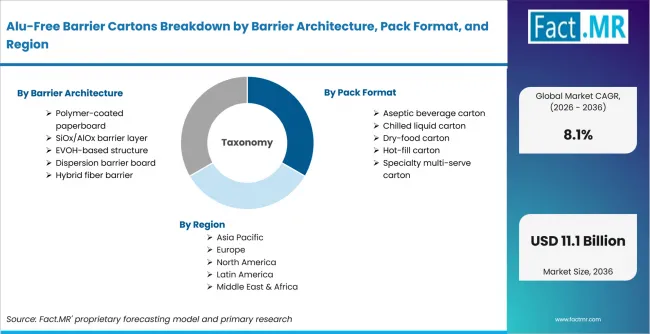
Alu Free Barrier Cartons Breakdown By Barrier Architecture, Pack Format, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Aluminum-layer-free barrier carton structures used for liquid, chilled, dry and specialty food packaging where polymer, oxide, dispersion or hybrid fiber barriers replace aluminum foil layers. |
| Barrier Architecture | Polymer-coated paperboard; SiOx/AlOx barrier layer; EVOH-based structure; Dispersion barrier board; Hybrid fiber barrier |
| Pack Format | Aseptic beverage carton; Chilled liquid carton; Dry-food carton; Hot-fill carton; Specialty multi-serve carton |
| Barrier Requirement | Oxygen + light; Moisture; Aroma; Grease / oil; Full multi-barrier |
| End-use | Dairy / alternatives; Juice / nectar; Liquid foods; Wine / beverages; Dry / specialty foods |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | United States; China; Germany; Japan; France |
| Key Companies Profiled | SIG; Tetra Pak; Elopak; Greatview Aseptic Packaging; Nippon Paper Industries; Ecolean |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using liquid carton demand, paperboard converter activity, barrier-material qualification, end-use packaging need, country indicators and provider portfolio review. |
How is the market segmented?
-
By Barrier Architecture
- Polymer-coated paperboard
- SiOx/AlOx barrier layer
- EVOH-based structure
- Dispersion barrier board
- Hybrid fiber barrier
-
By Pack Format
- Aseptic beverage carton
- Chilled liquid carton
- Dry-food carton
- Hot-fill carton
- Specialty multi-serve carton
-
By Barrier Requirement
- Oxygen + light
- Moisture
- Aroma
- Grease / oil
- Full multi-barrier
-
By End-use
- Dairy / alternatives
- Juice / nectar
- Liquid foods
- Wine / beverages
- Dry / specialty foods
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa

