- Market Value (2025): USD 11.2 Bn
- Estimated Value (2026): USD 12.8 Bn
- Forecast Value (2036): USD 48.7 Bn
- CAGR (2026-2036): 14.3%
What is the Digital Collectible Market forecast to be worth by 2036?
USD 12.8 billion in 2026 to USD 48.7 billion by 2036 at a 14.3% CAGR.
- The Digital Collectible Market surpassed a value of USD 11.2 billion in 2025.
- Demand is projected to increase from USD 12.8 billion in 2026 to USD 48.7 billion by 2036.
- The market is forecast to record 14.3% CAGR from 2026 to 2036 as collectors use blockchain records to verify scarcity.
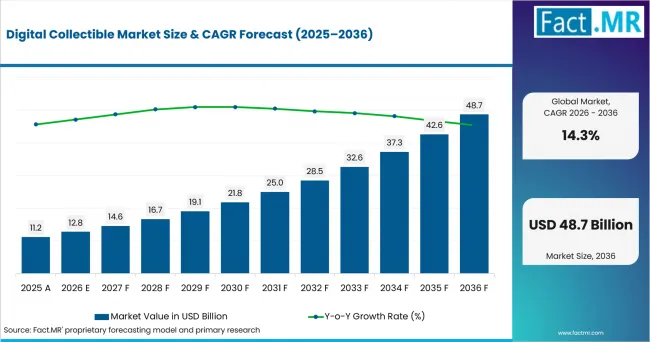
Digital Collectible Market Value Analysis | Source: Fact.MR
What are the defining numbers behind Digital Collectible Market growth?
An absolute opportunity of USD 35.9 billion is expected between 2026 and 2036.
- Demand Drivers in the Market
- Collectors need visible scarcity because resale confidence weakens when ownership records are unclear.
- Gaming communities value identity items tied to accounts, rankings and repeat platform activity.
- The U.S. Census Bureau estimated USD 340.2 billion in seasonally adjusted U.S. retail e-commerce sales for the second quarter of 2026.
- ESA's February 11, 2026 release, updated following a March 2026 data restatement, gives final 2025 U.S. consumer spending on video games of USD 60.8 billion.
- Key Segments Analyzed
- By Product: Gaming Collectibles are expected to hold 36.8% share in 2026 because game assets give collectors use beyond display.
- By Blockchain Network: Ethereum Based Collectibles are projected to account for 42.5% share in 2026 supported by wallet and marketplace familiarity.
- By Asset Standard: ERC 721 Assets are anticipated to capture 51.6% share in 2026 owing to their simple one-token-one-asset structure.
- By Platform Type: Marketplace Platforms are estimated to represent 48.7% share in 2026 due to search, listing and resale tools in one venue.
- By End User: Collectors are forecast to hold 29.4% share in 2026 supported by licensed releases and completion-based buying behavior.
- By Payment Method: Cryptocurrency Payments are expected to hold 67.8% share in 2026 because wallet-native checkout remains common across blockchain platforms.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, "Digital collectibles are being judged less by token novelty and more by collectible discipline. Scarcity, licensing, custody and resale history are expected to define which platforms keep user trust. Providers should combine clear ownership records, simple payment routes and brand-safe drop design."
- Strategic Implications
- Marketplace operators should publish mint counts, royalty terms and resale histories beside checkout.
- Game publishers should link collectibles to simple in-game utility without confusing casual users.
- Sports platforms should protect licensed clips with clear rights language and stable access.
- Payment teams should keep crypto checkout and give fiat users a short route into drops.
Germany is expected to record 16.5% CAGR through 2036 supported by online-shopping depth and EU crypto rules. Brazil is projected to post 15.0% CAGR as Pix familiarity widens digital payment behavior. The USA is anticipated to reach 13.6% CAGR due to e-commerce scale. The UK is estimated to advance at 12.2% CAGR while regulation improves platform boundaries. Japan is forecast to reach 10.7% CAGR as online games support digital purchases.
How does the Digital Collectible Market break down by segment?
Gaming Collectibles lead Product at 36.8% share in 2026; Cryptocurrency Payments lead Payment Method at 67.8% share.
Which Product dominates?
Gaming Collectibles are expected to hold 36.8% share in 2026.
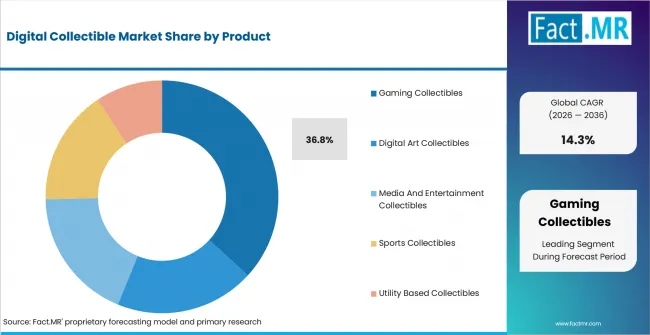
Digital Collectible Market Analysis By Product | Source: Fact.MR
Gaming Collectibles lead because players use scarce digital items to express identity, status and participation within gaming communities. Limited skins, cards and similar assets combine collectibility with in-game utility, while virtual items remain tied to platform activity. This supports repeat demand from players seeking ownership, rarity and recognizable digital assets.
What leads the Blockchain Network segment?
Ethereum Based Collectibles are projected to account for 42.5% share in 2026.
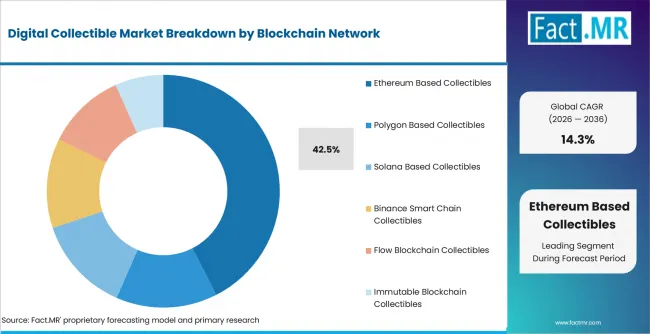
Digital Collectible Market Analysis By Blockchain Network | Source: Fact.MR
Ethereum Based Collectibles lead because established wallets, marketplaces and token infrastructure support broad user familiarity and trading activity. Ethereum remains central to collectible issuance, while Polygon offers lower-cost transactions and Flow supports sports-oriented content. This ecosystem depth strengthens creator participation, secondary-market activity and accessibility across digital collectible applications.
How does Asset Standard shape demand?
ERC 721 Assets are anticipated to capture 51.6% share in 2026.
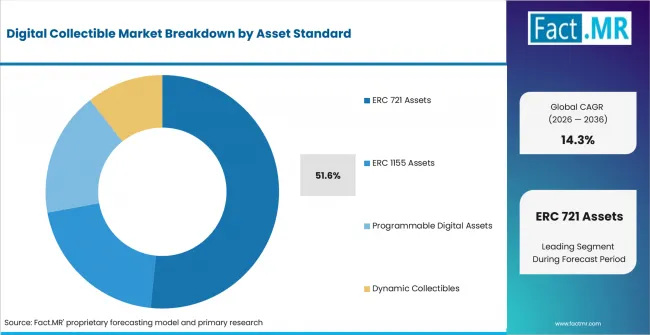
Digital Collectible Market Analysis By Asset Standard | Source: Fact.MR
ERC 721 Assets lead because the standard is designed around individually identifiable digital assets, making it suitable for unique collectibles. ERC 1155 supports mixed editions and multiple token types, while programmable assets add dynamic traits. Clear ownership structures and broad platform compatibility continue to support ERC 721 adoption across collectible ecosystems.
What supports Marketplace Platforms within Platform Type?
Marketplace Platforms are estimated to represent 48.7% share in 2026.
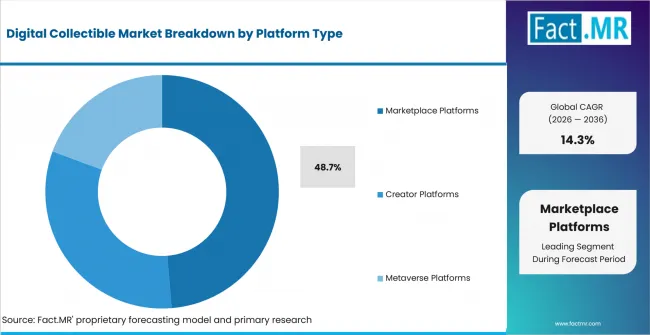
Digital Collectible Market Analysis By Platform Type | Source: Fact.MR
Marketplace Platforms lead because collectors need centralized discovery, purchasing and resale access across multiple digital asset categories. These platforms simplify browsing and transaction activity, while curated and brand-owned venues help maintain quality and relevance. Strong marketplace visibility also supports creator reach, community engagement and repeat trading across collectible ecosystems.
What supports Collectors within End User?
Collectors are forecast to hold 29.4% share in 2026.
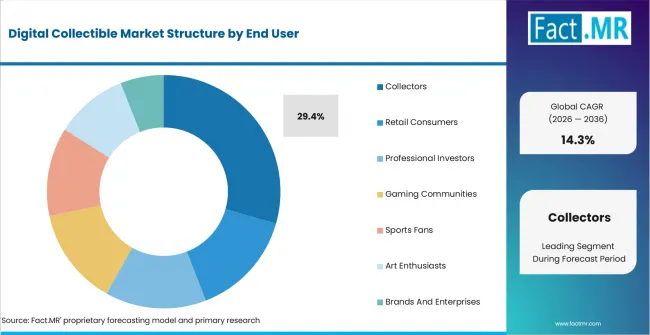
Digital Collectible Market Analysis By End User | Source: Fact.MR
Collectors lead because scarcity, rarity and completion goals strongly influence purchasing behavior across digital collectible categories. Gaming communities, sports fans and entertainment audiences support repeat drops when assets connect with recognizable properties or experiences. Ownership visibility and secondary-market activity further encourage continued participation among users seeking distinctive digital collections.
What leads Payment Method demand?
Cryptocurrency Payments are expected to hold 67.8% share in 2026.
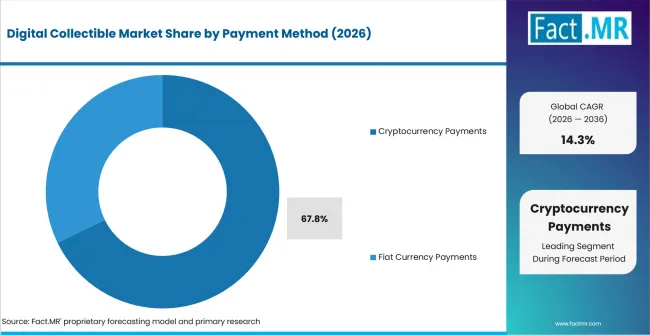
Digital Collectible Market Analysis By Payment Method | Source: Fact.MR
Cryptocurrency Payments lead because token purchases, wallet custody and blockchain transactions remain closely connected across digital collectible platforms. Crypto-based settlement supports direct participation in decentralized marketplaces, while fiat, card and digital-wallet options remain important for licensed collectible buyers. Broader payment choice can also reduce entry barriers for new users.
What is accelerating Digital Collectible Market adoption, and what is holding it back?
Licensed scarcity drives it; fraud and regulatory risk restrain it.
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Licensed sports and entertainment drops | +1.9% | North America, Europe | Short term (<= 2 years) |
| Game-linked ownership and avatar identity | +1.5% | Global | Medium term (2-4 years) |
| Marketplace resale and price discovery | +1.2% | North America, East Asia | Medium term (2-4 years) |
| Wallet-native and fiat payment access | +0.9% | Global | Short term (<= 2 years) |
- Licensed sports and entertainment drops: Recognized leagues, teams, studios and entertainment properties give digital collectibles a familiar reference point. Repeat releases can gain stronger traction when ownership terms, edition sizes and scarcity rules remain clear to buyers.
- Game-linked ownership and avatar identity: Games encourage users to value skins, cards, avatars and other digital objects as part of identity and participation. Adoption can increase when collectible ownership adds utility, progression benefits or personalization within gameplay.
- Marketplace resale and price discovery: Digital marketplaces turn collectibles into searchable inventory and support secondary trading. Resale access can improve liquidity, visibility and price discovery while encouraging collectors to remain active across multiple releases and asset categories.
- Wallet-native and fiat payment access: Crypto checkout aligns with blockchain-native collectors, while fiat, card and digital-wallet options broaden access for mainstream users. Flexible payment routes can reduce entry barriers and make licensed digital collectibles easier to purchase across different user groups.
Opportunity Impact Analysis
| Opportunity | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Fiat checkout for licensed collectibles | +1.1% | USA, UK, Japan | Short term (<= 2 years) |
| Sports and fantasy-linked assets | +0.9% | USA, Brazil, Europe | Medium term (2-4 years) |
| Interoperable marketplace listings | +0.8% | Global | Long term (>= 4 years) |
- Fiat checkout for licensed collectibles: Card and digital-wallet payment options reduce the need for users to set up cryptocurrency before purchasing. Platforms that simplify checkout and shorten technical steps can improve accessibility, conversion and participation among mainstream buyers entering digital collectible ecosystems.
- Sports and fantasy-linked assets: Sports collectibles can gain relevance when assets connect with season events, rookies, team performance or fan milestones. Limited releases and reward structures tied to recognizable sports moments can strengthen repeat engagement and encourage collectors to follow assets throughout a season.
- Interoperable marketplace listings: Bridge tools and self-custody options can make digital ownership feel less restricted to a single marketplace. Greater interoperability can improve portability, resale flexibility and user control while supporting broader movement of collectibles across compatible platforms and wallet environments.
Restraints Impact Analysis
| Restraint | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Crypto scam and fraud exposure | -0.8% | USA, UK, Global | Short term (<= 2 years) |
| Unclear custody and platform continuity | -0.6% | Global | Medium term (2-4 years) |
| Regulatory onboarding burden | -0.5% | Europe, UK, Brazil | Medium term (2-4 years) |
- Crypto scam and fraud exposure: Fraud concerns can make mainstream users cautious about connecting wallets or completing blockchain-based purchases. Platforms therefore need clear security practices, trusted payment flows and user education to build confidence around digital collectible transactions.
- Unclear custody and platform continuity: Users need confidence that purchased digital assets will remain accessible when platforms change ownership, technology or operating models. Clear migration plans, custody options and continuity policies can reduce uncertainty and strengthen trust in long-term collectible ownership.
- Regulatory onboarding burden: Compliance reviews can add friction for platforms that combine collectibles with token-based payments or blockchain features. Identity checks, promotional requirements and financial-services rules may increase onboarding complexity, making streamlined compliance processes important for maintaining user conversion and platform accessibility.
Which countries are scaling the Digital Collectible Market through 2036?
- The country comparison spans 5.8 percentage points between Germany and Japan.
- Germany remains 1.5 percentage points above Brazil as online shopping and EU crypto rules support platforms.
- Brazil remains 1.4 percentage points above the USA because internet access and Pix lower purchase barriers.
- The USA remains 1.4 percentage points above the UK due to e-commerce scale and sports communities.
- The UK remains 1.5 percentage points above Japan while crypto regulation clarifies platform boundaries.
- Japan closes the displayed range as online games support digital spending and crypto oversight shapes onboarding.
Comparable CAGRs create different entry conditions because payment habits and crypto rules vary by country. Full coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Middle East & Africa.
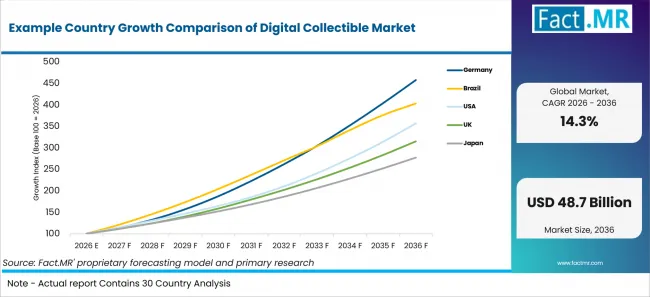
Example Country Growth Comparison Of Digital Collectible Market | Source: Fact.MR
| Country | CAGR |
|---|---|
| Germany | 16.5% |
| Brazil | 15.0% |
| USA | 13.6% |
| UK | 12.2% |
| Japan | 10.7% |
What supports Germany adoption?
16.5% CAGR, supported by online shopping depth and regulated crypto-asset access.
Destatis reported that just over 83% of Germans aged 16–74, representing around 52 million people, had purchased or ordered something online in 2024. Deutsche Bundesbank reported that German households’ financial assets totaled EUR 9,504 billion at the end of 2025. MiCA establishes EU-wide safeguards for the custody and administration of crypto-assets, including requirements for asset segregation, custody policies and protection of client ownership rights.
How is Brazil scaling demand?
15.0% CAGR, driven by internet access and instant-payment behavior.
IBGE reported in July 2026 that 168.7 million Brazilians aged 10 years or older used the Internet during the previous three-month reference period in 2025. Brazil’s Ministry of Finance, citing Central Bank data, reported that Pix recorded almost 80 billion transactions in 2025. Mobile-first payment behavior supports low-ticket collectibles linked to gaming, music, football and creator communities.
What supports USA growth?
13.6% CAGR, backed by e-commerce scale and licensed sports collectibles.
The U.S. Census Bureau estimated seasonally adjusted U.S. retail e-commerce sales at USD 340.2 billion in the second quarter of 2026, while ESA reported final 2025 U.S. consumer spending on video games of USD 60.8 billion. Dapper Labs (NBA Top Shot) extends licensed NBA content into limited-edition digital collectibles, while its marketplace enables collectors to buy, sell and trade digital Moments and view active listings and transaction activity.
How does the UK perform?
12.2% CAGR, led by cryptoasset regulation and mainstream online retail.
ONS reported that internet sales accounted for 27.4% of Great Britain retail sales in 2025, while FCA research found that 25% of cryptoasset users would be more likely to invest if cryptocurrencies were more regulated in the UK. Card-based checkout, accessible wallet infrastructure and established licensed entertainment properties may help broaden access to digital collectibles.
What underpins Japan adoption?
10.7% CAGR, supported by online games and selective crypto oversight.
METI reported that Japan’s domestic B-to-C e-commerce market reached JPY 26.1 trillion in 2024, while the FSA reported that crypto-asset exchange accounts exceeded 12 million by the end of January 2025. Japan’s established online-gaming, digital-content and collecting ecosystems may provide familiar channels for engagement with virtual assets.
Who leads the Digital Collectible Market?
VeVe Digital Collectibles and Dapper Labs (NBA Top Shot) are prominent licensed-digital-collectible platforms covered in this report, while Panini America and Sorare add sports-linked digital collectible offerings.
VeVe Digital Collectibles is active through licensed digital comics, 3D collectibles and its marketplace. In November 2025, VeVe Digital Collectibles announced migration to Collect while keeping its app, showrooms and drop schedule in place.
Dapper Labs (NBA Top Shot) competes through licensed basketball Moments. Panini America supports digital trading cards and Ethereum bridging. Candy Digital, Sorare, The Topps Company / Topps Digital broaden competition across sports and game-linked collectibles.
Which companies are the key providers?
Key companies include VeVe Digital Collectibles, Dapper Labs (NBA Top Shot), Mattel, Inc. (Mattel Creations), Panini America, Candy Digital, Sorare, and The Topps Company / Topps Digital.
- VeVe Digital Collectibles
- Dapper Labs (NBA Top Shot)
- Mattel, Inc. (Mattel Creations)
- Panini America
- Candy Digital
- Sorare
- The Topps Company / Topps Digital
Bibliography
- U.S. Census Bureau. (2026, August 18). Quarterly retail e-commerce sales.
- Federal Bureau of Investigation. (2026, April 6). Cryptocurrency and AI scams bilk Americans of billions.
- Entertainment Software Association. (2026, February 11). 2025 U.S. consumer spending on video games nears pandemic-level peak at $60.7 billion, second-highest on record.
- Statistisches Bundesamt (Destatis). (2024, November 28). 83 % der 16- bis 74-Jährigen kaufen online ein.
- Deutsche Bundesbank. (2026, April 16). Acquisition of financial assets and external financing in Germany in the fourth quarter of 2025.
- Instituto Brasileiro de Geografia e Estatística. (2026, July 2). Proportion of Internet users in Brazil exceeded 90% of population aged 10 or over, in 2025.
- Ministério da Fazenda. (2026, August 19). Pix consolida liderança nos pagamentos digitais e projeta novas evoluções até 2030.
- Comissão de Valores Mobiliários. (2025, December 16). CVM emite 175 ofícios de alerta e 11 stop orders no 3º trimestre de 2025.
- Financial Conduct Authority. (2025, February 7). FCA steps up action against misleading financial adverts.
- Ministry of Economy, Trade and Industry. (2025, August 26). Results of FY2024 E-Commerce Market Survey Compiled.
- Financial Services Agency. (2025, July 4). Publication of discussion paper: “Examination of the regulatory systems related to cryptoassets”.
- NBA Top Shot. (2025, October 21). The 2025–26 NBA Top Shot Roadmap: The New Era Starts Now.
- Panini America. (2025, August 8). Panini Blockchain builds a bridge. The Knight’s Lance.
- VeVe. (2025, November 19). Introducing Collect: The Next Era of Digital Collecting.
This Report Answers
- The report explains where digital collectibles are used across product and blockchain network. It covers asset standard, platform type and payment method.
- Segment analysis identifies the leading subsegments and collector priorities.
- Country analysis examines Germany, Brazil, the USA, the UK and Japan.
- Competitive analysis reviews VeVe Digital Collectibles, Dapper Labs (NBA Top Shot), Panini America and other providers.
- Application analysis assesses how scarcity, licensing and wallet access influence buying decisions.
What does the Digital Collectible Market cover?
The Digital Collectible Market covers blockchain-recorded assets that represent scarce digital ownership across games, sports, art, media and loyalty use cases.
The assessment covers digital objects built for collection, access or exchange. Ordinary downloads and generic tokens remain outside scope unless ownership and scarcity define the offer.
What is included in the scope?
The scope includes blockchain-recorded digital collectibles used across gaming, digital art, media and entertainment, sports, and utility-based applications. It covers assets designed for collection, display, access, resale, or fan engagement where ownership records and scarcity are central to the offering.
It includes Ethereum-, Polygon-, Solana-, Binance Smart Chain-, Flow-, and Immutable-based collectibles; ERC 721 and ERC 1155 assets; programmable and dynamic collectibles; marketplace, creator, brand-owned, and metaverse platforms; and cryptocurrency, fiat, card, and digital-wallet payment routes serving collectors, gaming communities, sports fans, art enthusiasts, and brands.
What is excluded from the scope?
The scope leaves out ordinary downloadable media, general cryptocurrency trading and securities tokens. Physical collectibles remain outside scope unless a digital ownership layer is sold with them.
It leaves out gambling tokens and unlicensed entertainment copies. A platform is included only where the asset carries collectible value and the purchase record is central.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report's scope and coverage?
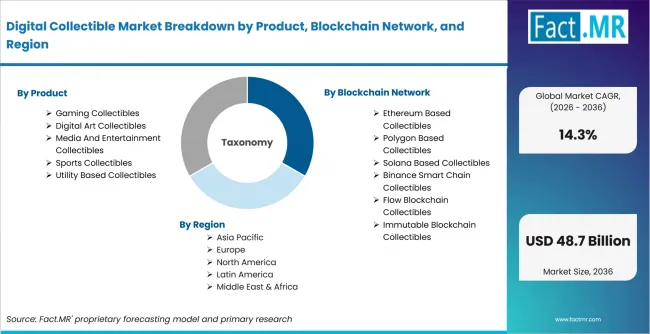
Digital Collectible Market Breakdown By Product, Blockchain Network, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Blockchain-recorded assets issued for collection, display, access, resale or fan engagement across media, games, art and sports. |
| Product | Gaming Collectibles; Digital Art Collectibles; Media And Entertainment Collectibles; Sports Collectibles; Utility Based Collectibles |
| Blockchain Network | Ethereum Based Collectibles; Polygon Based Collectibles; Solana Based Collectibles; Binance Smart Chain Collectibles; Flow Blockchain Collectibles; Immutable Blockchain Collectibles |
| Asset Standard | ERC 721 Assets; ERC 1155 Assets; Programmable Digital Assets; Dynamic Collectibles |
| Platform Type | Marketplace Platforms; Creator Platforms; Brand Owned Platforms; Metaverse Platforms |
| End User | Collectors; Retail Consumers; Professional Investors; Gaming Communities; Sports Fans; Art Enthusiasts; Brands And Enterprises |
| Payment Method | Cryptocurrency Payments; Fiat Currency Payments; Credit And Debit Card Payments; Digital Wallet Payments |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | Germany; Brazil; USA; UK; Japan |
| Key Companies Profiled | VeVe Digital Collectibles, Dapper Labs (NBA Top Shot), Mattel, Inc. (Mattel Creations), Panini America, Candy Digital, Sorare, and The Topps Company / Topps Digital |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using platform activity, drop formats, payment pathways and provider portfolio review. |
How is the market segmented?
-
By Product
- Gaming Collectibles
- In Game Assets
- Virtual Trading Cards
- Virtual Land And Metaverse Assets
- Digital Art Collectibles
- Static Digital Artwork
- Animated Digital Artwork
- Generative Art
- Media And Entertainment Collectibles
- Music Collectibles
- Video Collectibles
- Celebrity Collectibles
- Sports Collectibles
- Player Memorabilia
- Event Collectibles
- Fantasy Sports Assets
- Utility Based Collectibles
- Membership Collectibles
- Ticketing Collectibles
- Loyalty Collectibles
- Gaming Collectibles
-
By Blockchain Network
- Ethereum Based Collectibles
- Polygon Based Collectibles
- Solana Based Collectibles
- Binance Smart Chain Collectibles
- Flow Blockchain Collectibles
- Immutable Blockchain Collectibles
-
By Asset Standard
- ERC 721 Assets
- ERC 1155 Assets
- Programmable Digital Assets
- Dynamic Collectibles
-
By Platform Type
- Marketplace Platforms
- Open Marketplaces
- Curated Marketplaces
- Creator Platforms
- Artist Driven Platforms
- Brand Owned Platforms
- Metaverse Platforms
- Social Metaverse Platforms
- Gaming Metaverse Platforms
- Marketplace Platforms
-
By End User
- Collectors
- Retail Consumers
- Professional Investors
- Gaming Communities
- Sports Fans
- Art Enthusiasts
- Brands And Enterprises
-
By Payment Method
- Cryptocurrency Payments
- Ethereum Payments
- Stablecoin Payments
- Fiat Currency Payments
- Credit And Debit Card Payments
- Digital Wallet Payments
- Cryptocurrency Payments
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa