- Market Value (2025): USD 464.3 Mn
- Estimated Value (2026): USD 525.6 Mn
- Forecast Value (2036): USD 1816.0 Mn
- CAGR (2026-2036): 13.2%
What is the Dynamic Line Rating (DLR) Sensor Market forecast to be worth by 2036?
USD 525.6 million in 2026 to USD 1816.0 million by 2036 at a 13.2% CAGR.
- The Dynamic Line Rating (DLR) Sensor Market was approximately USD 464.3 million in 2025.
- Demand is projected to increase from USD 525.6 million in 2026 to USD 1816.0 million by 2036.
- The market is forecast to expand at a 13.2% CAGR from 2026 to 2036.
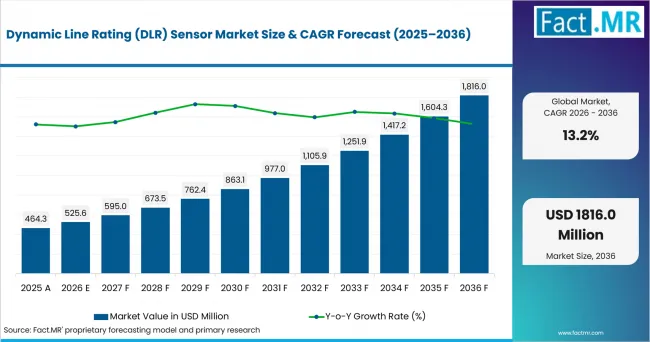
Dynamic Line Rating (dlr) Sensor Market Value Analysis | Source: Fact.MR
What are the defining numbers behind Dynamic Line Rating (DLR) Sensor Market growth?
An absolute opportunity of USD 1290.4 million is expected between 2026 and 2036.
- Demand Drivers in the Market
- Transmission operators are seeking more usable capacity from existing overhead lines as electrification and renewable generation increase power flows. The U.S. Department of Energy defines dynamic line rating as hardware and software that updates the capacity of existing lines in real time, and notes that favorable cold or windy conditions can allow substantially more transfer than conservative nameplate limits. This creates demand for sensors that measure the conditions needed to calculate safe ampacity.
- Regulation is moving line ratings toward more frequent use of weather-responsive operating limits. FERC Order No. 881 requires ambient-adjusted ratings for near-term transmission service, while the Commission has also examined broader use of DLR inputs such as wind and solar heating. Utilities therefore need dependable weather, conductor, and communications data that can feed rating calculations and control-room processes.
- Grid congestion and renewable curtailment increase the value of real-time line awareness. The U.S. Department of Energy includes DLR among grid-enhancing technologies that can defer conventional upgrades and support renewable integration by making better use of existing transmission corridors. Sensor deployments become easier to justify where a constrained line limits interconnection or forces redispatch.
- Retrofit deployment lowers the barrier to adoption because line-mounted and tower-mounted sensors can be added to existing circuits without rebuilding the full corridor. In a U.S. Department of Energy demonstration, Oncor installed DLR technology across eight transmission circuits using field sensors, radio receivers, and a central transmission management system. This operating model supports demand for modular sensor packages that connect with existing utility infrastructure.
- Utilities increasingly want rating data to flow into energy-management and asset-health systems rather than remain in standalone dashboards. Current DLR platforms combine conductor temperature, sag or tension, current, local weather, and remote communications with forecasting and SCADA or EMS integration. This extends the purchasing case from capacity optimization into condition monitoring, outage prevention, and maintenance planning.
- Key Segments Analyzed
- Weather Based Sensors account for 22.6% of Sensor Type in 2026 because wind, ambient temperature, and solar heating directly influence the thermal capacity of overhead conductors.
- Retrofit Installations account for 36.8% of Installation Type in 2026 as utilities can add DLR capability to constrained lines without waiting for full reconductoring or new corridor construction.
- Transmission Lines account for 56.2% of Line Type in 2026 because capacity constraints on high-voltage corridors have a direct effect on power transfer, congestion, and renewable interconnection.
- Wireless accounts for 59.2% of Communication Technology in 2026 because field sensors require remote data transfer from energized and geographically dispersed line locations to utility control systems.
- Power Utilities account for 22.5% of Application in 2026 because line-capacity monitoring is directly tied to grid dispatch, transmission efficiency, and asset-management decisions.
- Utilities and Transmission System Operators account for 28.7% of End Use in 2026 because they set operating limits and integrate dynamic ratings into transmission planning and control-room workflows.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Senior Consultant at Fact.MR, states, “DLR sensor purchasing is moving from isolated line trials toward operational deployment on constrained corridors. Utilities need more than a field measurement. They need validated data, dependable communications, forecasting, and control-room integration that can support safe rating decisions. Suppliers that reduce installation effort while proving data quality and interoperability are better placed to convert pilots into broader utility programmes.”
- Strategic Implications
- Sensor suppliers should package hardware with validation, forecasting, and integration support because utilities must convert field measurements into approved operating ratings before additional capacity can be used.
- Retrofit deployment should focus on circuits where congestion costs or renewable curtailment are already measurable, since the economic case is clearer when additional line capacity has an immediate operational use.
- Communication architecture should be treated as part of the product specification. Utilities need secure transfer of high-frequency field data into SCADA, EMS, and asset-management systems without creating separate manual workflows.
- Vendors should distinguish between direct conductor sensing, weather-based approaches, and hybrid architectures so buyers can match measurement depth with line criticality, installation constraints, and expected capacity benefit.
How does the Dynamic Line Rating (DLR) Sensor Market break down by segment?
The market is segmented by Sensor Type, Installation Type, Line Type, Communication Technology, Application, and End Use.
Why do Weather Based Sensors lead Sensor Type?
Weather Based Sensors are projected to account for a 22.6% share in 2026.
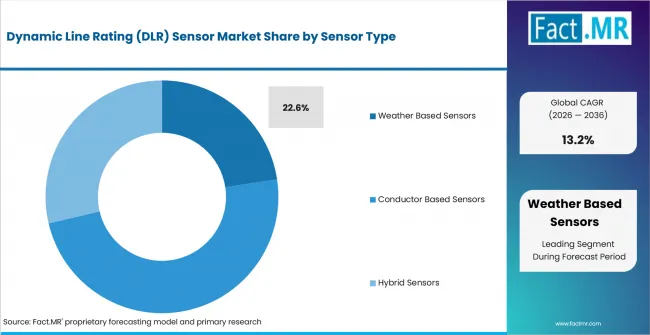
Dynamic Line Rating (dlr) Sensor Market Analysis By Sensor Type | Source: Fact.MR
Weather-based sensors lead because conductor capacity changes with the environment around the line. Wind can cool a conductor, while high ambient temperature and solar heating reduce the safe current it can carry. Measuring these conditions gives the DLR engine a real-time basis for moving beyond fixed seasonal assumptions.
FERC describes DLRs as ratings that reflect current forecasts of ambient air temperature, wind, and solar heating. The operational value is strongest where local conditions change enough to create recurring unused capacity, which makes reliable weather measurement central to rating accuracy.
Why do Retrofit Installations lead Installation Type?
Retrofit Installations are projected to account for a 36.8% share in 2026.
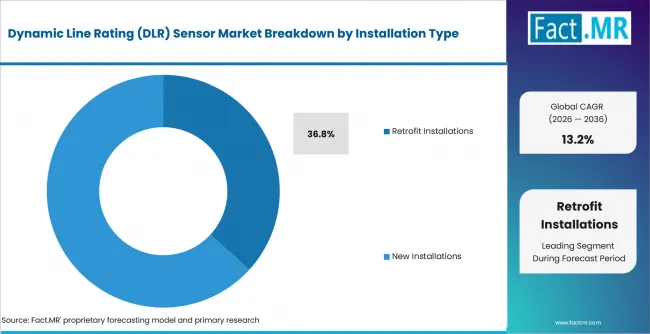
Dynamic Line Rating (dlr) Sensor Market Analysis By Installation Type | Source: Fact.MR
Retrofit installations lead because DLR is commonly purchased to extract more capability from lines that are already in service. Utilities can install sensors at critical spans, connect them to a rating platform, and use the resulting data before a multi-year line rebuild is completed.
The U.S. Department of Energy identifies DLR as a grid-enhancing technology that can increase use of existing transmission infrastructure at lower cost and with shorter deployment cycles than conventional expansion. This makes retrofit projects attractive on congested corridors where the utility needs capacity before a major reinforcement can be delivered.
Why do Transmission Lines lead Line Type?
Transmission Lines are projected to account for a 56.2% share in 2026.
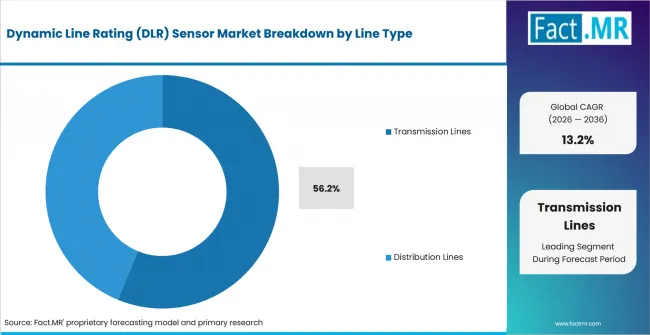
Dynamic Line Rating (dlr) Sensor Market Analysis By Line Type | Source: Fact.MR
Transmission lines lead because their thermal limits can constrain large power transfers across the grid. A rating change on a high-voltage corridor can influence dispatch, congestion, renewable curtailment, and the ability to move electricity between generation and load centres.
DOE guidance focuses DLR on real-time or forecasted current-carrying capacity of transmission lines while maintaining reliability limits. The value per monitored circuit is therefore higher where a line is already carrying substantial system flows or acts as a bottleneck between regions.
Why does Wireless lead Communication Technology?
Wireless is projected to account for a 59.2% share in 2026.
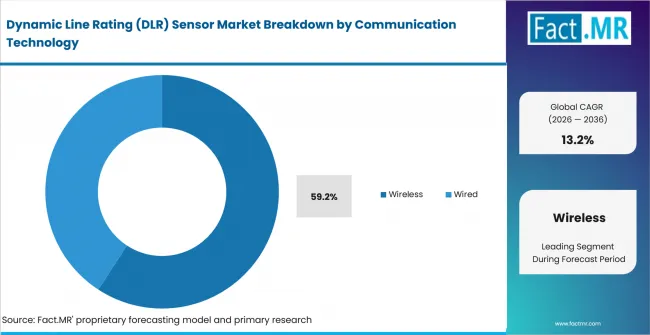
Dynamic Line Rating (dlr) Sensor Market Analysis By Communication Technology | Source: Fact.MR
Wireless communication leads because DLR sensors are often installed on energized conductors or towers far from utility-owned communications infrastructure. Cellular, radio, satellite, and low-power wide-area links allow field data to reach control systems without laying a separate physical communication path along the corridor.
The DOE-supported Oncor demonstration used radio receivers at substations to collect DLR data from field locations. Current commercial systems also use LTE-M, NB-IoT, satellite, and other wireless protocols, reinforcing wireless communication as the practical architecture for retrofit monitoring.
Why do Power Utilities lead Application?
Power Utilities are projected to account for a 22.5% share in 2026.
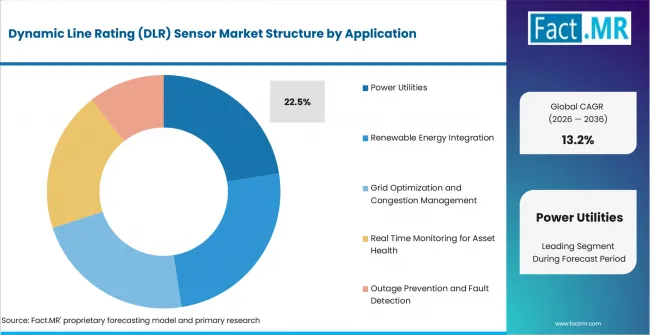
Dynamic Line Rating (dlr) Sensor Market Analysis By Application | Source: Fact.MR
Power utilities lead because DLR data affects operating decisions that sit directly within utility grid management. Operators need to know how much power a line can carry, whether sag or temperature is approaching a limit, and how the rating is expected to change during the next operating period.
The UK government’s 2026 DLR delivery plan links field deployment with upgrades to the National Energy System Operator’s ratings-management and control-room systems. This shows that the sensor purchase is tied to utility operating workflows rather than being an isolated instrumentation decision.
Why do Utilities and Transmission System Operators lead End Use?
Utilities and Transmission System Operators are projected to account for a 28.7% share in 2026.
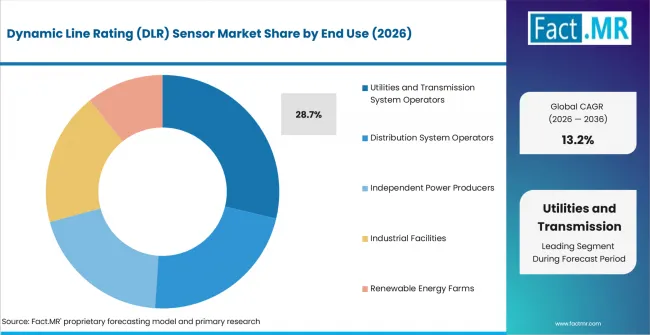
Dynamic Line Rating (dlr) Sensor Market Analysis By End Use | Source: Fact.MR
Utilities and transmission system operators lead because they are responsible for the safe transfer limits applied to overhead lines. They also decide which circuits justify monitoring and how rating data should be validated before it influences dispatch or transmission-service calculations.
In Great Britain, the government states that all three transmission owners have provided plans for DLR rollout, while NESO is upgrading control-room technology so dynamic ratings can be used operationally. The procurement decision therefore sits with organizations that own or operate the transmission network and can convert sensor data into usable grid capacity.
What is accelerating Dynamic Line Rating (DLR) Sensor Market adoption, and what is holding it back?
Adoption is being accelerated by transmission congestion, renewable integration, more accurate line-rating requirements, and the ability to retrofit monitoring onto existing circuits. Deployment can be slowed by validation requirements, cybersecurity and control-room integration, installation constraints on energized lines, and competition from sensorless rating approaches on less critical corridors.
Drivers Impact Analysis
| Factor | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Utility programmes to unlock existing transmission capacity | +1.6% | Global | Short term (<= 2 years) |
| More accurate and weather-responsive line-rating requirements | +1.4% | USA and UK | Short term (<= 2 years) |
| Renewable integration and congestion-management needs | +1.1% | UK, Germany, Japan and France | Medium term (2-4 years) |
| Retrofit-friendly sensor deployment on existing lines | +0.9% | USA, Germany and France | Medium term (2-4 years) |
| Control-room integration, forecasting and asset analytics | +0.6% | Global | Long term (>= 4 years) |
Opportunity Impact Analysis
| Factor | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| System-wide DLR rollout on constrained corridors | +1.0% | UK, Germany and USA | Medium term (2-4 years) |
| Hybrid physical and virtual sensing architectures | +0.8% | USA, UK and Germany | Medium term (2-4 years) |
| Monitoring for distribution and renewable-energy networks | +0.7% | Japan, France and USA | Long term (>= 4 years) |
| AI-based forecasting layered onto field sensor data | +0.5% | Global | Long term (>= 4 years) |
Restraints Impact Analysis
| Factor | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Validation and operational-integration burden before ratings are used | -1.1% | Global | Short term (<= 2 years) |
| Cybersecurity, communications and data-quality requirements | -0.9% | USA, UK and Germany | Short term (<= 2 years) |
| Sensorless DLR as a lower-hardware alternative | -0.7% | USA, Japan and Europe | Medium term (2-4 years) |
| Installation and maintenance constraints on energized lines | -0.5% | Global | Long term (>= 4 years) |
Which countries are scaling the Dynamic Line Rating (DLR) Sensor Market through 2036?
- UK: The government’s 2026 delivery plan calls for DLR rollout across the networks of SSE, SP Energy Networks, and National Grid Electricity Transmission. NESO has assessed circuits where DLR can reduce constraints and has requested installation on 40 circuits, creating a defined route from sensor deployment into control-room use.
- Germany: Weather-dependent operation is already established on parts of the German transmission network. TenneT reports long-running use of dynamic overhead-line monitoring, while Amprion has applied DLR on constrained corridors to increase usable transfer capability during favorable conditions.
- USA: FERC has moved transmission line ratings toward more weather-responsive calculations, while DOE continues to fund grid-enhancing-technology demonstrations. These programmes support sensor purchases where utilities need independently validated data before operational adoption.
- Japan: METI identifies DLR as a method for dynamically increasing transmission operating capacity and reducing renewable curtailment. Japanese utilities are validating conductor sensors, LTE communications, rating servers, and links to non-firm grid-control systems before broader use.
- France: RTE has installed DLR sensors on overhead lines in Hauts-de-France to measure how wind cooling changes allowable power transfer. Real-time data is sent to transmission control centres so available capacity can be adjusted without building a new line for every local constraint.
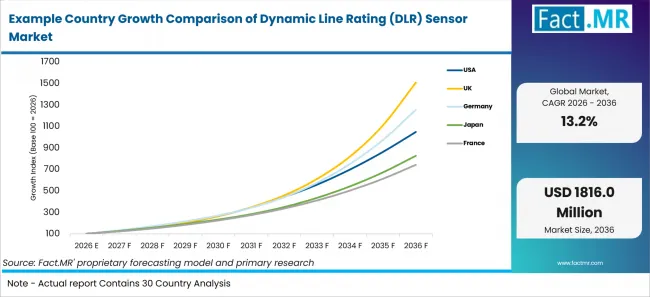
Example Country Growth Comparison Of Dynamic Line Rating (dlr) Sensor Market | Source: Fact.MR
| Country | CAGR, 2026-2036 |
|---|---|
| UK | 31.2% |
| Germany | 28.8% |
| USA | 26.5% |
| Japan | 23.5% |
| France | 22.2% |
What is driving the UK’s growth through 2036?
The UK is forecast to expand at a 31.2% CAGR from 2026 to 2036.
Growth is being supported by a move from trials toward planned transmission-network rollout. The UK government’s Reformed National Pricing delivery plan states that all three transmission owners have confirmed detailed DLR deployment plans and that NESO has completed an assessment of circuits where DLR can reduce constraints.
The same programme is upgrading NESO’s ratings-management and control-room technology in phases through 2027/28. This creates demand for sensors, communications, data validation, and systems integration because installed hardware must feed ratings that operators can use at day-ahead and live operating timescales.
What is driving Germany’s growth through 2036?
Germany is forecast to expand at a 28.8% CAGR from 2026 to 2036.
Germany has an established operating base for weather-dependent overhead-line ratings. TenneT states that it introduced dynamic operation on 220 kV and 380 kV lines in 2010 and subsequently expanded weather-dependent monitoring across a substantial part of its German overhead network.
Amprion has also used DLR on the Emsland corridor, where its market report described a 25% increase in maximum transmission capacity on a key bottleneck route. Further sensor and weather-station deployment supports demand for field measurement that can be parameterized inside transmission-network models.
What is driving USA’s growth through 2036?
The USA is forecast to expand at a 26.5% CAGR from 2026 to 2036.
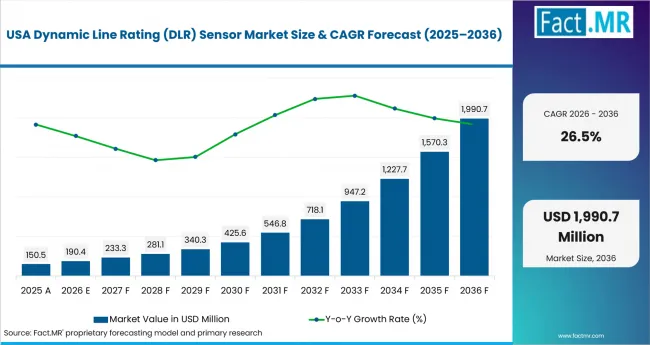
Dynamic Line Rating (dlr) Sensor Market Country Value Analysis | Source: Fact.MR
FERC’s line-rating reforms are increasing the operating value of weather-responsive transmission data. Order No. 881 requires ambient-adjusted ratings for near-term service, and the Commission’s subsequent DLR proceeding has examined ratings that also reflect wind and solar heating on suitable lines.
DOE-funded demonstrations are reducing technical uncertainty around deployment. The Department reported a Pennsylvania pilot where dynamic ratings increased line capacity by 25%, while additional projects are testing direct and indirect sensing, weather-based DLR, digital twins, and field validation. These programmes support purchases by utilities that need evidence before scaling across more circuits.
What is driving Japan’s growth through 2036?
Japan is forecast to expand at a 23.5% CAGR from 2026 to 2036.
Japan is trying to use existing networks more efficiently as renewable output and grid congestion increase. METI describes DLR as a way to calculate line operating capacity dynamically from weather and line information so non-firm renewable connections can face less curtailment when physical conditions permit.
A regulatory review of utility research describes prototype DLR systems that combine line sensors, LTE communication, rating servers, and links to grid-control equipment. The programme envisages broader application to expected congestion lines after validation, creating a purchasing path for conductor sensors and communications hardware.
What is driving France’s growth through 2036?
France is forecast to expand at a 22.2% CAGR from 2026 to 2036.
RTE has deployed DLR sensors on existing overhead lines to use local wind conditions as an operating input. On the Achiet-le-Grand to Thilloy-les-Mofflaines line, sensors were installed on an energized 90 kV circuit so real-time measurements could be transmitted directly to the regional high-voltage control centre.
RTE later deployed additional sensors on the Vaumoise to Villers-Cotterêts line. These projects demonstrate a repeatable model in which field sensing supports higher transfer when conductors are being cooled by wind, helping integrate variable generation while limiting the need for immediate new-line construction.
Who Leads the Dynamic Line Rating (DLR) Sensor Market?
Key players in the Dynamic Line Rating (DLR) Sensor Market include General Electric (GE Vernova), Heimdall Power, Ampacimon, Lindsey Systems, Sentient Energy, Inc., Schneider Electric SE, Toshiba Corporation, Landis+Gyr, Sentrisense (a Megger company), Gridpulse, Laki Power, Energiot, Micca Informationstechnologie, Atecnum / USi, and Nexans (Valley Group).
Competition is shaped by measurement architecture and integration depth. Heimdall Power combines physical line-mounted sensors with virtual sensing and forecasting, while Ampacimon uses conductor-mounted monitoring and vibration-based measurement. Lindsey Systems focuses on transmission capacity forecasting and line behavior, and Sentrisense (a Megger company) is supplying overhead-line sensors to support wider DLR deployment by TenneT.
Broader grid-technology companies participate in the DLR ecosystem through software and control-system integration. GE Vernova and Toshiba currently offer sensorless DLR approaches, placing these solutions adjacent to the physical sensor revenue defined in this assessment. Schneider Electric participates through protection, control and grid-management technologies linked to dynamic rating workflows.
The current corporate context matters for several companies. General Electric’s grid software and energy activities are now represented by GE Vernova. Sentient Energy was acquired from Koch Engineered Solutions by Accurant International in 2024 and continues to market grid-sensor and analytics products. Nexans’ 2025 registration document continues to list The Valley Group, Inc. as a U.S. subsidiary, while Atecnum currently markets the PowerDonut line-monitoring platform associated with the USi technology lineage.
Supplier selection depends on sensor accuracy, installation method, communications reliability, forecasting capability, cybersecurity, and integration with SCADA or EMS platforms. Utilities also assess whether a vendor can validate ratings across different conductor types and weather conditions before the system is permitted to influence live operating limits.
Which companies are the key providers?
Key Companies includes General Electric (GE Vernova); Heimdall Power; Ampacimon; Lindsey Systems; Sentient Energy, Inc. (an Accurant International company); Schneider Electric SE; Toshiba Corporation; Landis+Gyr; Sentrisense (a Megger company); Gridpulse; Laki Power; Energiot; Micca Informationstechnologie; Atecnum / USi; Nexans (Valley Group)
- General Electric (GE Vernova)
- Heimdall Power
- Ampacimon
- Lindsey Systems
- Sentient Energy, Inc. (an Accurant International company)
- Schneider Electric SE
- Toshiba Corporation
- Landis+Gyr
- Sentrisense (a Megger company)
- Gridpulse
- Laki Power
- Energiot
- Micca Informationstechnologie
- Atecnum / USi
- Nexans (Valley Group)
Bibliography
- U.S. Department of Energy. (2020). Advanced Transmission Technologies. Office of Electricity.
- U.S. Department of Energy. (2023). Grid-Enhancing Technologies Improve Existing Power Lines. Office of Electricity.
- U.S. Department of Energy. (2025). Smart Transmission Tools Modernize America’s Power Grid. U.S. Department of Energy.
- U.S. Department of Energy. (2017). Oncor Electric Delivery Company: Dynamic Line Rating Demonstration. Office of Electricity.
- Federal Energy Regulatory Commission. (2021). Staff Presentation: Final Order Regarding Managing Transmission Line Ratings. FERC.
- Federal Energy Regulatory Commission. (2024). Presentation E-1: Implementation of Dynamic Line Ratings. FERC.
- Government of the United Kingdom. (2026). Reformed National Pricing: Delivery Plan. Department for Energy Security and Net Zero.
- TenneT TSO GmbH. (2025). Freileitungsmonitoring: Weather-dependent Operation of Overhead Lines. TenneT.
- Amprion GmbH. (2021). Market Report 2021: Further Development of Dynamic Line Rating. Amprion.
- Agency for Natural Resources and Energy. (2022). Power Transmission and Distribution Business: Dynamic Rating as a Measure to Reduce Curtailment under Non-firm Connections. Ministry of Economy, Trade and Industry, Japan.
- Electricity and Gas Market Surveillance Commission. (2024). Dynamic Line Rating: Overview and Research Status. Ministry of Economy, Trade and Industry, Japan.
- Agency for Natural Resources and Energy. (2025). Energy White Paper 2025: Formation of Next-generation Power Networks. Ministry of Economy, Trade and Industry, Japan.
- RTE. (2020). RTE Uses Wind to Optimize Grid Capacity in Hauts-de-France. Réseau de Transport d’Électricité.
- RTE. (2021). Soissons-Compiègne: RTE Uses Wind to Optimize the Electricity Network. Réseau de Transport d’Électricité.
- GE Vernova. (2026). GridOS Digital Dynamic Line Rating. GE Vernova Inc.
- Heimdall Power. (2026). Heimdall Power and Entergy Deploy Multi-state Dynamic Line Rating Project. Heimdall Power.
- Ampacimon. (2026). Sensor-based Dynamic Line Rating Solutions. Ampacimon.
- Lindsey Systems. (2026). SMARTLINE Dynamic Line Rating and Transmission Capacity Forecasting. Lindsey Manufacturing Company.
- Sentrisense (a Megger company). (2026). TenneT Selects Sentrisense (a Megger company) to Support the Expansion of Dynamic Line Rating. Sentrisense (a Megger company).
- Sentient Energy. (2024). Accurant International Acquires Sentient Energy, a Business Unit of Koch Engineered Solutions. Sentient Energy.
- Schneider Electric. (2026). Dynamic Line Rating and Interconnection Protection. Schneider Electric SE.
- Toshiba. (2025). Dynamic Line Rating Technology without Use of Sensors for Effective Utilization of Existing Transmission Lines. Toshiba Energy Systems & Solutions Corporation.
- Atecnum. (2026). PowerDonut Transmission Line Monitoring and Dynamic Line Rating. Atecnum Corporation.
- Nexans. (2026). 2025 Universal Registration Document. Nexans S.A.
This Report Answers
- How real-time weather and conductor data change the amount of power that an overhead line can safely carry.
- Why retrofit DLR projects are being used on constrained transmission corridors before conventional line expansion is completed.
- How sensor, communication, forecasting, and control-room requirements shape utility procurement decisions.
- How country-specific grid policies and operational programmes influence deployment through 2036.
- How dedicated DLR vendors compete with broader grid-software and protection-system suppliers.
What does the Dynamic Line Rating (DLR) Sensor Market cover?
The Dynamic Line Rating (DLR) Sensor Market covers commercial sensor and monitoring-system revenue used to measure environmental or conductor conditions that support dynamic calculation of overhead-line capacity. Counted revenue includes covered sensing hardware and integrated monitoring configurations sold within the defined segment taxonomy.
The market includes systems used for grid monitoring, transmission efficiency, renewable integration, asset health, congestion management, and outage-prevention applications when the product is supplied as part of a DLR sensor or monitoring configuration.
What is included in the scope?
The scope includes Weather Based Sensors, Conductor Based Sensors, and Hybrid Sensors together with the listed subsegments. It covers Retrofit Installations and New Installations across Transmission Lines and Distribution Lines, using Wireless or Wired communication technologies.
Application coverage includes Power Utilities, Renewable Energy Integration, Grid Optimization and Congestion Management, Real Time Monitoring for Asset Health, and Outage Prevention and Fault Detection. End users include Utilities and Transmission System Operators, Distribution System Operators, Independent Power Producers, Industrial Facilities, and Renewable Energy Farms across the stated global regions.
What is excluded from the scope?
The scope excludes new transmission conductors, towers, substations, transformers, and other grid equipment when sold without the covered DLR sensing or monitoring function. General weather stations are excluded when they are not deployed to support line rating or the listed applications.
Standalone grid-planning software, power-flow-control devices, and sensorless rating software are excluded when sold without covered sensor or monitoring revenue. Routine line inspection services are also outside the market unless they are supplied as part of a covered DLR monitoring system.
How Was the Analysis Built?
The analysis draws on more than 120 sources, over 35 company portfolios and more than 20 industry interviews across at least 25 countries.
- Primary Research: Interviews with transmission system operators, distribution utilities, DLR sensor manufacturers, grid-software providers, line-maintenance teams, renewable project operators, and utility engineering consultants examine deployment criteria, validation requirements, installation practices, communications architecture, and purchasing priorities.
- Desk Research: The review covers transmission-line-rating regulation, grid-enhancing-technology programmes, renewable-integration policy, utility DLR demonstrations, grid-modernization plans, technical publications, company product documentation, and corporate-status disclosures. Sources used in the article are recorded in the bibliography.
- Market Sizing and Forecasting: Estimates consider monitored transmission and distribution line kilometres, sensor density per deployed corridor, retrofit and new-installation mix, hardware and monitoring-system pricing, communication architecture, utility rollout schedules, and country-level adoption of dynamic ratings.
- Data Validation and Update Cycle: Findings are cross-checked against utility programmes, regulatory actions, company activity, and primary interviews. Updates account for new DLR tenders, changes in line-rating rules, sensor-platform launches, ownership changes, and expansion from pilot circuits to broader network deployment.
What is the report's scope and coverage?
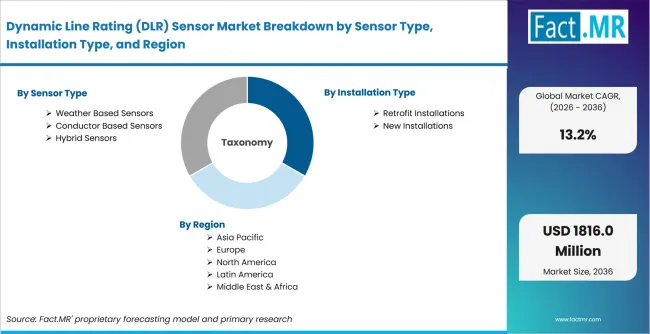
Dynamic Line Rating (dlr) Sensor Market Breakdown By Sensor Type, Installation Type, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD million |
| Market Definition | Dynamic line rating sensors and integrated monitoring systems sold across the defined segments and applications |
| Segments Covered | Sensor Type; Installation Type; Line Type; Communication Technology; Application; End Use |
| Regions Covered | North America; Latin America; Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | UK; Germany; USA; Japan; France |
| Key Companies Profiled | General Electric (GE Vernova); Heimdall Power; Ampacimon; Lindsey Systems; Sentient Energy, Inc.; and others |
| Forecast Period | 2026 to 2036 |
| Base Year | 2025 |
| Market Value, 2026 | USD 525.6 million |
| Market Value, 2036 | USD 1,816.0 million |
| CAGR, 2026-2036 | 13.2% |
| Absolute Opportunity | USD 1,290.4 million |
| Approach | Hybrid top-down and bottom-up approach using monitored line kilometres, sensor density, retrofit and new-installation mix, system pricing, communications architecture, utility rollout schedules, and country-level DLR adoption |
How is the market segmented?
-
By Sensor Type
- Weather Based Sensors
- Ambient Weather Sensors
- Wind Monitoring Sensors
- Environmental Monitoring Sensors
- Conductor Based Sensors
- Conductor Temperature Sensors
- Sag and Tension Sensors
- Current Monitoring Sensors
- Hybrid Sensors
- Multi Parameter Sensors
- Advanced Hybrid Systems
- Grid Integrated Sensors
- Weather Based Sensors
-
By Installation Type
- Retrofit Installations
- Existing Grid Retrofit
- Modular Retrofit Systems
- Low Downtime Installations
- New Installations
- New Transmission Projects
- New Distribution Projects
- Smart Grid Installations
- Retrofit Installations
-
By Line Type
- Transmission Lines
- High Voltage Lines
- Extra High Voltage Lines
- Long Distance Transmission
- Distribution Lines
- Urban Distribution
- Rural Distribution
- Industrial Distribution
- Transmission Lines
-
By Communication Technology
- Wireless
- RF Communication
- Cellular Communication
- Satellite Communication
- Wired
- Fiber Optic Communication
- Ethernet Based Systems
- Power Line Communication
- Wireless
-
By Application
- Power Utilities
- Grid Monitoring
- Transmission Efficiency
- Asset Management
- Renewable Energy Integration
- Solar Energy Integration
- Wind Energy Integration
- Hybrid Renewable Systems
- Grid Optimization and Congestion Management
- Load Optimization
- Congestion Reduction
- Grid Reliability
- Real Time Monitoring for Asset Health
- Condition Monitoring
- Predictive Maintenance
- Remote Diagnostics
- Outage Prevention and Fault Detection
- Fault Monitoring
- Outage Management
- Risk Mitigation
- Power Utilities
-
By End Use
- Utilities and Transmission System Operators
- Transmission Operators
- Public Utilities
- Grid Modernization Programs
- Distribution System Operators
- Urban Distribution Operators
- Rural Distribution Operators
- Distribution Automation
- Independent Power Producers
- Conventional Power Producers
- Renewable Power Producers
- Hybrid Energy Producers
- Industrial Facilities
- Manufacturing Facilities
- Mining Operations
- Oil and Gas Facilities
- Renewable Energy Farms
- Solar Farms
- Wind Farms
- Hybrid Renewable Farms
- Utilities and Transmission System Operators
-
By Region:
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa