- Market Value (2025): USD 4.4 Bn
- Estimated Value (2026): USD 4.8 Bn
- Forecast Value (2036): USD 10.9 Bn
- CAGR (2026-2036): 8.5%
What is the Helmet Mounted Display Market forecast to be worth by 2036?
USD 4.8 billion in 2026 to USD 10.9 billion by 2036 at an 8.5% CAGR.
- The Helmet Mounted Display Market was valued at USD 4.4 billion in 2025.
- Demand is projected to increase from USD 4.8 billion in 2026 to USD 10.9 billion by 2036.
- The market is forecast to record an 8.5% CAGR from 2026 to 2036 as combat aircraft, helicopters, and training systems place more mission data inside the user line of sight.
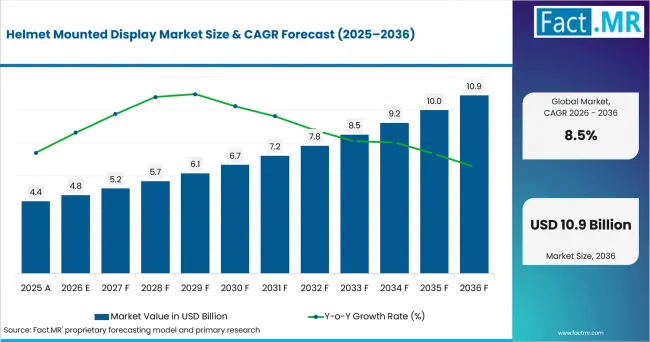
Helmet Mounted Display Market Value Analysis | Source: Fact.MR
What are the defining numbers behind Helmet Mounted Display Market growth?
USD 6.1 billion absolute opportunity by 2036, led by Helmet Mounted Displays, Airborne Platforms and Germany.
- Demand Drivers in the Market
- Combat aircraft teams need visor-level navigation and targeting data because pilots must read sensor information without shifting attention to cockpit panels.
- Helicopter crews need synthetic vision and head tracking supported by landing cues in dust, fog, smoke, and night missions.
- Soldier modernization teams need lighter helmet displays owing to longer missions and higher data load at unit level.
- Training centers need mixed-reality headsets that reproduce cockpit and vehicle tasks while reducing dependence on live platforms.
- SIPRI reported in April 2026 that world military expenditure reached USD 2,887 billion in 2025, giving display suppliers a broad defense spending base. This spending backdrop supports demand for airborne optronics systems that connect sensors and helmet displays inside modern aircraft.
- Key Segments Analyzed
- By Product: Helmet Mounted Displays are expected to hold 49.5% share in 2026 because they form the core visor, optics, and cueing layer in the system.
- By Technology: Augmented Reality Displays are projected to account for 41.8% share in 2026 supported by symbology overlay and real-time mission data.
- By Display Technology: Organic Light Emitting Diode is anticipated to capture 34.6% share in 2026 owing to contrast, response speed, and compact module design.
- By Component: Display Modules are estimated to represent 38.2% share in 2026 because they carry the visual output that crews directly use.
- By Platform: Airborne Platforms are forecast to hold 46.7% share in 2026 led by fighter aircraft and helicopter integration work.
- By Application: Navigation And Situational Awareness is expected to account for 29.4% share in 2026 due to heads-up route and threat awareness needs.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, "Helmet displays now behave like part of the aircraft and soldier information layer. Adoption is expected to rise where display brightness, low-latency tracking, and night-vision integration reduce workload. Winning suppliers combine optical design, sensor fusion, and platform qualification in one repeatable package."
- Strategic Implications
- Airframe integrators should qualify helmet displays with avionics, sensors, and pilot equipment early in the upgrade cycle.
- Defense electronics vendors should document latency, field of view, and night-vision performance under actual mission conditions.
- Training-system providers should connect mixed-reality headsets with cockpit trainers and vehicle simulators for repeatable crew practice.
- Component suppliers should keep display modules, optical engines, and tracking sensors modular across aircraft and soldier platforms.
Germany is projected to record 9.8% CAGR through 2036 driven by Eurofighter and F-35 cockpit modernization. Brazil is expected to post 8.9% CAGR supported by Gripen localization. The USA is anticipated to advance at 8.1% CAGR due to fighter and Navy aircrew helmet renewal. The UK is estimated to hold 7.2% CAGR led by Typhoon support. Japan is forecast to reach 6.4% CAGR shaped by F-35A and F-35B fleet activity linked to cockpit alert systems.
How does the Helmet Mounted Display Market break down by segment?
Helmet Mounted Displays lead Product at 49.5%; Airborne Platforms lead Platform at 46.7%.
Which Product dominates?
Helmet Mounted Displays are expected to hold 49.5% share in 2026.
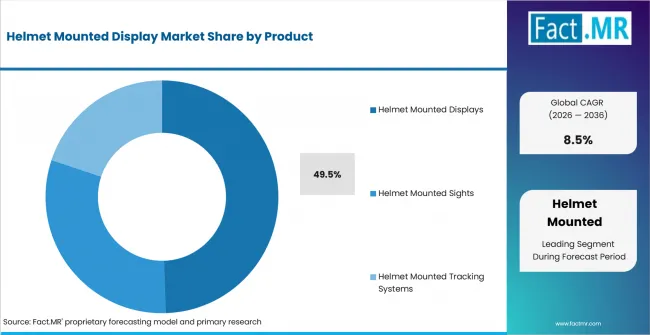
Helmet Mounted Display Market Analysis By Product | Source: Fact.MR
Helmet Mounted Displays are projected to lead Product because they place mission data in the wearer’s view. Fixed wing and rotary wing variants support aircraft cueing, while ground and naval systems serve heads-up awareness. BAE Systems plc describes Striker II as flight-proven with integrated night vision.
What leads the Technology segment?
Augmented Reality Displays are projected to account for 41.8% share in 2026.
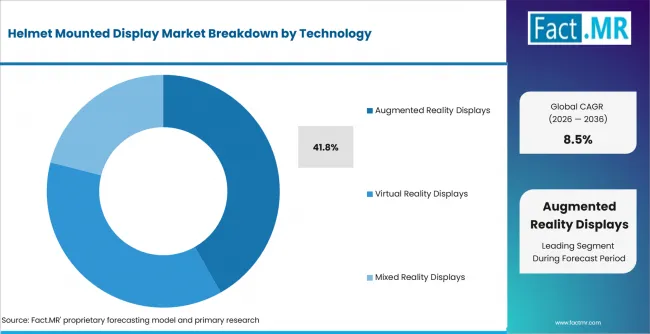
Helmet Mounted Display Market Analysis By Technology | Source: Fact.MR
Augmented Reality Displays are anticipated to lead Technology because they overlay symbols on the external view. Waveguide and projection designs support compact helmet layouts. Elbit Systems stated in February 2026 that its UH-60 HDTS uses synthetic vision symbology and line-of-sight tracking.
How does Display Technology shape demand?
Organic Light Emitting Diode is anticipated to capture 34.6% share in 2026.
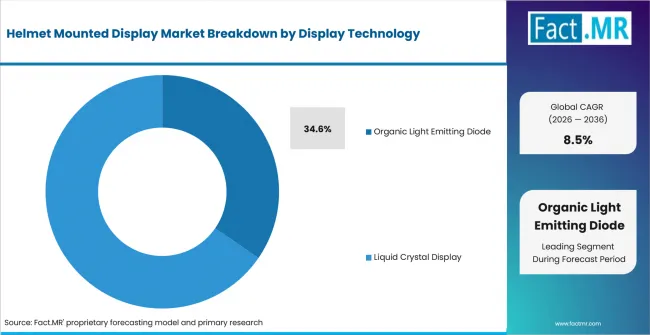
Helmet Mounted Display Market Analysis By Display Technology | Source: Fact.MR
Organic Light Emitting Diode is estimated to lead Display Technology owing to contrast and compact near-eye module design. Liquid Crystal Display remains useful in familiar supply routes. Liquid Crystal On Silicon supports projection systems, while Micro Light Emitting Diode suits high-brightness applications.
What supports Display Modules within Component?
Display Modules are estimated to represent 38.2% share in 2026.
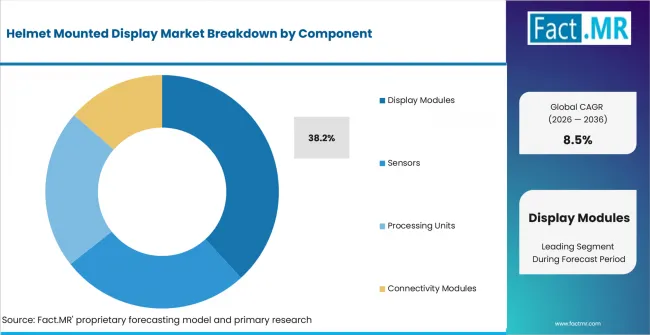
Helmet Mounted Display Market Analysis By Component | Source: Fact.MR
Display Modules are forecast to lead Component demand because they carry the information seen by the wearer. Optical engines, sensors, and processing units shape resolution and tracking. NAVAIR reported in February 2026 that the NGFWH contract covers more than 5,000 systems and spares.
What leads the Platform segment?
Airborne Platforms are forecast to hold 46.7% share in 2026.
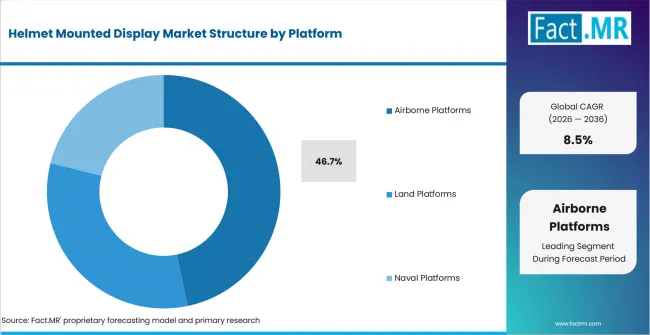
Helmet Mounted Display Market Analysis By Platform | Source: Fact.MR
Airborne Platforms are expected to lead Platform demand led by fighter aircraft and helicopter integration needs. Fighter Aircraft require precise cueing under high workload. Helicopters use helmet systems for low-altitude flight, while land and naval platforms add smaller mission-use cases.
How does Application shape adoption?
Navigation And Situational Awareness is expected to account for 29.4% share in 2026.
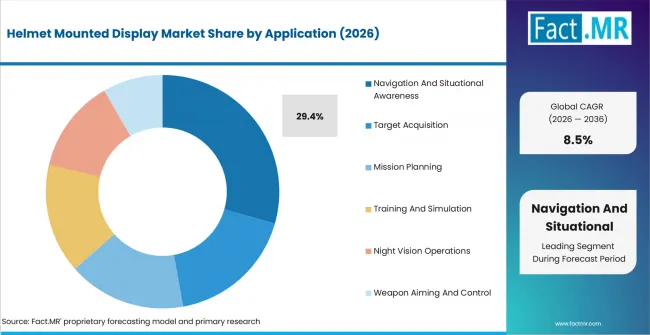
Helmet Mounted Display Market Analysis By Application | Source: Fact.MR
Navigation And Situational Awareness is projected to lead Application demand because HMDs help crews interpret route, heading, and threat cues. Target Acquisition follows where line-of-sight aiming shortens response. Training And Simulation gains share as extended reality technology strengthens headset-based training links.
What is accelerating Helmet Mounted Display Market adoption, and what is holding it back?
Cockpit data integration drives it; qualification cost restrains it.
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Fighter aircraft modernization | +1.9% | North America, Europe, East Asia | Short term (<= 2 years) |
| Helmet-level situational awareness | +1.5% | Global | Medium term (2-4 years) |
| Training and simulation digitization | +0.8% | Europe, North America | Long term (>= 4 years) |
- Fighter aircraft modernization: New avionics and radar packages can increase the value of helmet-mounted cueing and display systems. HMD suppliers benefit when display qualification, integration, and replacement cycles align with broader fighter-aircraft modernization programs.
- Helmet-level situational awareness: Pilots and soldiers need mission information without looking away from their operational environment. Helmet-mounted displays can support faster interpretation, navigation, targeting, threat awareness, and coordination by placing critical information directly within the user’s field of view.
- Training and simulation digitization: Mixed-reality headsets are increasingly used in cockpit trainers, vehicle simulators, and mission-rehearsal environments. These systems can improve training realism, reduce dependence on physical platforms, and support repeatable simulation scenarios across defense and aviation programs.
Opportunity Impact Analysis
| Opportunity | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Waveguide and compact optics | +1.0% | Global | Medium term (2-4 years) |
| Mixed-reality crew training | +0.9% | North America, Europe | Short term (<= 2 years) |
| Modular aircraft helmets | +0.6% | North America, Europe | Long term (>= 4 years) |
- Waveguide and compact optics: Thinner optical architectures can support lighter helmet designs, improved comfort, and better integration of visual information. The opportunity is strongest where pilots need color symbology, targeting cues, and night-imaging functions combined within a single visor system.
- Mixed-reality crew training: Air and ground forces are adopting immersive headsets for training outside live aircraft and vehicles. This creates demand for rugged mixed-reality systems that integrate with simulators, mission-rehearsal environments, and field classrooms while supporting repeatable training scenarios.
- Modular aircraft helmets: Modular helmet designs allow displays, communications equipment, and other mission systems to be upgraded during planned refresh cycles. This supports longer platform life and gives defense operators more flexibility to add new capabilities without replacing the entire helmet system.
Restraints Impact Analysis
| Restraint | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Aircraft qualification cost | -0.7% | Global | Short term (<= 2 years) |
| Helmet weight and comfort limits | -0.5% | Global | Medium term (2-4 years) |
| Display latency and calibration risk | -0.4% | North America, Europe | Medium term (2-4 years) |
- Aircraft qualification cost: Helmet-mounted displays must integrate with avionics, sensors, weapons, and pilot-safety requirements. Qualification, testing, and certification can extend development timelines before new display systems enter operational service.
- Helmet weight and comfort limits: Cameras, wiring, optics, and other integrated components can increase helmet weight and user fatigue during long missions. Suppliers therefore need lighter materials, balanced designs, and improved ergonomics to reduce neck strain and maintain comfort.
- Display latency and calibration risk: Misaligned or delayed symbology can reduce confidence in the display during rapid maneuvers. Qualification teams therefore need repeated testing of tracking accuracy, calibration, latency, and image stability before systems are cleared for operational use.
Which countries are scaling Helmet Mounted Display Market through 2036?
- The country comparison spans 3.4 percentage points and forms three practical growth bands across the forecast period.
- Germany remains 0.9 percentage point above Brazil through Eurofighter and F-35 cockpit modernization.
- Brazil remains 0.8 percentage point above the USA as Gripen localization expands aircraft electronics work.
- The USA remains 0.9 percentage point above the UK through fighter funding and Navy aircrew helmet renewal.
- The UK remains 0.8 percentage point above Japan through Typhoon engineering support and F-35B operations.
- Japan closes the displayed range through F-35A and F-35B acquisitions plus base-readiness work.
Comparable CAGRs create different entry conditions due to fleet timing and qualification rules. Full report coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
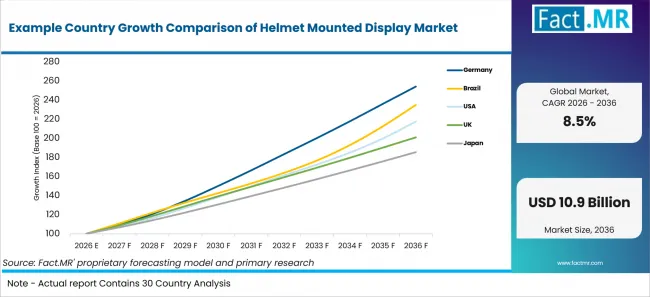
Example Country Growth Comparison Of Helmet Mounted Display Market | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| Germany | 9.8% |
| Brazil | 8.9% |
| USA | 8.1% |
| UK | 7.2% |
| Japan | 6.4% |
What supports Germany adoption?
9.8% CAGR through 2036, driven by Eurofighter and F-35 cockpit modernization.
Germany is scaling demand through Eurofighter funding and the F-35A transition. The Deutscher Bundestag stated in September 2025 that EUR 796.97 million was assigned for the Eurofighter weapon system. The country is expected to benefit as avionics and pilot interface work move together.
How is Brazil scaling helmet display demand?
8.9% CAGR through 2036, driven by Gripen localization and air-defense renewal.
Brazil is building demand around the F-39 Gripen program and local aerospace work. The Brazilian Air Force reported in February 2026 that 10 Gripen units were in operation. The country is projected to gain from local aircraft electronics learning.
What supports USA adoption?
8.1% CAGR through 2036, driven by fighter funding and Navy aircrew helmet renewal.
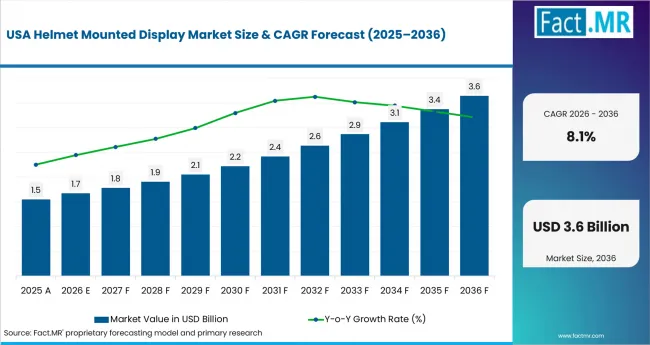
Helmet Mounted Display Market Country Value Analysis | Source: Fact.MR
The USA links demand to fighter programs and Navy aircrew equipment renewal. NAVAIR reported in February 2026 that a USD 22.6 million NGFWH award covers more than 5,000 systems and spares. The market is anticipated to benefit from fixed-wing aircraft scale.
What supports the UK outlook?
7.2% CAGR through 2036, driven by Typhoon upgrades and F-35B operations.
The UK outlook is supported by Typhoon engineering work and combat-air electronics capability. The UK Ministry of Defence announced in January 2026 a GBP 205 million Typhoon support contract extension over five years. The country is estimated to advance through staged avionics work.
How does Japan perform?
6.4% CAGR through 2036, driven by F-35A acquisition and base readiness work.
Japan is adding fighter capacity while preparing bases and shipboard operations. The Japan Ministry of Defense’s FY2026 budget allocated JPY 149.3 billion for acquisition of 8 F-35A aircraft. Demand is forecast to build as F-35 integration raises pilot display needs.
Who leads the Helmet Mounted Display Market?
BAE Systems plc and Elbit Systems lead direct helmet display coverage, while Collins Aerospace (RTX Corporation) and Thales Group strengthen avionics and mission-system depth.
BAE Systems plc is profiled through Striker II, which builds on the original Striker HMD used on Eurofighter Typhoon and Saab JAS 39 Gripen. Elbit Systems is active through helmet display, tracking, and synthetic vision systems. Collins Aerospace (RTX Corporation) remains tied to F-35 helmet display heritage, while Thales Group supports aircrew display technologies linked to electro-optical systems.
HTC Corporation, Sony Corporation, and Varjo Technologies Oy are profiled across virtual and mixed-reality training systems. L3Harris Technologies, Leonardo DRS, Inc., support the market through avionics, electro-optics, sensors, and display-adjacent defense electronics. Competition is shaped by qualification, brightness, latency, and lifecycle support.
Elbit Systems announced in February 2026 that it would supply HDTS for the Israeli Air Force UH-60 Black Hawk fleet. The system combines helmet display, tracking, synthetic symbology, and multi-sensor integration for crew decision support.
Which companies are the key providers?
Key companies include BAE Systems plc, Collins Aerospace (RTX Corporation), Elbit Systems Ltd., HTC Corporation, L3Harris Technologies, Inc., Leonardo DRS, Inc., Sony Corporation, Thales Group, and Varjo Technologies Oy.
- BAE Systems plc
- Collins Aerospace (RTX Corporation)
- Elbit Systems Ltd.
- HTC Corporation
- L3Harris Technologies, Inc.
- Leonardo DRS, Inc.
- Sony Corporation
- Thales Group
- Varjo Technologies Oy
Bibliography
- BAE Systems. (2025, February 13). Striker® II helmet-mounted display.
- Elbit Systems. (2026, February 24). Elbit Systems to supply Helmet Display and Tracking System for the Israeli Air Force UH 60 Black Hawk helicopter fleet.
- Varjo. (2025, October 8). Varjo launches mixed reality headsets purpose-built for training across air, land, and sea.
- Naval Air Systems Command. (2026, February 4). U.S. Navy awards contract for next-generation fixed wing helmet system.
- U.S. Department of Defense. (2025, June 26). Background briefing on FY 2026 defense budget.
- U.S. Government Accountability Office. (2025, September 3). F-35 Joint Strike Fighter: Actions needed to address late deliveries and improve future development (GAO-25-107632).
- Ministry of Defence. (2026, January 19). Britain’s fighter jet fleet strengthened in £205 million boost for British jobs.
- Deutscher Bundestag. (2025, September 5). Haushalt 2025: Verteidigungsetat auf neuem Höchststand.
- Cavalcante, F. (2026, February 24). Caças suecos vêm de Anápolis para proteger símbolos do poder no DF. Metrópoles.
- Ministry of Defense, Japan. (2025, December 10). Progress and budget in fundamental reinforcement of defense capabilities: Overview of FY2026 budget request.
- Stockholm International Peace Research Institute. (2026, April 27). Global military spending rise continues as European and Asian expenditures surge.
This Report Answers
- The report explains Product and Platform demand across aircraft, soldier, naval, and training use cases.
- Segment analysis identifies Helmet Mounted Displays and Airborne Platforms as the main share leaders in 2026.
- Country analysis examines Germany, Brazil, USA, UK, and Japan by aircraft modernization and defense electronics activity.
- Competitive analysis reviews BAE Systems plc, Collins Aerospace (RTX Corporation), Elbit Systems Ltd., HTC Corporation, L3Harris Technologies, Leonardo DRS, Inc., Sony Corporation, Thales Group, and Varjo Technologies Oy.
- The forecast is supported by official defense agencies, company product pages, public budget releases, and company announcements.
What does the Helmet Mounted Display Market cover?
Helmet displays, helmet sights, and tracking systems used for mission display and cueing.
The Helmet Mounted Display Market covers near-eye and visor-projected systems that place mission data in the wearer’s line of sight. It includes aircraft HMDs, ground and naval helmet interfaces, helmet sights, and tracking systems within the broader helmet mounted display category.
The assessment covers display modules, optical engines, sensors, processing units, and connectivity modules inside a complete helmet display system. Wearable display systems helps separate helmet electronics from general wearable screens.
What is included in the scope?
Helmet mounted display systems used on aircraft, land platforms, naval platforms, and training systems.
The scope includes fixed wing and rotary wing helmet displays, target sights, night vision sights, tracking systems, and simulation headsets that present mission or training information through the helmet. Relevant adjacent coverage includes aircraft sensors used with cueing and targeting functions.
What is excluded from the scope?
Standalone protective helmets and general consumer headsets are outside the scope.
The scope excludes protective helmets sold without display electronics, consumer gaming headsets, and cockpit screens mounted away from the helmet. Raw sensors and software are included only within a helmet display package. Related military helmet equipment is treated separately when protection is the core function.
How Was the Analysis Built?
120+ sources, 35+ company portfolios, 25+ countries, and 20+ interviews.
- Primary Research: Primary research includes discussions with aircrew equipment teams, avionics integrators, simulator providers, and defense electronics suppliers. These interviews examine selection criteria, qualification needs, and upgrade timing.
- Desk Research: Desk research covers official defense budgets, air force releases, company product pages, technology statements, and aircraft modernization documents.
- Market Sizing and Forecasting: Market estimates combine historical performance, aircraft upgrade timing, component mix, segment shares, country CAGRs, and provider portfolio checks.
- Data Validation and Update Cycle: Findings are validated against company activity, defense spending, program milestones, and platform compatibility. Updates review product launches, contract awards, and qualification progress.
What is the report’s scope and coverage?
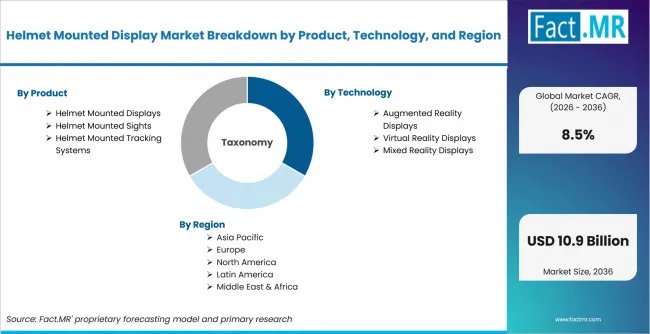
Helmet Mounted Display Market Breakdown By Product, Technology, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Helmet mounted display systems that present flight, mission, navigation, targeting, training, or situational-awareness information through helmet or near-eye displays. |
| Product | Helmet Mounted Displays; Helmet Mounted Sights; Helmet Mounted Tracking Systems |
| Technology | Augmented Reality Displays, Virtual Reality Displays, Mixed Reality Displays |
| Display Technology | Organic Light Emitting Diode, Liquid Crystal Display |
| Component | Display Modules, Sensors, Processing Units, Connectivity Modules |
| Platform | Airborne Platforms, Land Platforms, Naval Platforms |
| Application | Navigation And Situational Awareness; Target Acquisition; Mission Planning; Training And Simulation; Night Vision Operations; Weapon Aiming And Control |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Germany; Brazil; USA; UK; Japan |
| Key Companies Profiled | BAE Systems plc, Collins Aerospace (RTX Corporation), Elbit Systems Ltd., HTC Corporation, L3Harris Technologies, Inc., Leonardo DRS, Inc., Sony Corporation, Thales Group, and Varjo Technologies Oy. |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using platform adoption, component mix, aircraft upgrade timing, training-system demand, country growth, and provider portfolio review. |
How is the market segmented?
-
By Product:
- Helmet Mounted Displays
- Fixed Wing Helmet Mounted Displays
- Rotary Wing Helmet Mounted Displays
- Ground Combat Helmet Displays
- Naval Helmet Mounted Displays
- Helmet Mounted Sights
- Targeting Sights
- Night Vision Sights
- Helmet Mounted Tracking Systems
- Optical Tracking Systems
- Magnetic Tracking Systems
- Helmet Mounted Displays
-
By Technology:
- Augmented Reality Displays
- Waveguide Based Displays
- Projection Based Displays
- Virtual Reality Displays
- Immersive Simulation Displays
- Mixed Reality Displays
- Fused Reality Systems
- Augmented Reality Displays
-
By Display Technology:
- Organic Light Emitting Diode
- Liquid Crystal Display
- Liquid Crystal On Silicon
- Micro Light Emitting Diode
- Organic Light Emitting Diode
-
By Component:
- Display Modules
- Optical Engines
- Micro Displays
- Sensors
- Position Sensors
- Tracking Sensors
- Processing Units
- Graphics Processors
- Control Units
- Connectivity Modules
- Wired Interfaces
- Wireless Interfaces
- Display Modules
-
By Platform:
- Airborne Platforms
- Fighter Aircraft
- Helicopters
- Land Platforms
- Soldier Modernization Systems
- Armored Vehicle Integration
- Naval Platforms
- Naval Aviation
- Shipborne Combat Systems
- Airborne Platforms
-
By Application:
- Navigation And Situational Awareness
- Target Acquisition
- Mission Planning
- Training And Simulation
- Night Vision Operations
- Weapon Aiming And Control
-
By Region:
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa