- Market Value (2025): USD 0.5 Bn
- Estimated Value (2026): USD 0.6 Bn
- Forecast Value (2036): USD 1.4 Bn
- CAGR (2026-2036): 9.1%
What is the Lithium Fluoride Market forecast to be worth by 2036?
USD 0.6 billion in 2026 to USD 1.4 billion by 2036 at a 9.1% CAGR.
- The lithium fluoride market reached USD 0.5 billion in 2025.
- Demand is projected to increase from USD 0.6 billion in 2026 to USD 1.4 billion by 2036.
- The market is projected to expand at a 9.1% CAGR from 2026 to 2036.
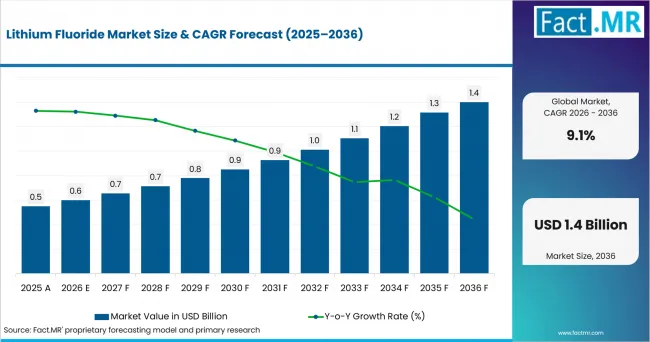
Lithium Fluoride Market Value Analysis | Source: Fact.MR
What are the defining numbers behind Lithium Fluoride Market growth?
An absolute opportunity of USD 0.8 billion is expected between 2026 and 2036.
- Demand Drivers in the Market
- High-purity lithium chemistry is gaining importance as battery and electronics producers tighten impurity limits across qualified material streams. U.S. Department of Energy programs continue to support domestic battery materials processing and advanced battery manufacturing, creating broader demand for specialty lithium compounds used in research, electrolyte development and high-specification chemical processing.
- Battery developers are increasingly engineering fluorine-rich interphases to improve cell stability under demanding operating conditions. U.S. national-laboratory research published through OSTI in 2026 reported durable LiF-rich interphase formation in lithium-ion electrolyte systems. This expands the technical relevance of lithium fluoride alongside battery chemicals and advanced electrolyte formulations.
- Fluoride-salt nuclear systems create a specialized demand pool for tightly controlled lithium fluoride. The U.S. Department of Energy reports that Kairos Power has operated large FLiBe molten-salt systems and is developing reactor-grade FLiBe production capacity. This links LiF demand to advanced nuclear programs rather than commodity chemical consumption alone, complementing growth in electrolyte additives and other high-purity fluorinated materials.
- Optical-grade LiF remains difficult to substitute in deep-ultraviolet and vacuum-ultraviolet uses. Crystran documents transmission from about 0.12 to 6 micrometres and commercial use in special UV optics and X-ray monochromator plates. This creates a premium market tied to precision optics, laser systems and electronic materials rather than to bulk tonnage, adjacent to semiconductor materials supply chains.
- Metallurgy continues to provide the broadest volume base because fluoride chemistry is used in metal-production and processing environments, while industrial users also require stable particle size and controlled chemistry. American Elements identifies LiF for metal-production and optical-deposition uses and supplies multiple purity levels and physical forms. The same qualification logic supports demand across electronic chemicals where contamination control is central to process yield.
- Key Segments Analyzed
- High Purity Lithium Fluoride accounts for 64.7% of Product in 2026. Battery, nuclear, semiconductor and optical applications require tight control of metallic impurities, moisture and batch consistency, which supports demand for higher-purity grades.
- Metallurgy Applications hold 38.9% of Application in 2026. Aluminum and steel processing consume fluoride materials in larger industrial volumes than more specialized optical or research uses.
- Metallurgical Industry represents 52.6% of End Use in 2026. Aluminum producers and steel-industry users purchase lithium fluoride as a recurring process input, supporting repeat industrial demand.
- High Purity Synthesis Technology accounts for 47.3% of Technology in 2026. Electronic, nuclear and optical grades require controlled synthesis and purification to limit trace contaminants and moisture.
- Powdered Lithium Fluoride holds 61.8% of Formulation in 2026. Powdered material is easier to meter, blend and introduce into metallurgy, chemical synthesis and research processes than finished crystal forms.
- Direct Industrial Sales account for 58.4% of Distribution Channel in 2026. Large buyers often work directly with suppliers to qualify purity, particle size, packaging, analytical documentation and delivery schedules.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Senior Consultant, Fact.MR, states, "Lithium fluoride is a specification-led material market. Metallurgical users need dependable bulk chemistry, while battery, nuclear and optical buyers place much more weight on impurity control, isotopic or moisture specifications, particle form and analytical documentation. Suppliers that can separate these grade architectures clearly and support repeat qualification will capture more value than companies competing only on nominal LiF purity."
- Strategic Implications
- Suppliers should separate metallurgical, electronic, nuclear and optical grades because each customer group has different requirements for purity, moisture control and physical form.
- Battery-material developers need to evaluate lithium fluoride alongside the wider electrolyte and interphase system. Its value depends on how it performs within the complete formulation rather than on fluoride content alone.
- Nuclear applications require tighter control of composition, trace contaminants, packaging and batch consistency. Molten-salt systems are sensitive to material purity and compatibility, making supplier qualification more demanding.
- Optical suppliers compete on crystal quality, polishing and transmission performance. For LiF windows and related components, usable optical performance matters more than the underlying powder cost.
- Distributors are better suited to laboratory and pilot-scale demand where small pack sizes and availability matter. Direct suppliers are more relevant for bulk volumes, custom specifications and tightly controlled supply arrangements.
How does the Lithium Fluoride Market break down by segment?
The Lithium Fluoride Market is segmented by Product, Application, End Use, Technology, Formulation and Distribution Channel.
Why does High Purity Lithium Fluoride lead Product?
High Purity Lithium Fluoride holds a 64.7% share of Product in 2026.
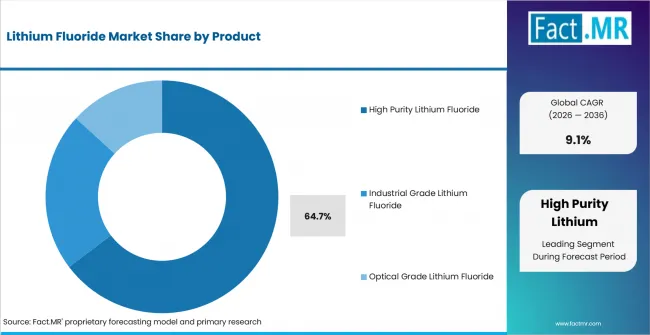
Lithium Fluoride Market Analysis By Product | Source: Fact.MR
High-purity material carries more value because electronics, nuclear and optical applications are sensitive to trace contaminants. Metallic impurities, moisture and unwanted ionic species can alter melt behavior, optical transmission, crystal quality or electrochemical performance, so buyers commonly define acceptance through certificates of analysis and tighter specification limits.
American Elements offers lithium fluoride across multiple high-purity grades up to 99.999%, illustrating the commercial separation between ordinary industrial material and specification-intensive products. Electronic-grade and nuclear-grade LiF therefore support higher unit values even when the absolute tonnage is below broad metallurgical consumption.
Why do Metallurgy Applications lead Application?
Metallurgy Applications hold a 38.9% share of Application in 2026.
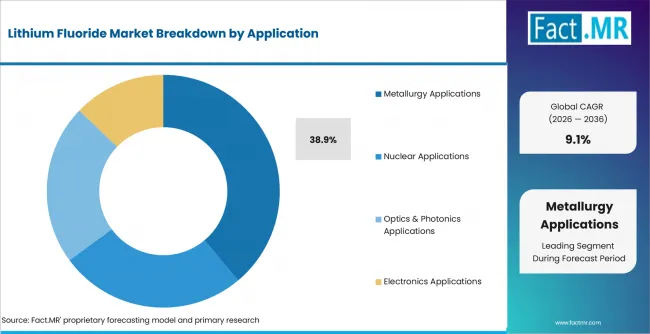
Lithium Fluoride Market Analysis By Application | Source: Fact.MR
Metallurgy leads because LiF is used in metal-production environments where fluoride chemistry can influence melt behavior and process control. These applications create recurring industrial volumes that are larger and less project-specific than optical windows, laboratory materials or nuclear-development programs.
Industrial users also value consistent powder size, low contamination and reliable bulk availability. The application therefore combines a broad installed process base with repeat purchasing, while nuclear and photonics applications remain technically important but narrower in volume.
Why does Metallurgical Industry lead End Use?
Metallurgical Industry holds a 52.6% share of End Use in 2026.
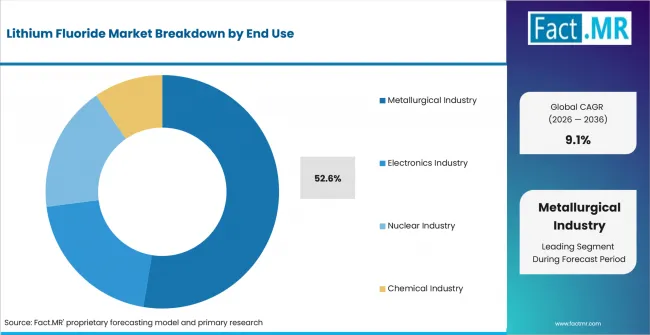
Lithium Fluoride Market Analysis By End Use | Source: Fact.MR
Aluminum producers and steel-industry users purchase fluorides through established process-chemical supply chains. Once a grade and supplier are qualified for a melt or treatment step, switching can require process checks and new material validation, which supports recurring industrial demand.
The end-use segment also benefits from scale. Metallurgical facilities buy material in larger lots than universities, optical laboratories or specialty electronics users, so industrial tonnage remains the main revenue anchor even as higher-purity niches grow more quickly.
Why does High Purity Synthesis Technology lead Technology?
High Purity Synthesis Technology holds a 47.3% share of Technology in 2026.
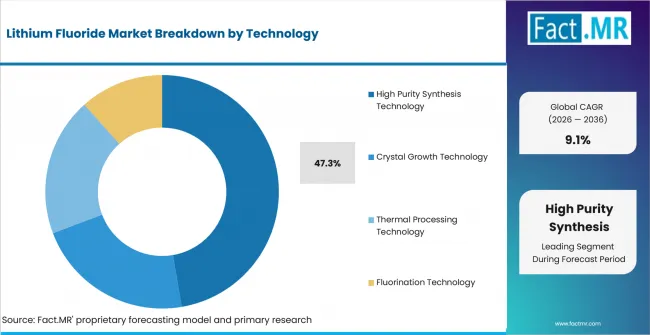
Lithium Fluoride Market Analysis By Technology | Source: Fact.MR
High-purity synthesis leads because advanced LiF applications depend on controlling contaminants before the material reaches crystal growth, battery research or nuclear-salt preparation. Chemical precipitation and vacuum-based purification routes give producers more control over ionic impurities and volatile residues than simple industrial conversion alone.
The premium comes from repeatability rather than chemistry identity. Buyers need the same impurity profile from lot to lot, supported by analytical testing and packaging that prevents recontamination during shipment and storage.
Why does Powdered Lithium Fluoride lead Formulation?
Powdered Lithium Fluoride holds a 61.8% share of Formulation in 2026.
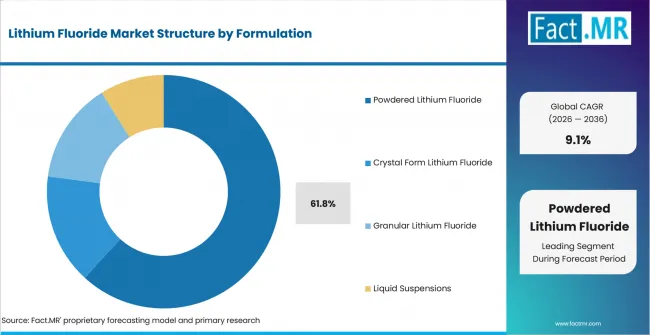
Lithium Fluoride Market Analysis By Formulation | Source: Fact.MR
Powder dominates because it can be weighed, blended and introduced directly into metallurgy, chemical synthesis and research workflows. Micro-fine powders support controlled mixing, while industrial powders provide a practical format for larger-volume processing.
Crystal forms remain essential for optics and selected nuclear or research uses, but they require additional crystal-growth and finishing steps. Granules and suspensions solve handling needs in specific processes, yet powder offers the widest cross-application flexibility.
Why do Direct Industrial Sales lead Distribution Channel?
Direct Industrial Sales hold a 58.4% share of Distribution Channel in 2026.
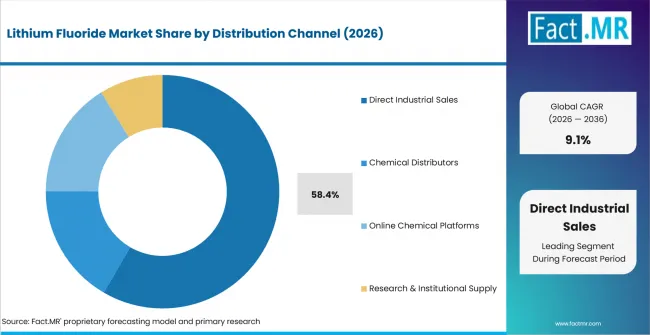
Lithium Fluoride Market Analysis By Distribution Channel | Source: Fact.MR
Large metallurgical, electronics and chemical buyers often require negotiated specifications, certificates of analysis, packaging controls and delivery schedules. Direct relationships make it easier to approve a grade, manage changes and maintain continuity when LiF is embedded in a qualified process recipe.
Distributors and online platforms remain important for research quantities and standard grades. Direct sales lead because the larger contracts are tied to OEM supply agreements and enterprise purchasing where technical qualification is more involved.
What is accelerating Lithium Fluoride Market adoption, and what is holding it back?
Adoption is accelerating through battery-material development, high-purity electronics demand, advanced molten-salt nuclear programs and sustained metallurgical use. The main constraints are lithium and fluorine feedstock volatility, stringent impurity control, limited suppliers for optical or nuclear grades, hazardous-material handling requirements and substitution by other fluoride compounds where LiF does not deliver a clear process advantage.
Drivers Impact Analysis
| Factor | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growth in high-purity battery and electrolyte materials | +1.6% | South Korea, USA, Japan, Germany and UK | Short term (2 years or less) |
| Recurring metallurgical fluoride demand | +1.4% | Global industrial markets | Short term (2 years or less) |
| Expansion of advanced nuclear fluoride-salt programs | +1.2% | USA and UK | Medium term (2-4 years) |
| Semiconductor and optical-grade material qualification | +0.9% | South Korea, Japan, Germany and UK | Medium term (2-4 years) |
| Localization of lithium and battery-material supply chains | +0.7% | USA, South Korea, Japan and Europe | Long term (4 years or more) |
Opportunity Impact Analysis
| Factor | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| LiF-rich battery interphase and electrolyte development | +1.3% | South Korea, USA, Japan and Germany | Medium term (2-4 years) |
| Reactor-grade FLiBe and advanced molten-salt systems | +1.1% | USA and UK | Long term (4 years or more) |
| VUV, UV and X-ray optical crystal demand | +0.9% | UK, Germany, Japan and USA | Medium term (2-4 years) |
| Electronic-grade and semiconductor chemical supply | +0.8% | South Korea, Japan, USA and Germany | Short term (2 years or less) |
| Custom particle-size and high-purity direct contracts | +0.6% | Global specialty-chemical buyers | Medium term (2-4 years) |
Restraints Impact Analysis
| Factor | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Lithium and fluorine feedstock cost volatility | -1.2% | Global | Short term (2 years or less) |
| High purification and analytical-control cost | -1.0% | Electronic, optical and nuclear grades | Short term (2 years or less) |
| Limited qualification base for reactor-grade material | -0.8% | USA and UK | Medium term (2-4 years) |
| Handling, toxicity and packaging requirements | -0.7% | Global chemical markets | Medium term (2-4 years) |
| Substitution by alternative fluoride compounds | -0.5% | Metallurgy and specialty chemistry | Long term (4 years or more) |
Which countries are scaling the Lithium Fluoride Market through 2036?
- South Korea’s battery policy supports next-generation cell development, materials R&D and domestic supply-chain investment. This creates demand for high-purity lithium and fluorinated materials used in electrochemical testing and qualification.
- Germany combines battery-cell development with semiconductor and advanced-materials manufacturing. These industries create demand for high-purity lithium fluoride across chemical, electronic and optical applications.
- In the USA, battery-material manufacturing and fluoride-salt reactor development create demand at both research and industrial scale. High-purity powders are particularly relevant where impurity control and chemical consistency are critical.
- Japan’s 2026 Battery and Power Industry Strategy supports domestic manufacturing and next-generation battery commercialization. This sustains demand for specialty lithium compounds and electronic-grade materials.
- The UK has demand from battery innovation, advanced nuclear development and precision optics. These applications support high-purity lithium fluoride for research, reactor-related chemistry and UV and X-ray optical components.
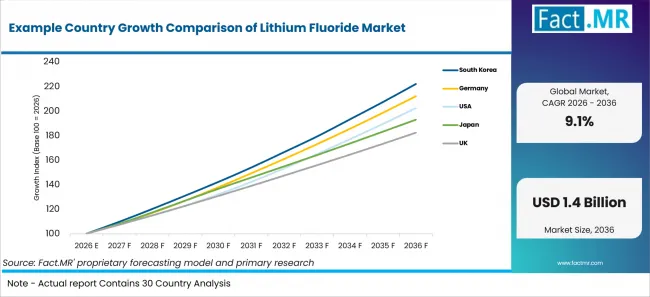
Example Country Growth Comparison Of Lithium Fluoride Market | Source: Fact.MR
| Country | CAGR, 2026-2036 |
|---|---|
| South Korea | 8.3% |
| Germany | 7.8% |
| USA | 7.3% |
| Japan | 6.8% |
| UK | 6.2% |
What is driving South Korea's growth through 2036?
South Korea is projected to expand at an 8.3% CAGR from 2026 to 2036.
South Korea is continuing to invest in next-generation battery technology and domestic supply-chain competitiveness. Government policy in 2025 expanded support for solid-state battery R&D and broader K-battery competitiveness, reinforcing demand for high-purity lithium and fluorine-containing materials used in electrochemical development and qualification.
The country also combines major battery producers with a large semiconductor and electronics manufacturing base. That mix supports electronic-grade LiF, research powders and specialty formulations where trace contamination and supplier consistency matter more than commodity pricing.
What is driving Germany's growth through 2036?
Germany is projected to expand at a 7.8% CAGR from 2026 to 2036.
Germany continues to support battery-cell development through European IPCEI programs and industrial R&D that covers next-generation lithium-ion and all-solid-state technologies. This creates a technical market for high-purity lithium compounds used in materials research, pilot production and supplier qualification.
The opportunity is reinforced by semiconductor and advanced-materials investment. Germany is coordinating new European advanced-semiconductor projects, which supports demand for high-purity chemical inputs and process materials alongside the country’s established optical and specialty-chemical industries.
What is driving USA's growth through 2036?
USA is projected to expand at a 7.3% CAGR from 2026 to 2036.
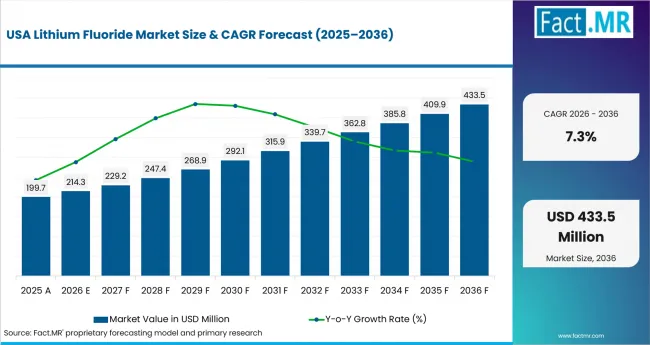
Lithium Fluoride Market Country Value Analysis | Source: Fact.MR
The U.S. Department of Energy continues to fund domestic critical-mineral processing, battery materials and battery manufacturing. These programs increase the number of domestic qualification projects for lithium compounds, electrolyte materials and other high-purity inputs used in advanced cells.
The U.S. also has a distinct nuclear route to demand. DOE has supported Kairos Power’s FLiBe molten-salt testing and salt-production infrastructure, while the Nuclear Regulatory Commission continues to review fluoride-salt-cooled reactor technology. Reactor-grade fluoride programs require tighter chemical specifications than ordinary industrial LiF.
What is driving Japan's growth through 2036?
Japan is projected to expand at a 6.8% CAGR from 2026 to 2036.
Japan revised its Battery Industry Strategy in June 2026 into a Battery and Power Industry Strategy. The plan targets 150 GWh per year of domestic manufacturing capacity from 2030 into the mid-2030s and full-scale commercialization of all-solid-state batteries around 2030.
That strategy supports ongoing demand for high-purity lithium compounds, electrolyte-development materials and specialty chemicals used by battery and electronics companies. Japan’s strong precision-materials base also sustains demand for optical and research-grade LiF outside battery applications.
What is driving UK's growth through 2036?
UK is projected to expand at a 6.2% CAGR from 2026 to 2036.
The UK Battery Strategy is designed to strengthen battery design, manufacturing and supply-chain resilience through 2030, creating a continuing research and pilot-production market for specialty lithium inputs. The country also has active academic and industrial battery-development programs that purchase high-purity chemicals in smaller, specification-sensitive volumes.
Advanced nuclear and optics add separate demand channels. UK government funding has supported molten-salt reactor development, while Crystran supplies LiF optical material for VUV, UV and X-ray applications. This mix gives the market a broader base than battery demand alone.
Who Leads the Lithium Fluoride Market?
Key players in the Lithium Fluoride Market include Morita Chemical Industries Co., Ltd., Crystran Ltd, American Elements, MaTeck GmbH, ProChem Inc., Noah Chemicals, Parad Corporation, Foshan Nanhai Double Fluoride Chemical Co., Ltd., Stanford Advanced Materials, Iwatani Corporation, MilliporeSigma (Merck KGaA), and Nacalai Tesque.
Competition is shaped by purity, moisture control, particle-size consistency, optical quality, analytical documentation and packaging. Requirements become more stringent in nuclear, semiconductor and other high-purity applications, where trace contaminants and batch consistency can affect qualification.
American Elements supplies lithium fluoride in multiple purity grades and physical forms, including powders, granules and optical windows. Crystran focuses on optical-grade LiF crystals for VUV, UV and X-ray applications. Other participants compete through specialty fluoride chemistry, laboratory-grade reagents, technical distribution and the ability to serve both small research orders and recurring industrial demand.
Which companies are the key providers?
Morita Chemical Industries Co., Ltd., Crystran Ltd, American Elements, MaTeck GmbH, ProChem Inc., Noah Chemicals, Parad Corporation, Foshan Nanhai Double Fluoride Chemical Co., Ltd., Stanford Advanced Materials, Iwatani Corporation, MilliporeSigma (Merck KGaA), and Nacalai Tesque
- Morita Chemical Industries Co., Ltd.
- Crystran Ltd
- American Elements
- MaTeck GmbH
- ProChem Inc.
- Noah Chemicals
- Parad Corporation
- Foshan Nanhai Double Fluoride Chemical Co., Ltd.
- Stanford Advanced Materials
- Iwatani Corporation
- MilliporeSigma (Merck KGaA)
- Nacalai Tesque
Bibliography
- U.S. Department of Energy. (2026). Energy Department Announces $500 Million to Secure America’s Critical Mineral and Battery Supply Chains. U.S. Department of Energy.
- U.S. Department of Energy. (2024). Kairos Power Starts Operation of First Molten Salt System. Office of Nuclear Energy.
- U.S. Department of Energy. (2024). Kairos Power Breaks Ground on Molten Salt Production Facility. Office of Nuclear Energy.
- U.S. Nuclear Regulatory Commission. (2026). Backgrounder on New Nuclear Plant Designs. Nuclear Regulatory Commission.
- Office of Scientific and Technical Information. (2026). Trace LiBF4 Enabling Robust LiF-Rich Interphase for Durable Low-Temperature Lithium-Ion Batteries. U.S. Department of Energy.
- Ministry of Trade, Industry and Energy, Republic of Korea. (2025). Measures to Strengthen K-Battery Competitiveness and Next-Generation Battery Technology. Government of the Republic of Korea.
- Federal Ministry for Economic Affairs and Energy, Germany. (2026). Advanced Semiconductor Technologies IPCEI Projects. Federal Government of Germany.
- Federal Ministry for Economic Affairs and Energy, Germany. (2026). Batteries Made in Germany and Battery Cell Production Programs. Federal Government of Germany.
- Ministry of Economy, Trade and Industry, Japan. (2026). Battery and Power Industry Strategy. Government of Japan.
- Department for Business and Trade. (2023). UK Battery Strategy. UK Government.
- Department for Energy Security and Net Zero. (2024). British Nuclear Revival to Move Towards Energy Independence. UK Government.
- Crystran Ltd. (2026). Lithium Fluoride LiF Optical Material Data. Crystran Ltd.
- American Elements. (2026). Lithium Fluoride High-Purity Material and Product Specifications. American Elements.
This Report Answers
- How large is the Lithium Fluoride Market in 2026 and what value is projected for 2036?
- Why do high-purity LiF and metallurgy account for the leading 2026 shares?
- How are battery, nuclear, electronics and optical applications changing purity requirements?
- Why do powders and direct industrial sales remain the main commercial formats?
- How are South Korea, Germany, USA, Japan and UK supporting demand through industrial policy and technology programs?
- Which suppliers compete across industrial, research, optical and high-purity lithium fluoride applications?
What does the Lithium Fluoride Market cover?
The Lithium Fluoride Market covers commercial lithium fluoride sold as high-purity, industrial and optical material for metallurgy, nuclear, optics and photonics, electronics and specialty chemical applications. Revenue includes LiF powder, crystal, granule and suspension forms when lithium fluoride is the separately priced commercial product.
The assessment covers the specified Product, Application, End Use, Technology, Formulation and Distribution Channel hierarchy across the five supplied country markets and the broader global demand base.
What is included in the scope?
Included products comprise High Purity Lithium Fluoride, Industrial Grade Lithium Fluoride and Optical Grade Lithium Fluoride. Applications include metallurgy, nuclear, optics and photonics, and electronics, while end users include metallurgical, electronics, nuclear and chemical industries.
Technology coverage includes high-purity synthesis, crystal growth, thermal processing and fluorination. Formulations include powder, crystal, granular and liquid suspension forms. Distribution covers direct industrial sales, chemical distributors, online chemical platforms and research or institutional supply.
What is excluded from the scope?
The scope excludes other lithium salts such as lithium carbonate, lithium hydroxide, lithium chloride and lithium acetate when sold independently of lithium fluoride. It also excludes other fluoride compounds such as sodium fluoride, magnesium fluoride and calcium fluoride unless the commercial product is specifically LiF.
Finished batteries, complete electrolyte systems, aluminum or steel products, nuclear reactors, optical assemblies and semiconductor devices are excluded except for the revenue attributable to lithium fluoride itself. General laboratory services and contract processing are also excluded when LiF is not separately sold.
How Was the Analysis Built?
The analysis combines market-specific primary research with desk research on metallurgy, battery materials, advanced nuclear systems, optical materials, electronics supply chains and specialty chemical distribution across the specified countries and segment hierarchy.
- Primary Research: Interviews with fluoride-chemical suppliers, metallurgical procurement teams, battery-material developers, optical-component producers, nuclear-material specialists, laboratory distributors and electronics-material buyers examine purity requirements, physical form, packaging, qualification, contract structures and substitution behavior.
- Desk Research: The review covers government battery and industrial strategies, advanced nuclear programs, public research on LiF-rich electrochemical interfaces, optical-material specifications and first-party supplier product information. External sources used in the article are recorded in the bibliography.
- Market Sizing and Forecasting: Estimates combine LiF volume and value by grade, application intensity, end-user demand, synthesis technology, physical formulation, direct versus distributor purchasing and country-level battery, metallurgy, electronics, optical and nuclear activity.
- Data Validation and Update Cycle: Findings are cross-checked against public industrial programs, supplier specifications, technology-development milestones and primary interviews. Updates account for lithium feedstock conditions, high-purity qualification, battery technology, nuclear-project timing, optical demand and supplier availability.
What is the report's scope and coverage?
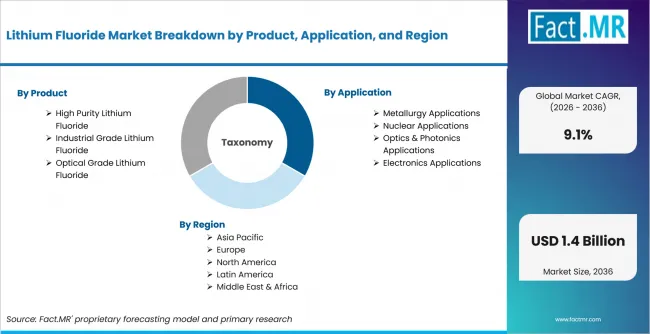
Lithium Fluoride Market Breakdown By Product, Application, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Commercial lithium fluoride in high-purity, industrial and optical grades used in metallurgy, nuclear, optics and photonics, electronics and specialty chemical applications |
| Segments Covered | Product; Application; End Use; Technology; Formulation; Distribution Channel |
| Regions Covered | North America; Latin America; Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | South Korea; Germany; USA; Japan; UK |
| Key Companies Profiled | Morita Chemical Industries Co., Ltd., Crystran Ltd, American Elements, MaTeck GmbH, ProChem Inc., Noah Chemicals, Parad Corporation, Foshan Nanhai Double Fluoride Chemical Co., Ltd., Stanford Advanced Materials, Iwatani Corporation, MilliporeSigma (Merck KGaA), and Nacalai Tesque |
| Base Year | 2025 |
| Base Year Value | USD 0.5 billion |
| Estimated Value (2026) | USD 0.6 billion |
| Forecast Value (2036) | USD 1.4 billion |
| Forecast CAGR (2026-2036) | 9.1% |
| Absolute Opportunity (2026-2036) | USD 0.8 billion |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid demand-side and top-down methodology using grade mix, application demand, industrial qualification, physical form, channel structure and country-level market validation |
How is the market segmented?
-
By Product:
- High Purity Lithium Fluoride
- Electronic Grade LiF
- Nuclear Grade LiF
- Industrial Grade Lithium Fluoride
- Metallurgical Grade LiF
- Ceramic Grade LiF
- Optical Grade Lithium Fluoride
- UV Optical Materials
- Photonics Grade Materials
- High Purity Lithium Fluoride
-
By Application:
- Metallurgy Applications
- Aluminium Processing
- Steel Manufacturing
- Nuclear Applications
- Nuclear Fuel Processing
- Radiation Shielding
- Optics & Photonics Applications
- Laser Technology
- Infrared Systems
- Electronics Applications
- Semiconductor Manufacturing
- Display Technologies
- Metallurgy Applications
-
By End Use:
- Metallurgical Industry
- Aluminium Producers
- Steel Industry
- Electronics Industry
- Semiconductor Manufacturers
- Optoelectronics Firms
- Nuclear Industry
- Nuclear Energy Operators
- Research Institutions
- Chemical Industry
- Specialty Chemical Producers
- Fluoride Chemical Manufacturers
- Metallurgical Industry
-
By Technology:
- High Purity Synthesis Technology
- Chemical Precipitation Systems
- Vacuum Distillation Systems
- Crystal Growth Technology
- Single Crystal Growth Systems
- Polycrystalline Formation Systems
- Thermal Processing Technology
- High Temperature Processing
- Vacuum Thermal Systems
- Fluorination Technology
- Gas Phase Fluorination
- Solid Phase Fluorination
- High Purity Synthesis Technology
-
By Formulation:
- Powdered Lithium Fluoride
- Micro Fine Powders
- Industrial Powders
- Crystal Form Lithium Fluoride
- Single Crystal Formulations
- Polycrystalline Forms
- Granular Lithium Fluoride
- Coarse Granules
- Controlled Size Granules
- Liquid Suspensions
- Chemical Suspension Systems
- Solution Based Forms
- Powdered Lithium Fluoride
-
By Distribution Channel:
- Direct Industrial Sales
- OEM Supply Contracts
- Enterprise Supply Deals
- Chemical Distributors
- Specialty Chemical Distributors
- Regional Distributors
- Online Chemical Platforms
- B2B Chemical Marketplaces
- Manufacturer Direct Platforms
- Research & Institutional Supply
- Government Supply Channels
- Academic Supply Channels
- Direct Industrial Sales
-
By Region:
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa

