- Market Value (2025): USD 1.3 Bn
- Estimated Value (2026): USD 1.5 Bn
- Forecast Value (2036): USD 4.5 Bn
- CAGR (2026-2036): 11.5%
What is the Offshore Drone Inspection Market forecast to be worth by 2036?
USD 1.5 billion in 2026 to USD 4.5 billion by 2036 at 11.5% CAGR.
- The Offshore Drone Inspection Market reached USD 1.3 billion in 2025.
- Demand is projected to increase from USD 1.5 billion in 2026 to USD 4.5 billion by 2036.
- The market is forecast to record 11.5% CAGR from 2026 to 2036 as offshore energy operators shift inspection work toward safer remote data capture.
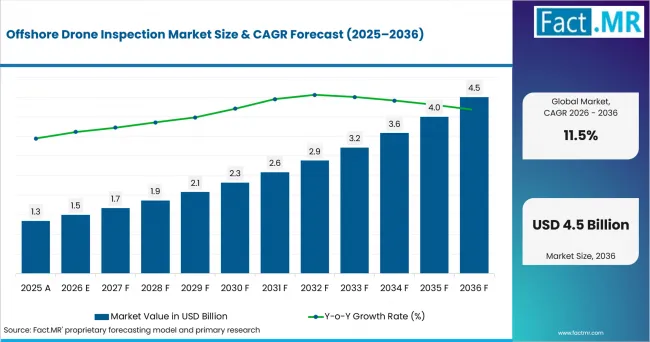
Offshore Drone Inspection Market Value Analysis | Source: Fact.MR
What are the defining numbers behind Offshore Drone Inspection Market growth?
USD 3.0 billion absolute opportunity by 2036, led by Autonomous Navigation Systems, Filming and Photography and Oil and Gas Rigs.
- Demand Drivers in the Market
- Oil and gas operators need faster inspection access for flare stacks, tanks and platform modules. BSEE reported in April 2026 that U.S. Outer Continental Shelf oil production reached 714 million barrels in 2025.
- Offshore wind owners need blade and foundation images that support maintenance planning before longer turbine downtime develops. RTE reported in April 2026 that French offshore wind generation reached 5.7 TWh in 2025.
- Port authorities need aerial views of quay walls, cranes and marine traffic areas while inspectors stay clear of moving cargo operations.
- Inspection contractors need repeatable reporting workflows so drone imagery becomes asset records for engineers across inspection cycles.
- Key Segments Analyzed
- By Product: Fixed Wing Drones are projected to hold 23.80% share in 2026 owing to the endurance needs of UAV inspection drones used across offshore routes.
- By Application: Filming and Photography is estimated to account for 36.80% share in 2026 as drone services continue to provide asset imagery for offshore operators.
- By End Use: Oil and Gas Rigs are anticipated to represent 35.70% share in 2026 due to inspection requirements across remote inspection and NDT services.
- By Technology: Autonomous Navigation Systems are forecast to capture 63.90% share in 2026, supported by route repeatability in industrial drone inspection work.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Offshore drone inspection is increasingly becoming part of a structured asset-integrity workflow. Service quality depends on disciplined flight operations, inspection-grade reporting and offshore access planning, with pilots, sensors and engineering review integrated into one auditable process.”
- Strategic Implications
- Service providers should build inspection packages around specific offshore tasks such as tank interiors, blade checks and topside corrosion screening.
- Drone platform vendors should document endurance, payload performance and wind limits under marine operating conditions.
- Asset owners should connect drone imagery with maintenance systems so inspection findings move directly into repair planning.
- Inspection teams should keep aviation approval, safety training and offshore access steps in one documented workflow for each site.
USA is projected to record 12.5% CAGR through 2036 through offshore oil production and platform inspection needs. UK is estimated to post 10.2% as port and offshore wind work increases. South Korea reaches 10.1% through port throughput. France records 9.5% through offshore wind output. Germany posts 8.8%, Japan reaches 8.5%, and Italy records 7.3%.
How does the Offshore Drone Inspection Market break down by segment?
Autonomous Navigation Systems lead at 63.90%; Filming and Photography leads at 36.80%.
Which Product type leads demand?
Fixed Wing Drones hold 23.80% share in 2026.
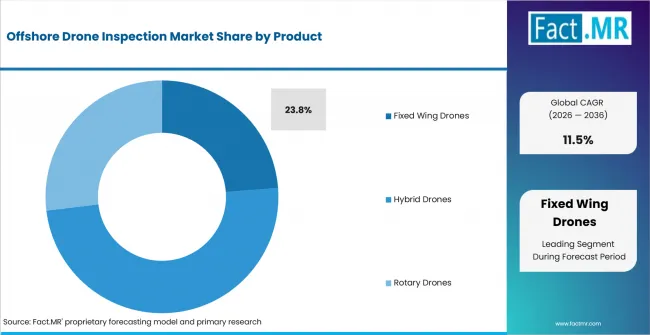
Offshore Drone Inspection Market Analysis By Product | Source: Fact.MR
Fixed Wing Drones are projected to lead Product demand owing to longer flight endurance over offshore routes. Long Endurance Drones support wider area coverage where launch points are limited. Hybrid Drones remain useful near vessels or platforms. Rotary Drones retain value for close-range hovering.
What leads the Application segment?
Filming and Photography account for 36.80% share in 2026.
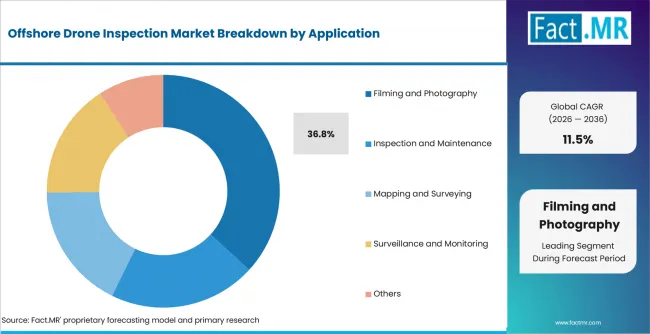
Offshore Drone Inspection Market Analysis By Application | Source: Fact.MR
Filming and Photography are estimated to lead Application demand as offshore users still require high-quality visual proof of asset condition. Drone filming services make visual records easier to package into client reports. Inspection and Maintenance tasks add structural views and equipment checks. Mapping, Surveying and Monitoring applications expand where ports and offshore wind farms need repeatable records.
How does End Use shape demand?
Oil and Gas Rigs represent 35.70% share in 2026.
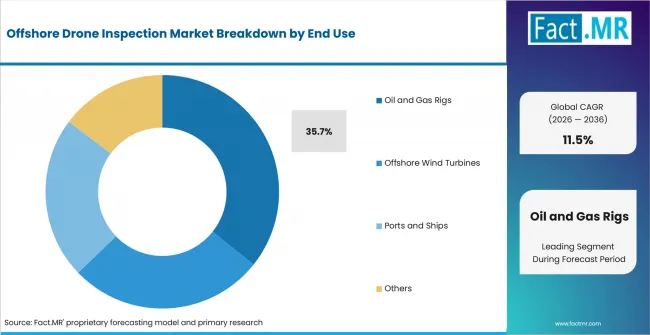
Offshore Drone Inspection Market Analysis By End Use | Source: Fact.MR
Oil and Gas Rigs are anticipated to hold the primary displayed End Use share due to recurring inspection work on topsides, tanks and supporting structures. Wind turbine drone inspection supports offshore wind work as turbines need blade and nacelle checks. Ports and Ships create additional routes where vessel inspection data supports maintenance decisions.
What supports Technology adoption?
Autonomous Navigation Systems capture 63.90% share in 2026.
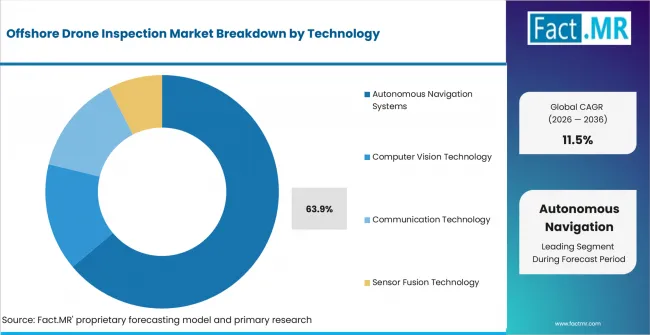
Offshore Drone Inspection Market Analysis By Technology | Source: Fact.MR
Autonomous Navigation Systems are forecast to lead Technology demand because offshore inspections benefit from repeatable path planning around hazardous structures. Thermal drone inspection adds value where heat signatures support electrical or mechanical checks. Sensor fusion technologies support safer flight control where weather and metallic structures affect manual operation.
What is accelerating Offshore Drone Inspection Market adoption, and what is holding it back?
Safety-led remote inspection drives it; offshore operating constraints restrain it.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Safer access to offshore structures | +1.8% | Global | Short term (<= 2 years) |
| Oil and gas inspection cycles | +1.5% | North America, Europe | Short term (<= 2 years) |
| Offshore wind blade and foundation checks | +1.3% | Europe, East Asia | Medium term (2-4 years) |
| Autonomous image capture and reporting | +1.0% | Global | Medium term (2-4 years) |
- Safer access to offshore structures: Drones can reduce the need for rope access or vessel-supported close inspection around flare stacks, towers, and confined offshore structures. Adoption is supported where operators accept drone-generated imagery and inspection records within formal maintenance and integrity workflows.
- Oil and gas inspection cycles: Offshore platforms require recurring visual checks to support safe operations, maintenance planning, and repair decisions. Drone programs can provide engineers with faster condition data between shutdown windows and reduce dependence on manual access for routine inspection tasks.
- Offshore wind blade and foundation checks: Larger turbine blades, towers, and foundations increase the value of rapid visual screening. Operating offshore wind assets create recurring inspection routes where drones can support blade assessment, corrosion checks, coating review, and foundation monitoring.
- Autonomous image capture and reporting: Repeatable flight paths allow teams to compare asset condition across multiple inspection rounds. Structured image libraries become more valuable when engineers track corrosion, blade damage, coating defects, and other changes over time.
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Autonomous docked offshore inspections | +1.2% | North America, Europe | Medium term (2-4 years) |
| Port and vessel inspection services | +0.9% | Europe, East Asia | Short term (<= 2 years) |
| Gas, thermal and corrosion sensing payloads | +0.8% | Global | Medium term (2-4 years) |
| Drone and robotic crawler service bundles | +0.7% | Global | Long term (>= 4 years) |
- Autonomous docked offshore inspections: Permanent drone stations can support scheduled inspections where regulations and site conditions allow. Docked systems can improve inspection frequency, reduce mobilization effort, and connect recurring aerial data with broader asset-management platforms used by energy, utility, and industrial operators.
- Port and vessel inspection services: Ports create demand for visual checks of cranes, quay walls, vessels, and surrounding infrastructure. Drone services can shorten inspection time around active cargo areas and improve documentation without relying entirely on manual access.
- Gas, thermal and corrosion sensing payloads: Diverse sensor payloads allow drone teams to move beyond basic photography. Thermal imaging, gas detection, and corrosion-focused inspection tools can support asset-integrity decisions when results fit existing offshore engineering and maintenance procedures.
- Drone and robotic crawler service bundles: Some offshore inspections require both aerial access and contact-based measurement. Bundling drones, robotic crawlers, and ROV services can help contractors cover confined, elevated, and subsea locations while giving operators a more integrated inspection workflow through a single service partner.
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Weather and marine operating windows | -0.8% | Global | Short term (<= 2 years) |
| Flight approvals near active assets | -0.6% | North America, Europe, East Asia | Medium term (2-4 years) |
| Data acceptance and report validation | -0.5% | Global | Medium term (2-4 years) |
| Payload endurance and saltwater exposure | -0.4% | Global | Long term (>= 4 years) |
- Weather and marine operating windows: Offshore wind, rain and salt spray reduce safe flight time. Inspection teams must plan around vessel schedules and daylight. The constraint is expected to keep experienced offshore operators ahead of generic drone service teams.
- Flight approvals near active assets: Offshore sites often require aviation checks, hot-work controls and site-specific safety permits. These steps lengthen mobilization for new providers. Contractors with repeat approval records are expected to move faster from booking to flight execution.
- Data acceptance and report validation: Drone imagery only creates value when engineers accept the file quality and defect classification. Clients need consistent naming, location tags and image resolution. Providers that standardize reports are better placed for repeat work.
- Payload endurance and saltwater exposure: Marine environments place stress on batteries, rotors, sensors and landing systems. Waterproof Drone designs support wet and saline operating areas. Service margins remain tied to maintenance cost and replacement-part availability.
Which countries are scaling Offshore Drone Inspection Market through 2036?
- The country comparison spans 5.2 percentage points and forms three practical growth bands across the forecast period.
- USA remains 2.3 percentage points above UK through offshore oil production and platform inspection cycles.
- UK remains 0.1 percentage point above South Korea as port cargo documentation and offshore wind logistics support inspection work.
- South Korea tracks 0.6 percentage point above France through port activity and offshore wind project selection.
- France remains 0.7 percentage point above Germany as offshore wind generation extends inspection needs.
- Germany remains 0.3 percentage point above Japan through wind-farm operating capacity and inspection discipline.
- Japan remains 1.2 percentage points above Italy as offshore wind policy and port activity support demand.
Full report coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, Middle East & Africa.
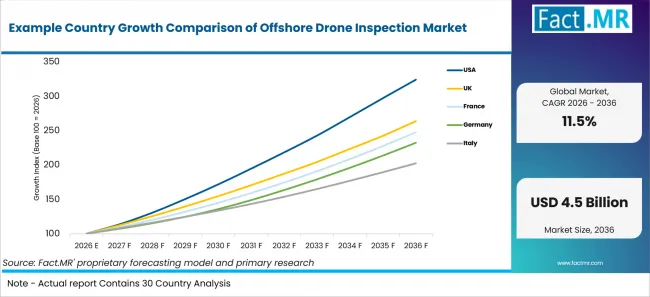
Example Country Growth Comparison Of Offshore Drone Inspection Market | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| USA | 12.5% |
| UK | 10.2% |
| South Korea | 10.1% |
| France | 9.5% |
| Germany | 8.8% |
| Japan | 8.5% |
| Italy | 7.3% |
What supports USA adoption?
12.5% CAGR through 2036, driven by offshore oil production and platform inspection cycles.
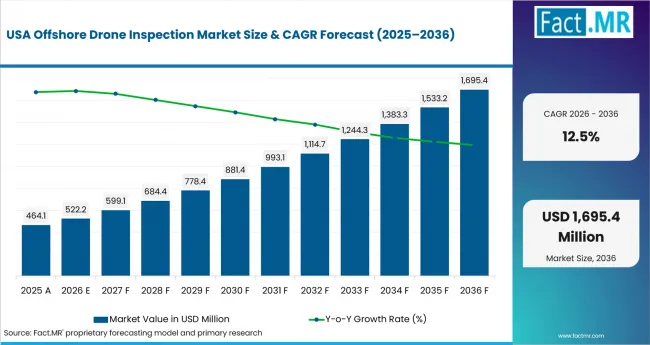
Offshore Drone Inspection Market Country Value Analysis | Source: Fact.MR
U.S. offshore demand is shaped by active oil and gas platforms that require recurring checks around topsides, tanks and safety-sensitive structures. The market is projected to record 12.5% CAGR through 2036 as service teams use drones to reduce rope access during inspection planning.
How is UK demand scaling?
10.2% CAGR through 2036, supported by offshore wind cargo handling and port inspection needs.
The UK outlook is tied to offshore wind logistics and inspection routes around ports, quays and turbine components. Demand is estimated to post 10.2% CAGR through 2036 as operators request visual documentation for marine construction and maintenance.
What underpins South Korea growth?
10.1% CAGR through 2036, driven by port throughput and offshore wind project selection.
South Korea’s port base gives drone teams a strong case for documentation around terminals, vessels and offshore project sites. The Ministry of Oceans and Fisheries reported in January 2026 that national port container throughput reached 32.11 million TEU in 2025.
What supports France adoption?
9.5% CAGR through 2036, led by offshore wind output and marine infrastructure inspection.
France is building a wider offshore inspection base through turbine generation, port work and marine engineering activity. EUR-Lex published in September 2025 the EU state-aid authorization for France’s offshore wind support scheme under case SA.115764, which had an overall budget of EUR 11.34 billion.
How does Germany perform?
8.8% CAGR through 2036, supported by operating offshore wind capacity and grid-fed output.
Germany’s offshore wind fleet creates repeat flight paths across North Sea and Baltic assets. Bundesnetzagentur reported in January 2026 that installed offshore wind capacity reached 9.5 GW at the end of 2025.
What supports Japan demand?
8.5% CAGR through 2036, driven by port activity and offshore wind project formation.
Japan’s offshore wind pipeline gives inspection providers a longer-term route into ports, vessels and turbine work. METI stated in March 2025 that Japan targets 10 million kW of offshore wind project formation by 2030.
How is Italy developing demand?
7.3% CAGR through 2036, shaped by offshore hub investment and port-side inspection routes.
Italy’s port-led opportunity is shaped by offshore hub investment at Augusta and Taranto. Italy’s Ministry of Infrastructure and Transport stated in July 2025 that EUR 78.3 million in investments would be distributed over three years starting in 2025 for the development of offshore hubs at Augusta and Taranto.
Who leads the Offshore Drone Inspection Market?
Sky-Futures is active through ABS-recognized UAS visual inspection and NDT capabilities for offshore installations. MISTRAS Group uses unmanned aerial, land-based and subsea systems in access services. SkySpecs supports offshore wind inspection through autonomous turbine inspection workflows.
Cyberhawk is relevant through drone-based critical infrastructure inspection and visual data management for energy customers. Ondas announced in June 2026 that Cyberhawk had operations in 40 countries and more than 300 customers. Competition is shaped by offshore access experience and accepted reporting.
Which companies are the key providers?
Key companies include Sky-Futures Ltd.; MISTRAS Group; SkySpecs; and Cyberhawk.
- Sky-Futures Ltd.
- MISTRAS Group
- SkySpecs
- Cyberhawk
Bibliography
- Bureau of Safety and Environmental Enforcement. (2026, April 1). BSEE ensures safe, responsible operations as offshore production reaches record levels.
- Bureau of Safety and Environmental Enforcement. (2025, November 18). American energy dominance: A new blueprint for offshore production.
- Department for Transport. (2026, July 29). Port freight annual statistics 2025: Cargo trends.
- RTE. (2026, March 3). Annual Electricity Review 2025.
- Bundesnetzagentur. (2026, January 8). Growth in renewable energy in 2025.
- Bundesnetzagentur. (2026, January 5). Bundesnetzagentur publishes 2025 electricity market data.
- European Commission. (2025, September 5). Authorisation for State aid pursuant to Articles 107 and 108 of the Treaty on the Functioning of the European Union—Cases where the Commission raises no objections—SA.115764 (C/2025/4924).
- Ministry of Economy, Trade and Industry. (2025, March 7). Cabinet Decision on the Bill for the Act for Partially Amending the Act on Promoting the Utilization of Sea Areas for the Development of Marine Renewable Energy Power Generation Facilities.
- Ministero delle Infrastrutture e dei Trasporti. (2025, July 4). Porti di Augusta e Taranto, firmato il decreto per lo sviluppo degli hub offshore.
- Sky-Futures. (2025, December 3). American Bureau of Shipping recertifies Sky-Futures for close visual inspections and non-destructive testing using UAS & robotics.
- SkySpecs. (2025, March 19). SkySpecs raises $20m to fuel global growth and innovation.
- Ondas Inc. (2026, June 18). Ondas to acquire Cyberhawk, expanding into critical infrastructure intelligence through software, data and AI.
- Ondas Inc. (2026, August 10). Ondas completes previously announced acquisition of Cyberhawk, a leader in AI-powered critical infrastructure intelligence.
- MISTRAS Group, Inc. (2026, March 11). Annual report for the fiscal year ended December 31, 2025 [Form 10-K].
This Report Answers
- The report explains where offshore drone inspection is used across product, application, end use and technology. It covers offshore energy, wind assets, port infrastructure and marine inspection routes.
- Segment analysis identifies the leading subsegments and the operational reasons asset owners prioritize them.
- Country analysis examines the listed markets and the infrastructure or policy mechanisms supporting inspection demand.
- Competitive analysis reviews active providers across offshore access, autonomous wind inspection, asset intelligence and engineering-grade reports.
What does the Offshore Drone Inspection Market cover?
The Offshore Drone Inspection Market covers services and systems used to inspect offshore platforms, wind turbines, port assets and marine vessels. It includes visual imaging, route planning, inspection reporting and data workflows used in offshore drone inspection assignments.
The assessment covers fixed wing, hybrid and rotary drones across filming, maintenance support, mapping and monitoring. Adjacent drone as a service models are included when the drone service is directly tied to offshore inspection output.
What is included in the scope?
The scope includes service revenue, inspection platforms, payload configuration, mission planning and report generation used for offshore assets. It also includes waterproof drone designs when they are used for marine inspection conditions.
It includes offshore inspection work for oil and gas rigs, offshore wind turbines, ports, ships and related marine structures where drone data supports asset condition review.
What is outside the scope?
The scope leaves out general aerial photography, parcel delivery, military surveillance and agricultural spraying when the activity is unrelated to offshore inspection output.
It also leaves out manual rope access, vessel repair, turbine replacement and subsea-only ROV services unless drone inspection data is part of the direct revenue activity.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report's scope and coverage?
Offshore Drone Inspection Market Breakdown By Product, Application, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Drone-based inspection services, platforms and data workflows used to inspect offshore platforms, wind assets, ports, ships and marine structures. |
| Product | Fixed Wing Drones; Hybrid Drones; Rotary Drones |
| Application | Filming and Photography; Inspection and Maintenance; Mapping and Surveying; Surveillance and Monitoring; Others |
| End Use | Oil and Gas Rigs; Offshore Wind Turbines; Ports and Ships; Others |
| Technology | Autonomous Navigation Systems; Computer Vision Technology; Communication Technology; Sensor Fusion Technology |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | USA; UK; South Korea; France; Germany; Japan; Italy |
| Key Companies Profiled | Sky-Futures Ltd.; MISTRAS Group; SkySpecs; Cyberhawk |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using offshore asset base, service revenue, inspection frequency, platform mix, country adoption and provider portfolio review. |
How is the market segmented?
-
By Product
- Fixed Wing Drones
- Long Endurance Drones
- Industrial Inspection Drones
- Hybrid Drones
- VTOL Hybrid Drones
- Multi-mission Hybrid Drones
- Rotary Drones
- Single Rotor Drones
- Multi Rotor Drones
- Fixed Wing Drones
-
By Application
- Filming and Photography
- Aerial Cinematography
- Offshore Documentation
- Inspection and Maintenance
- Structural Inspection
- Equipment Maintenance Support
- Mapping and Surveying
- Bathymetric Surveying
- Topographic Surveying
- Surveillance and Monitoring
- Security Surveillance
- Environmental Monitoring
- Others
- Emergency Response
- Logistics Support
- Filming and Photography
-
By End Use
- Oil and Gas Rigs
- Exploration Platforms
- Production Platforms
- Offshore Wind Turbines
- Foundation Inspection
- Blade Inspection
- Ports and Ships
- Port Infrastructure
- Marine Vessels
- Others
- Offshore Construction
- Marine Research Facilities
- Oil and Gas Rigs
-
By Technology
- Autonomous Navigation Systems
- AI Path Planning Systems
- GPS Assisted Navigation
- Computer Vision Technology
- Real Time Image Processing
- Object Detection Systems
- Communication Technology
- Satellite Communication Systems
- 5G Enabled Systems
- Sensor Fusion Technology
- LiDAR Based Systems
- Multispectral Sensors
- Autonomous Navigation Systems
-
By Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa

