- Market Value (2025): USD 1.6 Bn
- Estimated Value (2026): USD 1.7 Bn
- Forecast Value (2036): USD 3.3 Bn
- CAGR (2026-2036): 7.1%
What is the Silicone Polymer Processing Aids Market forecast to be worth by 2036?
USD 1.7 billion in 2026 to USD 3.3 billion by 2036 at a 7.1% CAGR.
- The Silicone Polymer Processing Aids Market was valued at USD 1.6 billion in 2025.
- Demand is projected to increase from USD 1.7 billion in 2026 to USD 3.3 billion by 2036.
- The market is forecast to record 7.1% CAGR from 2026 to 2036 as film firms and mixers place more value on stable line work and repeatable surface results.
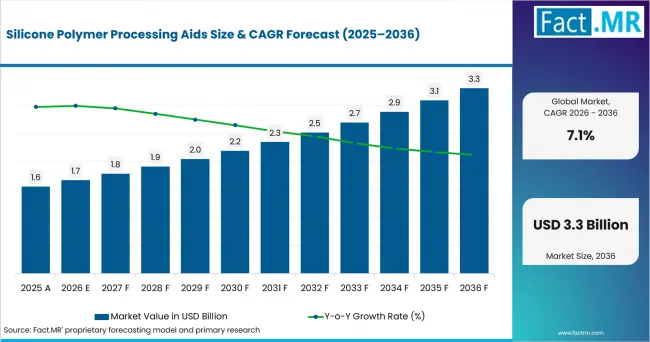
Silicone Polymer Processing Aids Value Analysis | Source: Fact.MR
What are the defining numbers behind Silicone Polymer Processing Aids Market growth?
An absolute opportunity of USD 1.6 billion is expected between 2026 and 2036.
- Demand Drivers in the Market
- Film firms need SPAs that reduce melt fracture while keeping output steady. The direct line link between smoother film and fewer die-related interruptions supports demand for the pellet mix in PE line work.
- Mixers need lower friction when filled blends raise pressure and motor load. The U.S. Bureau of Economic Analysis reported in June 2026 that expenditures for new foreign direct investment in U.S. plastics and rubber products manufacturing reached USD 19.0 billion in 2025.
- Wire and cable producers need better melt control in compounds with high mineral loading. SPA and siloxane aids can improve internal lubrication and support cleaner line work around the die.
- Engineering-resin plants need surface slip and mold release while keeping resin results stable. Silicone gum concentrates and specialty organosilicones can pair line support with surface change in one blend route.
- Key Segments Analyzed
- By Processing Aid Chemistry: Silicone masterbatch is expected to hold 34.0% share in 2026 because pelletized concentrates fit standard feeding systems and simplify low-dose dispersion.
- By Processing Function: Melt-fracture reduction is projected to account for 31.0% share in 2026 as film processors use additives to improve web appearance at commercially useful line speeds.
- By Polymer Substrate: Polyethylene is anticipated to capture 36.0% share in 2026 owing to its wide use in blown film, cable compounds and additive-masterbatch carrier systems.
- By Application: Blown film is estimated to represent 29.0% share in 2026 supported by the need to control melt fracture, die pressure and surface defects in continuous extrusion.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “An SPA earns repeat use when a firm can measure a cleaner surface or steadier line at the same resin mix. Plants are expected to compare pressure and final surface quality before approving a grade. Firms that pair resin-specific guidance with reliable dispersion and clear records have a better route from trial to regular use.”
- Strategic Implications
- Aid producers should show results by resin family. This helps plants compare pressure and surface change under the same line window.
- Masterbatch makers should match the carrier resin to the target base resin. Even spread makes plant trials easier to read and repeat.
- Film-focused firms should prepare for the Packaging and Packaging Waste Regulation. The European Commission said in August 2026 that the rules began applying on 12 August 2026 and included PFAS limits for food-contact packaging.
China is forecast to record 8.6% CAGR through 2036 backed by its large plastics base. Japan is anticipated to post 7.5% as tight process control shapes grade choice. The USA is projected at 7.1% owing to its large resin plants. France is estimated at 7.1% as film and pack use stays broad. Germany is forecast at 6.9% backed by high-spec plastics and cable use.
How does the Silicone Polymer Processing Aids Market break down by segment?
Silicone masterbatch leads Processing Aid Chemistry at 34.0%; Polyethylene leads Polymer Substrate at 36.0%.
Which Processing Aid Chemistry dominates?
Silicone masterbatch is expected to hold 34.0% share in 2026.
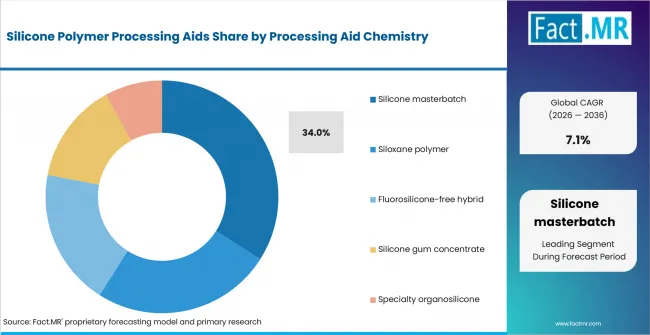
Silicone Polymer Processing Aids Analysis By Processing Aid Chemistry | Source: Fact.MR
Silicone masterbatch is expected to hold the main chemistry position because plants can meter pellets with standard resin-feed gear. The format gives a simple route for low-dose SPA feed. WACKER said in its October 2025 K 2025 material that silicone-based GENIOPLAST® additives and processing aids serve thermoplastics and engineering polymers. That product fit supports silicone masterbatch as a practical route for mixers. Related masterbatch formulations show the wider use of carrier-based aid feed. Additive masterbatch systems give a second nearby route for low-dose feed.
What leads the Processing Function segment?
Melt-fracture reduction is projected to account for 31.0% share in 2026.
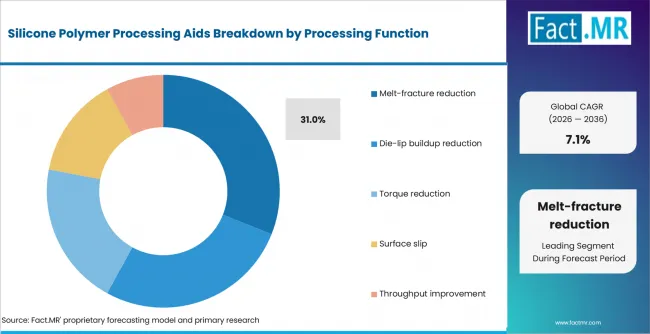
Silicone Polymer Processing Aids Analysis By Processing Function | Source: Fact.MR
Melt-fracture reduction is projected to lead because film defects are easy to see at the line. They can force a change in speed or die settings. An SPA gives operators a direct finish measure during a trial. Die-lip buildup reduction follows where long runs make deposits costly. Torque reduction matters in filled blends. Surface slip and throughput improvement widen use beyond film defects. Adjacent extrusion aids address many of the same line limits. Halogen-free extrusion aids give another nearby view of filled blends and cable use.
How does Polymer Substrate shape demand?
Polyethylene is anticipated to lead with 36.0% share in 2026.
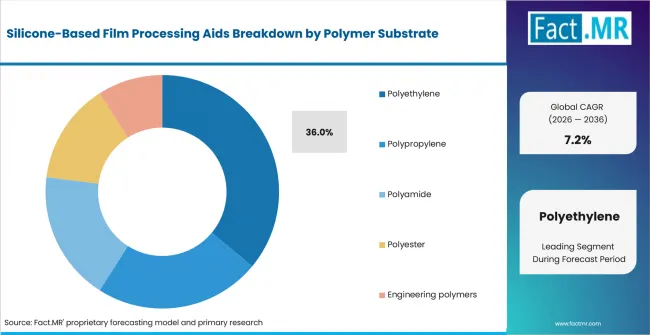
Silicone Based Film Processing Aids Analysis By Polymer Substrate | Source: Fact.MR
PE is anticipated to lead because it is used in blown film and cable blends. It also serves as a carrier resin for SPA pellets. PP follows in film and molded parts where flow and surface slip are useful. PA and polyester form a smaller technical pool that values heat-stable line support. Engineering polymers complete the segment for specialty siloxane grades. Related compatibilizer additives show how resin fit can shape blend results. Polymer reactive-extrusion additives give more context for in-line resin change.
What supports Blown Film within Application?
Blown film is estimated to represent 29.0% share in 2026.
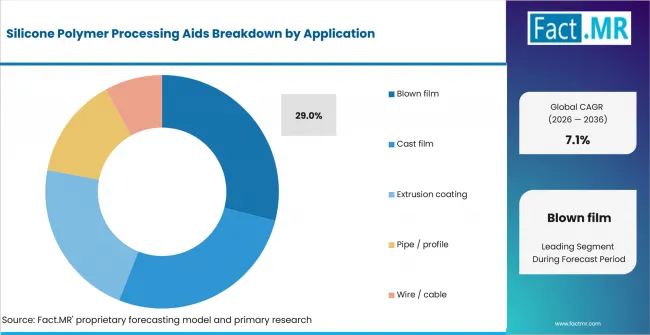
Silicone Polymer Processing Aids Analysis By Application | Source: Fact.MR
Blown film is estimated to lead because a steady run makes melt faults easy to see. Firms can track finish and pressure during a grade trial. Cast film follows where speed and slip still matter. Extrusion coating needs a stable melt curtain. Pipe and profile use values lower friction in filled blends. Wire and cable adds a route for torque control. The polyfilm market gives nearby context for film use.
What is accelerating Silicone Polymer Processing Aids Market adoption, and what is holding it back?
Extrusion efficiency drives adoption; formulation qualification restrains it.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Film extrusion defect control | +1.4% | Global | Short term (<= 2 years) |
| Throughput improvement in filled compounds | +1.1% | North America, East Asia | Medium term (2-4 years) |
| Fluoropolymer-free processing-aid transition | +0.9% | North America, Europe | Medium term (2-4 years) |
| Surface performance in engineering polymers | +0.7% | Europe, Japan | Long term (>= 4 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Silicone masterbatch for film conversion | +0.8% | Global | Short term (<= 2 years) |
| High-filled cable compounds | +0.6% | Europe, East Asia | Medium term (2-4 years) |
| Multi-function additives for technical plastics | +0.5% | Germany, Japan, USA | Long term (>= 4 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Resin-specific qualification requirements | -0.6% | Global | Short term (<= 2 years) |
| Surface migration and printability checks | -0.4% | Packaging applications | Medium term (2-4 years) |
| Cost sensitivity in commodity conversion | -0.3% | Global | Long term (>= 4 years) |
Which countries are scaling the Silicone Polymer Processing Aids Market through 2036?
- The country comparison spans 1.7 percentage points from China at 8.6% to Germany at 6.9% across the forecast period.
- China remains 1.1 percentage points above Japan as a broad plastics-use base supports aid use across film and mixing.
- Japan remains 0.4 percentage point above the USA as precision plastics line work supports demand for controlled melt flow.
- The USA matches France at 7.1% although the two markets differ in plant scale and packaging reach.
- France remains 0.2 percentage point above Germany as pack use and EU rules shape mix work.
- Germany closes the displayed range through high-spec plastics, cable compounds and pack uses that require repeatable line work results.
Similar CAGRs can still lead to different entry paths. Resin mix and line scale vary by country. Plant test rules vary too. Full report coverage includes North America and Latin America. It also covers Western Europe and Eastern Europe. East Asia and South Asia & Pacific are included with Middle East & Africa.
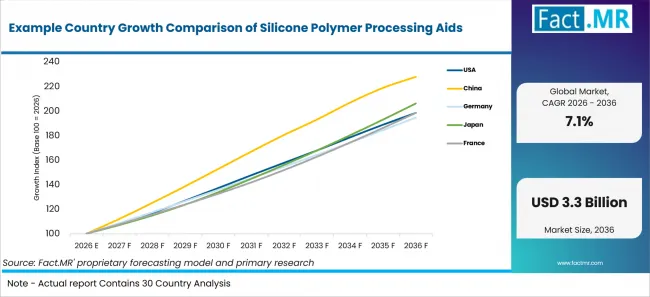
Example Country Growth Comparison Of Silicone Polymer Processing Aids | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| China | 8.6% |
| Japan | 7.5% |
| United States | 7.1% |
| France | 7.1% |
| Germany | 6.9% |
How is China scaling demand?
8.6% CAGR, supported by large plastics conversion and industrial processing activity.
China's large plant base gives aid firms access to film and compound output at scale. The National Bureau of Statistics of China reported in January 2026 that value added in the manufacture of rubber and plastic products increased 5.4% year on year in 2025 among industrial enterprises above designated size. That base supports trials where siloxane aids are judged on line pressure and surface finish. Firms still need resin-specific dose guides because line windows differ across film and filled-blend runs.
How does Japan perform?
7.5% CAGR, led by stable plastic-products output and precision processing requirements.
Japan's plants value repeat results where thin films and technical parts have tight surface needs. The Ministry of Economy, Trade and Industry reported in March 2026 that Japan’s 2025 production index for plastic products was 98.0, with 2020 equal to 100. Within plastic processing, SPA master pellets and siloxane processing aids can be evaluated for effects such as friction reduction and processing behavior within specific resin systems.
What supports USA adoption?
7.1% CAGR, backed by an established plastics manufacturing base and extrusion activity.
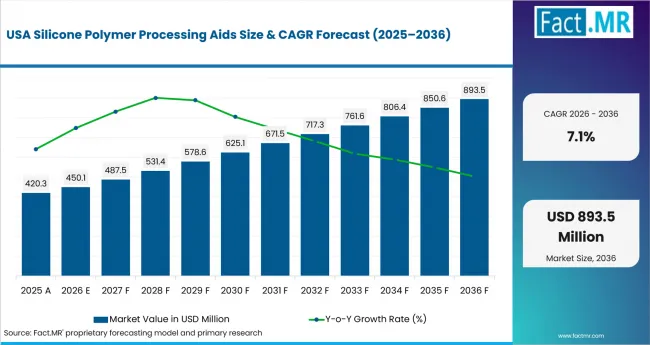
Silicone Polymer Processing Aids Country Value Analysis | Source: Fact.MR
U.S. film and blend makers test SPAs against output and die-cleaning time. The Federal Reserve said in January 2026 that capacity use for plastics and rubber products reached 73.2% in December 2025. That plant base gives SPAs a clear value test on existing lines. The PVC additives category gives nearby context for process and performance aids used in large plastics sectors.
What supports France demand?
7.1% CAGR, influenced by packaging conversion and EU formulation requirements.
France combines packaging use with rules that reward careful resin trials. INSEE said in November 2025 that the business-climate index for rubber and plastic products reached 96. The reading supports an active plant base where aid trials can focus on clear line gains. SPAs are useful for film and extrusion coating when firms need clean dies and stable surfaces. Plastic antioxidants give context for the wider aid set used in resin work.
What is supporting Germany’s adoption?
6.9% CAGR, shaped by technical plastics, cable compounds and packaging conversion.
Germany favors clear test data because technical plastics and cable blends often pass through set approval steps. SPAs can help lower friction and steady melt flow in these uses. Firms can improve grade choice with resin-specific data and clear dose guides. Halogen-free process aids give nearby context for cable and filled-blend line work.
Who leads the Silicone Polymer Processing Aids Market?
Dow has direct market coverage through DOWSIL™ polymer-processing aids for polyethylene and film applications. WACKER serves thermoplastics and engineering polymers through silicone-based GENIOPLAST® additives and processing aids. Shin-Etsu Chemical provides silicone master pellets for resin modification, with documented effects including lubricity, release performance, and surface-property modification. Evonik supplies organo-modified siloxane TEGO® PPA grades for film, fiber, and other extrusion processes.
In October 2025, Evonik stated that its K 2025 plastics portfolio included TEGO® PPA grades as alternatives to PFAS-based processing additives, with the company highlighting improved packaging quality. Momentive supplies PEarlene™ silicone masterbatches for polymer compounding and extrusion, while Chengdu Silike Technology provides silicone masterbatches and silicone-based processing additives for a range of thermoplastics.
Supplier differentiation is expected to reflect resin compatibility, effective dosage, die-pressure control, extrusion stability, and repeatable surface quality. Application trials are important because additive concentration and polymer formulation can influence processing and finished-part performance. The halogen-free process aids market provides adjacent context for processing-aid selection in filled compounds, polyolefin films, and wire-and-cable applications.
Which companies are the key providers?
Companies profiled include Dow; Wacker Chemie; Shin-Etsu Chemical; Momentive; Evonik; and Chengdu Silike Technology.
- Dow
- Wacker Chemie
- Shin-Etsu Chemical
- Momentive
- Evonik
- Chengdu Silike Technology
Bibliography
- U.S. Bureau of Economic Analysis. (2026, June 10). New foreign direct investment in the United States, 2025.
- Board of Governors of the Federal Reserve System. (2026, January 16). Industrial production and capacity utilization—G.17: Table 7. Capacity utilization.
- National Bureau of Statistics of China. (2026, January 20). Industrial production operation in December 2025.
- Ministry of Economy, Trade and Industry. (2026, April 30). Indices of industrial production: Preliminary report for March 2026.
- Institut national de la statistique et des études économiques. (2025, November 21). In November 2025, the business climate in manufacturing industry has fallen back.
- Evonik. (2025, October 1). Evonik to showcase latest innovations and sustainability initiatives in polymer chemistry at K 2025.
- Directorate-General for Environment. (2026, August 11). New EU packaging rules start to apply, including restrictions on PFAS in food-contact packaging. European Commission.
- Dow. (2025, September 23). Dow unveils an alternative to fluoropolymer-based polymer processing aids for film packaging.
Wacker Chemie AG. (2025, October 8). K 2025 plastics & rubber trade fair: WACKER showcases high-tech silicones for future-bound technologies [Press release].
This Report Answers
- The report explains where SPAs are used across chemistry and function. It also covers resin base and end use. The review focuses on line problems that plants can measure during a run.
- Segment review identifies the 2026 share leaders. It explains why silicone masterbatch and melt-fracture reduction lead their supplied groups. PE and blown film form the main resin and use route.
- Country review compares the five listed markets. It links their growth rates with plastics use and plant needs.
- Competitive review covers the supplied firm set. Company-share views stay outside the report. The review focuses on verified SPA or nearby resin-aid work.
- Use review looks at melt pressure and surface finish during grade tests. It also covers die cleanliness and torque across film or cable runs.
What does the Silicone Polymer Processing Aids Market cover?
The SPA market covers silicone and siloxane aids used during thermoplastic runs. These aids can improve melt flow and surface control. They can cut melt fracture or die buildup. Some grades lower torque or help raise output.
The scope covers aids sold for direct feed or in a carrier resin. The market stays focused on silicone or siloxane chemistry with a clear process role.
What is included in the scope?
The scope includes silicone masterbatch and siloxane polymer grades. It also includes silicone gum concentrates and specialty organosilicones. Covered base resins include PE and PP. PA and polyester are included with engineering polymers.
Use coverage includes blown film and cast film. Extrusion coating is included with pipe or profile. Wire and cable is covered where silicone aids serve a process role.
What is excluded from the scope?
The scope excludes bulk silicone elastomers sold as the finished resin. External mold-release coatings stay outside the market when they are added after resin conversion. Color or stabilizer aids stay outside the scope when they lack a silicone process role.
Process machines and dose gear stay outside the market boundary. Finished plastic goods are treated as end uses instead of aid sales.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report’s scope and coverage?
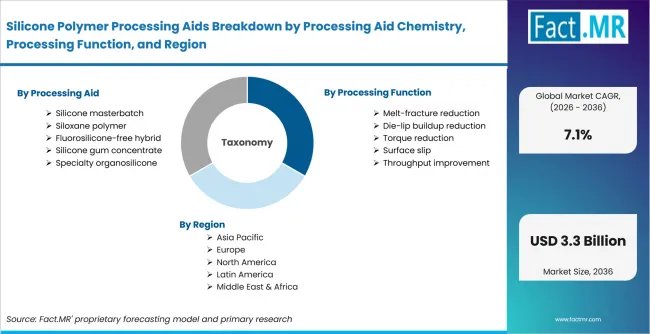
Silicone Polymer Processing Aids Breakdown By Processing Aid Chemistry, Processing Function, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Silicone and siloxane polymer processing aids added to thermoplastic formulations to improve melt flow, reduce melt fracture, lower torque, limit die buildup, modify slip or improve throughput during conversion. |
| Processing Aid Chemistry | Silicone masterbatch; Siloxane polymer; Fluorosilicone-free hybrid; Silicone gum concentrate; Specialty organosilicone |
| Processing Function | Melt-fracture reduction; Die-lip buildup reduction; Torque reduction; Surface slip; Throughput improvement |
| Polymer Substrate | Polyethylene; Polypropylene; Polyamide; Polyester; Engineering polymers |
| Application | Blown film; Cast film; Extrusion coating; Pipe / profile; Wire / cable |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | United States; China; Germany; Japan; France |
| Key Companies Profiled | Dow; Wacker Chemie; Shin-Etsu Chemical; Momentive; Evonik; Chengdu Silike Technology |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up approach using polymer conversion activity; application mix; segment shares; country growth; provider portfolio review; and technical validation. |
How is the market segmented?
-
By Processing Aid Chemistry:
- Silicone masterbatch
- Siloxane polymer
- Fluorosilicone-free hybrid
- Silicone gum concentrate
- Specialty organosilicone
-
By Processing Function:
- Melt-fracture reduction
- Die-lip buildup reduction
- Torque reduction
- Surface slip
- Throughput gain
-
By Polymer Substrate:
- Polyethylene
- Polypropylene
- Polyamide
- Polyester
- Engineering polymers
-
By Application:
- Blown film
- Cast film
- Extrusion coating
- Pipe / profile
- Wire / cable
-
By Region:
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa

