- Market Value (2025): USD 2.4 Bn
- Estimated Value (2026): USD 2.7 Bn
- Forecast Value (2036): USD 8.3 Bn
- CAGR (2026-2036): 12.0%
What is the ESD Protective Coating Additives Market forecast to be worth by 2036?
USD 2.7 Billion in 2026 to USD 8.3 Billion by 2036 at a 12.0% CAGR.
- The ESD Protective Coating Additives Market reached USD 2.4 Billion in 2025.
- Demand is projected to rise from USD 2.7 Billion in 2026 to USD 8.3 Billion by 2036.
- The market is forecast to record a 12.0% CAGR from 2026 to 2036 as chip fabs and battery plants add more ESD-controlled work areas.
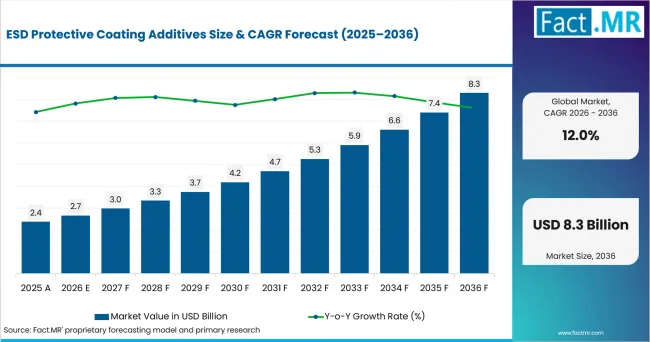
Esd Protective Coating Additives Value Analysis | Source: Fact.MR
What are the defining numbers behind ESD Protective Coating Additives Market growth?
An absolute opportunity of USD 5.6 Billion is expected between 2026 and 2036.
- Demand Drivers in the Market
- Chip-fab teams need a stable ohm range around wafer work and package lines. A stray charge can harm chips and stop a controlled process.
- Battery plants need ESD-safe floors around cell work and service zones. Cell expansion adds more areas where charge control becomes part of daily plant use.
- Data center teams need hard-wearing floors near dense racks and service zones. The International Energy Agency reported in April 2025 that data centers consumed about 415 TWh of electricity in 2024.
- Coating makers need inputs that mix well in epoxy and polyurethane. Stable mixing helps the cured film stay inside its target ohm range.
- Key Segments Analyzed
- By Conductive Additive: Carbon black is expected to hold 34.0% share in 2026 because it offers proven ESD grades and broad use in coating mixes.
- By Conductivity Target: Antistatic is projected to account for 31.0% share in 2026 where sites need charge control without shielding-level current flow.
- By End-use Facility: Semiconductor fabs are anticipated to capture 36.0% share in 2026 as wafer work and chip packaging need strict ESD control.
- By Coating System: Epoxy is estimated to represent 29.0% share in 2026 due to its common use in hard-wearing plant floors with an ESD function.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “The core test is a stable ohm range after the input is mixed into the coating. Demand is expected to favor mixes that keep that range after cure and wear. Firms gain more value when raw-input data is linked to cured-film tests.”
- Strategic Implications
- Input makers should show ohm ranges at real coating loadings. The data should cover the resin types used in plant floors and other ESD surfaces.
- Coating makers should test the cured film after wear. This gives site teams a clearer basis for sign-off than raw-input data alone.
- Site teams should set an ohm range for each protected zone. Antistatic and static-dissipative floors should be matched to the risk at that point.
- Supplier review should include recent field proof. Orion S.A. reported in November 2025 that its PRINTEX® kappa 100 grade of acetylene black had been qualified by a battery energy storage system producer.
China is projected to record 13.1% CAGR through 2036 as chip and battery output expands. Japan is anticipated to post 12.0% as chip investment rises. The United States and France are forecast at 11.6%, while Germany is expected to record 11.4% over the same period.
How does the ESD Protective Coating Additives Market break down by segment?
Carbon black leads Conductive Additive at 34.0%; semiconductor fabs lead End-use Facility at 36.0%.
Which Conductive Additive dominates?
Carbon black is expected to hold 34.0% share in 2026.
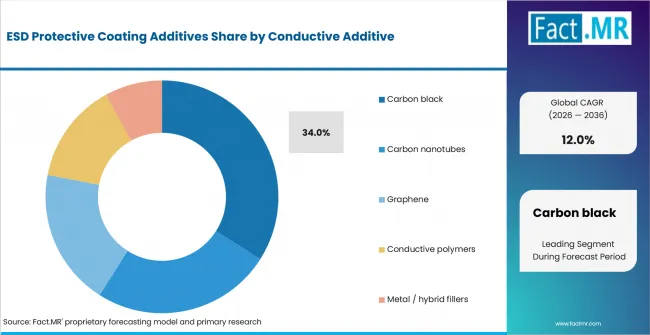
Esd Protective Coating Additives Analysis By Conductive Additive | Source: Fact.MR
Carbon black is expected to lead because it offers a proven path to antistatic and static-dissipative results. Carbon nanotubes serve mixes that need lower loading. Graphene can form thin charge paths in some films. Conductive polymers and metal or hybrid fillers serve narrower needs. Cabot lists conductive carbon black for water-based and solvent-based electrostatic primers, which supports its use in coating systems that need controlled current flow.
What leads the Conductivity Target segment?
Antistatic is projected to account for 31.0% share in 2026.
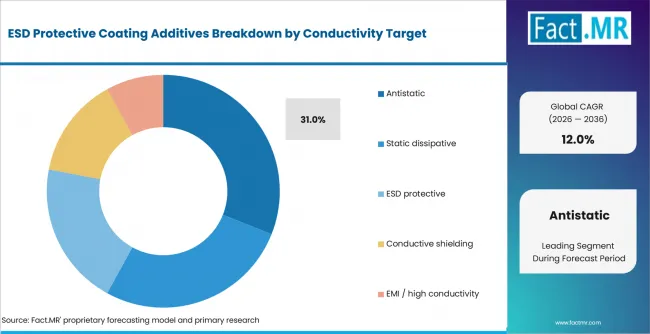
Esd Protective Coating Additives Analysis By Conductivity Target | Source: Fact.MR
Antistatic coatings are projected to lead where a site needs basic charge control across routine work zones. Static-dissipative systems serve tighter ohm bands near chip handling. ESD protective coatings address zones with formal ESD rules. Conductive shielding and EMI systems serve a smaller set of jobs. The cured coating must meet the set ohm band, so raw-input conductivity alone is a weak basis for final sign-off.
How does End-use Facility shape demand?
Semiconductor fabs are anticipated to capture 36.0% share in 2026.
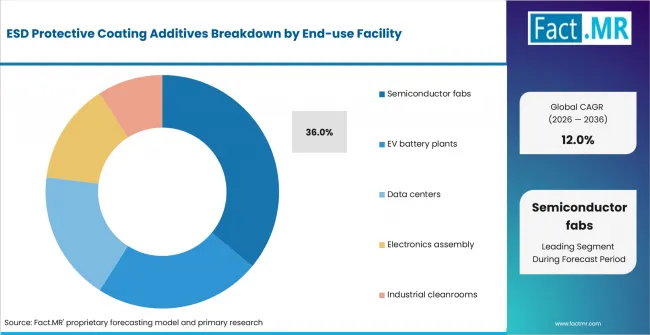
Esd Protective Coating Additives Analysis By End Use Facility | Source: Fact.MR
Chip fabs are anticipated to lead because wafer work and advanced package lines place high-value chips in tightly managed rooms. Battery plants need charge control in selected work zones. Data centers add use near racks and service areas. Electronics assembly and cleanrooms add more demand. The U.S. Department of Commerce reported in June 2025 that Micron planned USD 200 billion in U.S. semiconductor manufacturing and R&D investment.
What supports Epoxy within Coating System?
Epoxy is estimated to represent 29.0% share in 2026.
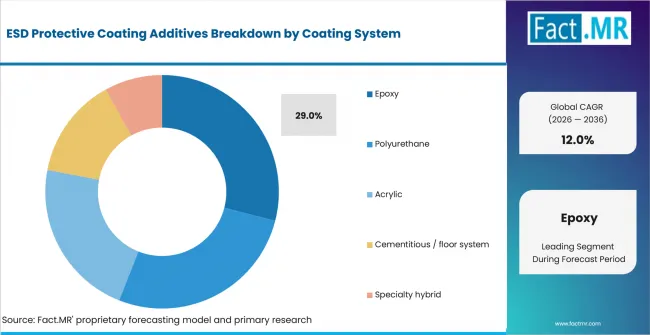
Esd Protective Coating Additives Analysis By Coating System | Source: Fact.MR
Epoxy is estimated to lead because plant floors need a hard film that can hold an ESD filler and still bond well to the base. Polyurethane is used where flex or wear response changes the choice. Acrylic suits some quick-service jobs. Cementitious floors fit mineral bases, while hybrid systems serve special site needs. Final sign-off still depends on the cured film because the resin can change mixing and the measured ohm range.
What is accelerating ESD Protective Coating Additives Market adoption, and what is holding it back?
Electronics-site expansion drives adoption; ohm-range drift restrains wider use.
Drivers Impact Analysis
| DRIVER | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Chip-fab investment | +2.1% | USA, China, Japan, Europe | Medium term (2-4 years) |
| Battery and storage buildout | +1.6% | USA, China, Europe, Japan | Medium term (2-4 years) |
| Data center ESD needs | +1.1% | USA, Europe, East Asia | Long term (>= 4 years) |
| New ESD input formats | +0.8% | Global | Short term (<= 2 years) |
Opportunity Impact Analysis
| OPPORTUNITY | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Low-loading CNT and graphene systems | +1.2% | Global | Medium term (2-4 years) |
| ESD floors for chip and battery sites | +1.0% | USA, East Asia, Europe | Short term (<= 2 years) |
| Waterborne ESD coating systems | +0.7% | North America, Europe | Long term (>= 4 years) |
Restraints Impact Analysis
| RESTRAINT | (~) % IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Ohm drift after cure or wear | -0.8% | Global | Short term (<= 2 years) |
| Mixing limits at plant scale | -0.6% | Global | Medium term (2-4 years) |
| Higher cost of CNT and graphene systems | -0.5% | Global | Medium term (2-4 years) |
Which countries are scaling ESD Protective Coating Additives Market through 2036?
- The displayed country range spans 1.7 percentage points from China at 13.1% to Germany at 11.4%.
- China remains above Japan as chip and battery output adds more ESD-sensitive work sites.
- Japan follows at 12.0% as new chip capacity supports controlled work areas.
- The United States and France each record 11.6%, though their project mix differs by chip, battery, and data-center work.
- Germany records 11.4% as chip and factory automation keep ESD control relevant in plant areas.
Similar CAGRs can lead to different entry paths because each country has its own site mix and sign-off rules. Full coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, and Middle East & Africa.
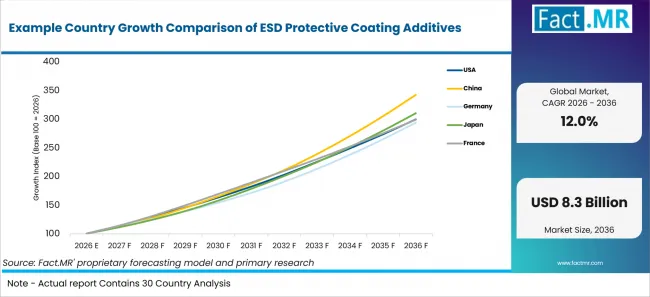
Example Country Growth Comparison Of Esd Protective Coating Additives | Source: Fact.MR
| Country | CAGR (2026-2036) |
|---|---|
| China | 13.1% |
| Japan | 12.0% |
| United States | 11.6% |
| France | 11.6% |
| Germany | 11.4% |
What supports China adoption?
13.1% CAGR, driven by chip and battery output.
China has a large chip base and a fast-growing EV supply chain. Both add sites where ESD control forms part of process design. The National Bureau of Statistics reported in February 2026 that new-energy vehicle output reached 16.524 million units in 2025. Coating firms are expected to compete on a stable ohm range and simple mixing across large plant floors.
How does Japan perform?
12.0% CAGR, shaped by new chip investment.
Japan is adding funds to build more chip capacity at home. These fabs need strict control in rooms that handle wafers and advanced packages. The Ministry of Economy, Trade and Industry reported in February 2026 that government and private companies had invested 267.6 billion yen in Rapidus. ESD coating firms are expected to gain when their cured-film tests fit strict site rules.
What supports United States adoption?
11.6% CAGR, backed by battery storage and chip-site expansion.
The United States is adding grid storage and chip capacity in several states. These projects create more sites with high-value electrical gear. The U.S. Energy Information Administration reported in February 2026 that a record 15 GW of utility-scale battery storage was added in 2025. ESD input demand is expected to center on large floors that keep a stable ohm band during heavy use.
How is France developing demand?
11.6% CAGR, supported by chip output and data-center activity.
France has chip plants and a growing base of data-heavy sites. Both can add ESD needs in work rooms and service zones. INSEE reported in July 2026 that output in the manufacture of computer, electronic and optical products was 6.1% higher during March–May 2026 than in the same three-month period of 2025. Coating firms are expected to focus on hard films and a stable ohm range for chip-related plant areas.
What supports Germany adoption?
11.4% CAGR, led by electronics orders and factory automation.
Germany has a deep factory base with a high use of chips and automated tools. This keeps ESD control relevant near high-value parts and test gear. Destatis reported in August 2026 that new orders for computer, electronic, and optical products rose 22.7% month on month in June 2026. Input firms are expected to gain when their products fit common epoxy and polyurethane work flows.
Who leads the ESD Protective Coating Additives Market?
Cabot Corporation supplies conductive carbon blacks for conductive and electrostatic coating applications. Orion S.A. offers specialty carbon black grades for conductive coatings and energy-storage applications. OCSiAl supplies TUBALL™ graphene nanotube dispersions for antistatic paints, ESD protective coatings, and conductive flooring systems. Evonik supplies ADDID® 230, a solvent-free antistatic additive designed to increase the conductivity of coating formulations, including ESD floor coatings.
Birla Carbon offers Conductex® conductive carbon blacks for ESD applications, including antistatic flooring. NanoXplore supplies graphene-based materials for electrically conductive, static-dissipative, and advanced coating applications. The competitive field therefore spans conductive carbon black, graphene nanotubes, graphene, and specialty antistatic additives.
Supplier selection is expected to depend on the target resistance range that can be achieved at a practical additive loading, along with dispersion quality, resin compatibility, and processing conditions. Carbon black suppliers offer established conductive-additive portfolios across coatings and related applications, while graphene nanotube and graphene suppliers emphasize conductivity at relatively low addition levels and greater formulation flexibility. Cured-film resistivity data under application-specific conditions are expected to remain important because electrical performance can vary with additive concentration, dispersion, resin system, and processing conditions.
Which companies are the key providers?
Key companies include Cabot Corporation; Orion S.A.; OCSiAl; Evonik Industries AG; Birla Carbon; and NanoXplore Inc.
- Cabot Corporation
- Orion S.A.
- OCSiAl
- Evonik Industries AG
- Birla Carbon
- NanoXplore Inc.
Bibliography
- International Energy Agency. (2025, April 10). Energy and AI.
- Orion S.A. (2025, November 19). Orion S.A. gains commercial traction with conductive additives vital for grid modernization.
- U.S. Department of Commerce. (2025, June 12). President Trump secures $200B investment from Micron Technology for memory chip manufacturing in the United States.
- National Bureau of Statistics of China. (2026, February 28). Statistical communiqué of the People’s Republic of China on the 2025 national economic and social development.
- Ministry of Economy, Trade and Industry. (2026, February 27). Press conference by Minister Akazawa (excerpt).
- U.S. Energy Information Administration. (2026, February 20). New U.S. electric generating capacity expected to reach a record high in 2026.
- Institut national de la statistique et des études économiques. (2026, July 3). In May 2026, manufacturing output fell back by 1.0%.
- Federal Statistical Office (Destatis). (2026, August 6). New orders in manufacturing in June 2026: +3.1% on the previous month.
- Cabot Corporation. (2025, July 29). Cabot Corporation launches new LITX® 95F conductive carbon engineered for energy storage systems.
- Evonik Industries AG. (2025, December). Electrostatic discharge performance with ADDID® 230 for floor coating applications [Fact sheet].
- Birla Carbon. (2026, June 1). Conductive & ESD.
- NanoXplore Inc. (2026, May 5). NanoXplore launches xGnP™ D500-HP, high-purity graphene to replace conventional conductive additives.
This Report Addresses
- The report explains how ESD inputs are used in protective coatings and how the target ohm band shapes input choice.
- Segment analysis reviews how coating chemistry and site type affect loading, mixing, current flow, and cured-film tests.
- Country analysis compares five markets with one distinct recent government statistic for each country.
- Competitive analysis reviews firms with current carbon black, CNT, graphene, or antistatic products that fit the report boundary.
What does the ESD Protective Coating Additives Market cover?
The market covers functional inputs added to protective coatings to control current flow in high-value plant areas. Its core material base includes conductive carbon black and CNT or graphene systems used when lower loading or color retention is needed. The focus stays on the input used in the coating and on the ohm range reached after cure.
Coverage spans antistatic, static-dissipative, ESD-protective, shielding, and high-conductivity uses. Related mix context includes specialty carbon black where conductive grades overlap with coatings and chip uses. Site construction and general electronic gear sit outside the revenue boundary.
What is included in the scope?
The scope includes inputs used in epoxy, polyurethane, acrylic, cementitious floor, and hybrid coatings for chip fabs, battery plants, data centers, assembly lines, and cleanrooms. It includes dispersions when current control is the stated coating function. Related EMI shielding materials are used only where shielding and ESD control overlap in coating design.
The material set includes carbon black, carbon nanotubes, graphene, conductive polymers, and metal or hybrid fillers. Loading and mixing are part of the supplier test. thermal graphene coatings give useful adjacent context for graphene use in functional coating films.
What is excluded from the scope?
Standalone conductive plastics and non-coating ESD gear are outside the revenue boundary.
Outside scope are molded conductive plastics, conductive adhesives sold as separate bonding products, grounding hardware, ESD clothing, wrist straps, ionizers, and monitoring gear. Finished floor coatings are used only as downstream proof of input use. Their full system revenue stays outside the additive market boundary.
General pigments and flow aids are outside scope when they carry no defined electrical role. Semiconductor wafers and electronic parts are outside the revenue line. Battery electrode inputs are treated separately because this report measures conductive inputs used in protective coatings.
How Was the Analysis Built?
The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
- Primary Research: Primary research includes discussions with manufacturers, service providers, technology developers, distributors, end users, and subject-matter experts. These conversations examine purchasing priorities, product adoption, operational challenges, approval requirements, competitive positioning, and the factors that influence wider market acceptance.
- Desk Research: Desk research covers government statistics, regulatory publications, company filings, trade data, technical studies, industry associations, standards, public policy, and other authoritative sources. Every source used in the analysis is documented in the bibliography.
- Market Sizing and Forecasting: Market estimates combine historical performance, demand indicators, pricing and volume trends, segment shares, company participation, country-level growth, adoption patterns, investment activity, and barriers to market expansion.
- Data Validation and Update Cycle: Findings are validated by comparing primary interviews with public data, company activity, regulatory changes, trade patterns, and industry developments. Regular updates review new product launches, capacity changes, partnerships, approvals, and shifts in commercial adoption.
What is the report’s scope and coverage?
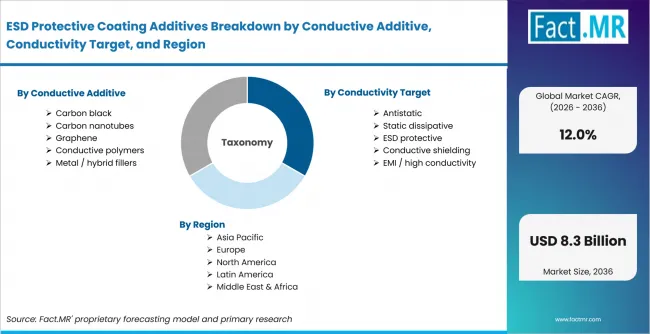
Esd Protective Coating Additives Breakdown By Conductive Additive, Conductivity Target, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD Billion |
| Market Definition | Functional additives used in protective coatings to provide antistatic, static-dissipative, ESD-protective, conductive-shielding, or high-conductivity performance. |
| Conductive Additive | Carbon black; Carbon nanotubes; Graphene; Conductive polymers; Metal / hybrid fillers |
| Conductivity Target | Antistatic; Static dissipative; ESD protective; Conductive shielding; EMI / high conductivity |
| End-use Facility | Semiconductor fabs; EV battery plants; Data centers; Electronics assembly; Industrial cleanrooms |
| Coating System | Epoxy; Polyurethane; Acrylic; Cementitious / floor system; Specialty hybrid |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Profiled | United States; China; Germany; Japan; France |
| Key Companies Profiled | Cabot Corporation; Orion S.A.; OCSiAl; Evonik Industries AG; Birla Carbon; NanoXplore Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up review using site growth, coating use, ohm targets, country trends, and verified provider portfolios. |
How is the market segmented?
-
By Conductive Additive:
- Carbon black
- Carbon nanotubes
- Graphene
- Conductive polymers
- Metal / hybrid fillers
-
By Conductivity Target:
- Antistatic
- Static dissipative
- ESD protective
- Conductive shielding
- EMI / high conductivity
-
By End-use Facility:
- Semiconductor fabs
- EV battery plants
- Data centers
- Electronics assembly
- Industrial cleanrooms
-
By Coating System:
- Epoxy
- Polyurethane
- Acrylic
- Cementitious / floor system
- Specialty hybrid
-
By Region:
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa

