- Market Value (2025): USD 2.4 Bn
- Estimated Value (2026): USD 2.7 Bn
- Forecast Value (2036): USD 9.8 Bn
- CAGR (2026-2036): 13.8%
What is the Decentralized Methanol Plants Market forecast to be worth by 2036?
USD 9.8 billion by 2036 at a 13.8% CAGR.
- The Decentralized Methanol Plants Market was approximately USD 2.4 billion in 2025.
- Demand is projected to increase from USD 2.7 billion in 2026 to USD 9.8 billion by 2036.
- The market is forecast to expand at a 13.8% CAGR from 2026 to 2036.
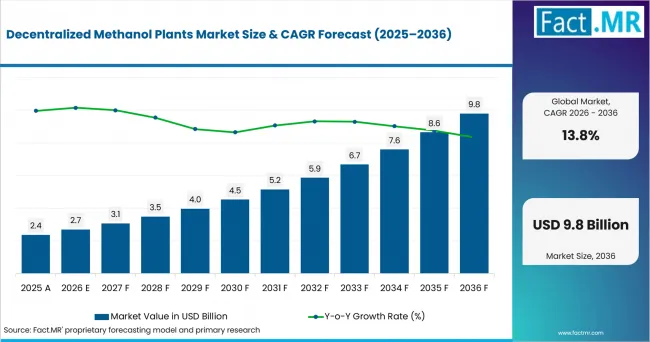
Decentralized Methanol Plants Market Value Analysis | Source: Fact.MR
What are the defining numbers behind Decentralized Methanol Plants Market growth?
An absolute opportunity of USD 7.1 billion is expected between 2026 and 2036.
- Demand Drivers in the Market
- Methanol-capable shipping is creating a new fuel outlet that can support production closer to ports and industrial demand centres. The International Energy Agency reported that more than 60 methanol-powered vessels were operating by June 2025 and nearly 300 additional vessels were on order. As vessel deployment expands, fuel buyers require dependable methanol supply, which can improve the economics of regional production projects.
- Captured carbon dioxide and low-emissions hydrogen are opening a second feedstock route alongside conventional natural gas. The U.S. Department of Energy includes e-methanol as a proposed marine-fuel use within the Gulf Coast Hydrogen Hub, linking clean hydrogen production with industrial carbon sources. This creates opportunities for plants located near refineries, chemical sites, biogenic carbon sources or renewable-power hubs.
- Remote and underused gas resources can be monetized without first building a large centralized methanol complex. Modular Plant Solutions states that its small-scale methanol design can use pipeline, stranded or flared natural gas as well as renewable natural gas and syngas. Locating conversion equipment closer to the feedstock can reduce the need to transport low-value gas before conversion into a liquid product.
- Chemical manufacturing provides an established local demand base in addition to fuel markets. UK public-health guidance identifies formaldehyde and acetic acid among chemicals produced from methanol. Decentralized plants can therefore serve chemical clusters where a stable offtaker values regional supply and reduced dependence on imported methanol.
- Modular construction and remote operation are reducing some execution barriers associated with smaller projects. Container-compatible modules can be fabricated away from the project site, transported by established logistics routes and assembled near the feedstock or customer. This model is relevant to remote industrial users that need methanol supply but cannot justify a conventional centralized complex.
- Key Segments Analyzed
- Natural Gas Based Methanol Plants account for 74.6% of Product in 2026. Their lead reflects the widespread availability of natural gas as a feedstock for syngas generation, including supplies from pipelines, associated gas fields and stranded-gas locations.
- Fuel Production Applications account for 41.8% of Application in 2026. Demand is increasing as methanol gains use as a marine fuel, encouraging supply projects near ports and major transport routes.
- Chemical Manufacturing Companies account for 67.9% of End Use in 2026. These buyers consume methanol directly in the production of formaldehyde, acetic acid and other chemical intermediates.
- Syngas Conversion Technology accounts for 58.3% of Technology in 2026. The process remains central to methanol production because hydrogen and carbon-oxide-rich synthesis gas can be converted catalytically at commercial scale.
- Containerized Plant Configurations account for 36.5% of Formulation in 2026. Modular designs are suited to projects where on-site construction needs to be limited or where feedstock and end users are located away from conventional industrial hubs.
- Direct Project Sales account for 72.4% of Distribution Channel in 2026. Methanol plants are typically engineered around site-specific reforming, synthesis, utility and control requirements, making direct coordination between the buyer and project supplier necessary.
- Analyst Opinion at Fact.MR
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states, “Decentralized methanol projects become more attractive when the plant is designed around a specific feedstock and a committed local offtaker. Natural gas remains the dominant route because its reforming and synthesis chain is mature, while new projects increasingly evaluate renewable hydrogen, captured carbon dioxide and biomass. Suppliers that can combine modular execution with reliable process performance and remote operating support are positioned to address sites that cannot justify conventional centralized production.”
- Strategic Implications
- Plant suppliers should qualify projects around feedstock availability and offtake before optimizing capacity, because decentralized economics depend on site-specific gas, biomass, carbon dioxide or power conditions.
- Technology providers can strengthen project bankability by offering pre-engineered modules with clear utility requirements and defined interfaces for hydrogen, carbon capture and product storage.
- Developers targeting marine fuel should locate production with access to ports, storage and bunkering systems so methanol does not incur unnecessary inland handling before delivery to vessels.
- Service models should include remote monitoring and performance support because unmanned or lightly staffed sites require rapid diagnosis when reforming, compression or synthesis conditions drift from design targets.
How does the Decentralized Methanol Plants Market break down by segment?
The market is segmented by Product, Application, End Use, Technology, Formulation and Distribution Channel.
Why do Natural Gas Based Methanol Plants lead Product?
Natural Gas Based Methanol Plants are projected to account for a 74.6% share in 2026.
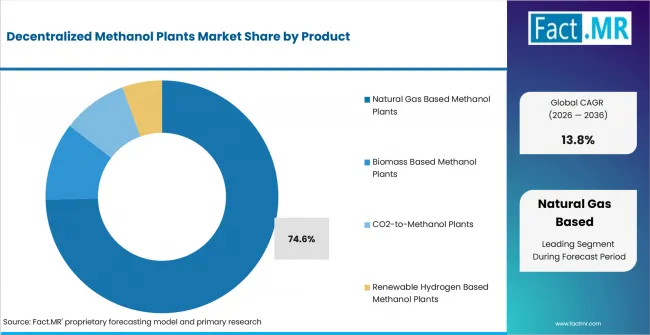
Decentralized Methanol Plants Market Analysis By Product | Source: Fact.MR
Natural gas leads because reforming and methanol synthesis are established industrial processes with well-defined equipment requirements. Decentralized projects can also use gas that is available locally but difficult to move economically, including associated or stranded resources.
Current modular designs reinforce this use case. Modular Plant Solutions markets a small-scale plant that can process pipeline, stranded or flared natural gas and operate as a stand-alone facility. For buyers, the commercial advantage is the ability to convert a gaseous feedstock into a storable liquid close to the source rather than waiting for new pipeline infrastructure.
Why do Fuel Production Applications lead Application?
Fuel Production Applications are projected to account for a 41.8% share in 2026.
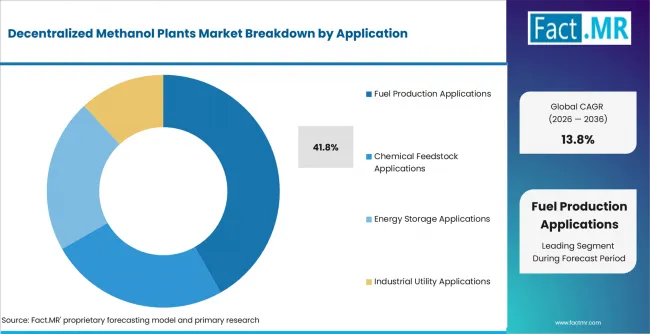
Decentralized Methanol Plants Market Analysis By Application | Source: Fact.MR
Fuel applications lead because methanol can be stored as a liquid at ambient conditions and can be handled through established chemical logistics. This is useful for maritime operators seeking a liquid alternative to conventional marine fuels without cryogenic storage.
The IEA reported more than 60 methanol-powered vessels in operation and nearly 300 additional vessels on order as of June 2025. The UK Maritime and Coastguard Agency also maintains a dedicated regulatory process for vessels using methanol as fuel. These developments create identifiable offtake that can support regional plant investment near ports and shipping routes.
Why do Chemical Manufacturing Companies lead End Use?
Chemical Manufacturing Companies are projected to account for a 67.9% share in 2026.
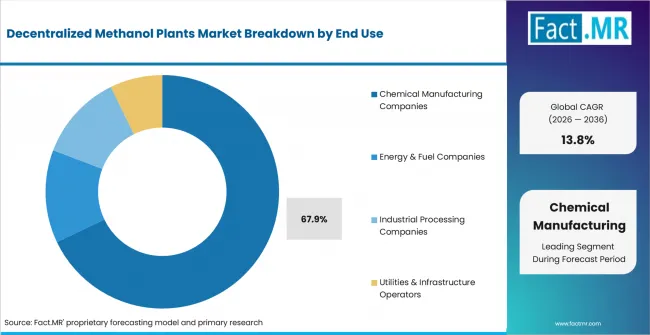
Decentralized Methanol Plants Market Analysis By End Use | Source: Fact.MR
Chemical manufacturers lead because methanol is already embedded in established production chains. It is used to make formaldehyde and acetic acid, giving chemical sites recurring feedstock demand that does not depend entirely on the pace of alternative-fuel adoption.
A decentralized plant can be placed near the consuming site when local gas, biomass-derived syngas or carbon dioxide and hydrogen are available. This reduces exposure to long-distance methanol logistics and gives the buyer greater control over feedstock specification and supply continuity.
Why does Syngas Conversion Technology lead Technology?
Syngas Conversion Technology is projected to account for a 58.3% share in 2026.
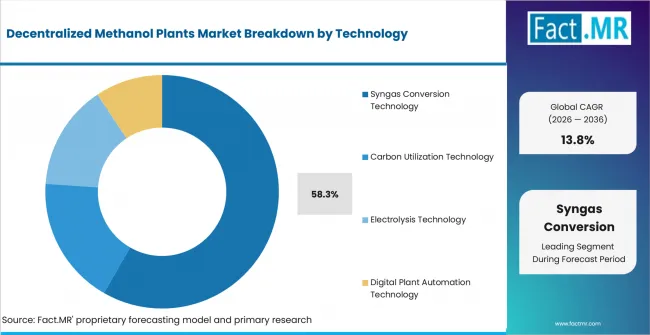
Decentralized Methanol Plants Market Analysis By Technology | Source: Fact.MR
Syngas conversion leads because methanol synthesis requires a controlled mixture of hydrogen and carbon oxides before catalytic conversion. Natural gas reforming, biomass gasification and several carbon-utilization routes can all be arranged to provide this synthesis-gas feed.
The technology is also supported by a broad engineering base. Linde Engineering describes integrated syngas installations that extend through gas conditioning and methanol synthesis, while thyssenkrupp Uhde offers methanol plant designs across a wide capacity range. Buyers therefore have access to proven process blocks that can be adapted to smaller site-specific projects.
Why do Containerized Plant Configurations lead Formulation?
Containerized Plant Configurations are projected to account for a 36.5% share in 2026.
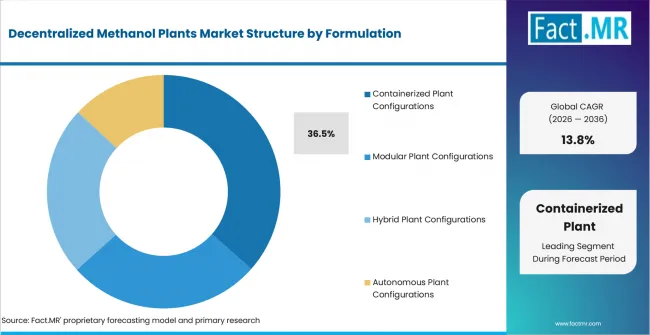
Decentralized Methanol Plants Market Analysis By Formulation | Source: Fact.MR
Containerized configurations lead because decentralization shifts project execution away from extensive site construction and toward repeatable factory-built modules. Equipment can be assembled and tested before shipment, reducing the amount of specialized work required at remote locations.
Modular Plant Solutions bases its methanol modules on the ISO 1496 container standard and designs the plant for remote operation. The purchasing logic is practical: owners can shorten field assembly, simplify transport planning and use a common structural format when expanding or relocating parts of the system.
Why do Direct Project Sales lead Distribution Channel?
Direct Project Sales are projected to account for a 72.4% share in 2026.
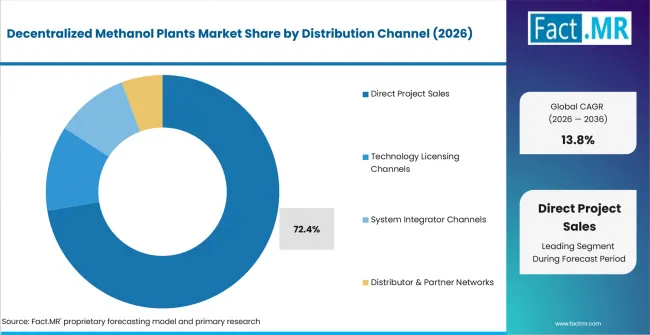
Decentralized Methanol Plants Market Analysis By Distribution Channel | Source: Fact.MR
Direct project sales lead because a methanol plant is purchased as an engineered asset rather than an off-the-shelf item. Feedstock composition, reformer design, synthesis-loop conditions, utilities and product specification must be aligned with the site and the intended customer.
thyssenkrupp Uhde describes its methanol offering as an integrated technology and EPC solution, while Air Liquide Engineering & Construction has supplied methanol process licences and engineering for project-specific plants. Direct contracting gives the owner a defined interface for performance guarantees and engineering responsibility.
What is accelerating Decentralized Methanol Plants Market adoption, and what is holding it back?
Adoption is being accelerated by localized feedstock monetization, methanol-fuel demand, carbon-utilization projects and modular plant execution. Growth can be restrained when small-scale economics are weakened by hydrogen or power costs, uncertain offtake, carbon-accounting requirements or competition from methanol supplied by centralized plants.
Drivers Impact Analysis
| Factor | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Localized feedstock monetization and regional methanol supply | +1.6% | Global | Short term (<= 2 years) |
| Marine-fuel demand and methanol-ready shipping | +1.4% | USA, UK, Germany and Japan | Short term (<= 2 years) |
| Low-emissions hydrogen and captured CO2 integration | +1.1% | USA, Germany and Canada | Medium term (2-4 years) |
| Containerized and modular plant execution | +0.9% | USA, Canada and remote industrial markets | Medium term (2-4 years) |
| Remote monitoring and lower staffing requirements | +0.6% | Global | Long term (>= 4 years) |
Opportunity Impact Analysis
| Factor | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| CO2-to-methanol plants at industrial sites | +1.0% | USA, Germany and Canada | Medium term (2-4 years) |
| Regional marine-fuel production near ports | +0.8% | USA, UK and Japan | Medium term (2-4 years) |
| Biomass and biogas-based distributed production | +0.7% | Canada, USA and Germany | Long term (>= 4 years) |
| Process licensing and pre-engineered plant packages | +0.5% | Global | Long term (>= 4 years) |
Restraints Impact Analysis
| Factor | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Capital and feedstock cost at smaller plant scale | -1.1% | Global | Short term (<= 2 years) |
| Low-emissions hydrogen availability and electricity cost | -0.9% | USA, UK, Germany and Japan | Short term (<= 2 years) |
| Carbon-source qualification and fuel certification | -0.7% | Germany, UK and Canada | Medium term (2-4 years) |
| Competition from centralized methanol and other low-carbon fuels | -0.5% | Global | Long term (>= 4 years) |
Which countries are scaling the Decentralized Methanol Plants Market through 2036?
- USA: The Gulf Coast Hydrogen Hub includes marine e-methanol among proposed clean-hydrogen applications. The region combines industrial carbon sources, natural gas infrastructure, ports and proposed low-emissions hydrogen supply, creating several possible feedstock combinations for distributed methanol projects.
- UK: The Maritime and Coastguard Agency has established a specific customer process for vessels considering methanol fuel, while clean-maritime programmes continue to support methanol among alternative-fuel pathways. Regulatory familiarity improves the visibility of port-linked methanol demand for project developers.
- Germany: Federal implementation rules now define how renewable electricity and hydrogen used in synthetic fuels can qualify under transport greenhouse-gas requirements. This gives e-methanol developers a clearer compliance framework when pairing carbon dioxide with renewable hydrogen.
- Japan: In February 2026, methanol was supplied ship-to-ship off Yokohama, including a portion of domestically produced biomethanol. This practical bunkering activity supports the development of local supply chains for methanol-fuelled vessels.
- Canada: Federal clean-fuel programmes explicitly include bio-methanol and synthetic methanol made from low-carbon hydrogen and carbon dioxide. Canada also has biomass, industrial carbon sources and renewable-power regions that can support site-specific production routes.
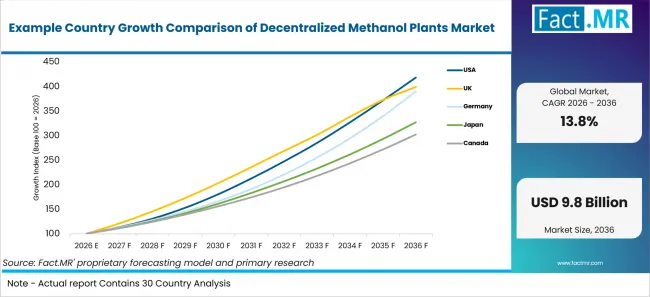
Example Country Growth Comparison Of Decentralized Methanol Plants Market | Source: Fact.MR
Country CAGR (2026-2036)
| Country | CAGR (2026-2036) |
|---|---|
| USA | 15.4% |
| UK | 14.9% |
| Germany | 14.6% |
| Japan | 12.6% |
| Canada | 11.7% |
What is driving USA’s growth through 2036?
The USA is forecast to expand at a 15.4% CAGR from 2026 to 2036.
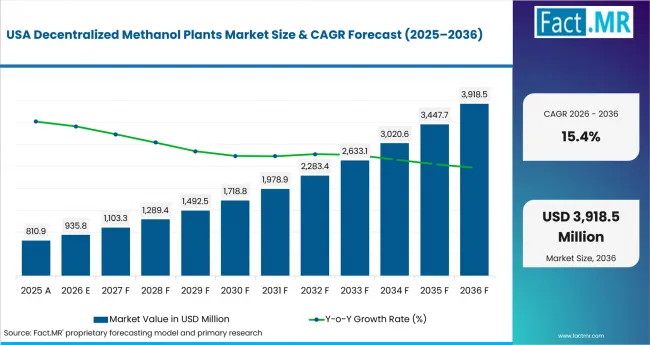
Decentralized Methanol Plants Market Country Value Analysis | Source: Fact.MR
Growth is supported by the ability to combine existing gas and chemical infrastructure with emerging clean-hydrogen and carbon-utilization projects. The Department of Energy selected the Star e-Methanol project on the Texas Gulf Coast for award negotiations; the project is designed to use captured carbon dioxide and clean hydrogen to produce up to 300,000 metric tons of e-methanol per year for hard-to-electrify transport applications.
This model is relevant to decentralization because production can be developed around a specific industrial carbon source, hydrogen supply and marine or chemical offtaker. Smaller regional plants can apply the same site-integration logic where feedstock volumes do not support a conventional centralized complex.
What is driving the UK’s growth through 2036?
The UK is forecast to expand at a 14.9% CAGR from 2026 to 2036.
Growth is tied to clean-maritime programmes and the development of practical approval pathways for alternative-fuel vessels. The UK Maritime Innovation Hub identifies methanol among the fuels for which vessel owners need guidance on safety, engineering, operations and emergency response.
For plant developers, this reduces uncertainty around the downstream use case. Port-linked methanol projects can be structured around shipping customers while chemical and industrial users provide additional offtake where local production is competitive with imported product.
What is driving Germany’s growth through 2036?
Germany is forecast to expand at a 14.6% CAGR from 2026 to 2036.
Germany is building technical experience with renewable methanol while formalizing the treatment of renewable hydrogen and synthetic fuels. The Leuna100 pilot plant uses synthesis gas made from carbon monoxide and green hydrogen to demonstrate a route to renewable methanol intended for shipping applications.
The Federal Environment Agency is also implementing rules that determine when electricity and hydrogen used for non-biogenic renewable fuels can qualify toward transport greenhouse-gas obligations. Together, demonstration capability and clearer certification rules improve the investment case for smaller CO2-to-methanol projects near industrial sites.
What is driving Japan’s growth through 2036?
Japan is forecast to expand at a 12.6% CAGR from 2026 to 2036.
Japan is developing methanol demand through vessel deployment and port-side fuel handling. A Ministry of Land, Infrastructure, Transport and Tourism roadmap states that methanol-fuelled domestic ships are expected to enter service and that wider bunkering experience can help build demand for methanol supply.
The same roadmap notes that stable methanol demand can strengthen the supply system and encourage production capacity. This creates room for regional projects connected to ports, biogenic carbon sources or imported and domestic hydrogen supply rather than relying only on centralized commodity imports.
What is driving Canada’s growth through 2036?
Canada is forecast to expand at an 11.7% CAGR from 2026 to 2036.
Canada is supporting both clean-fuel production and methanol-specific technology development. Natural Resources Canada lists synthetic methanol made from low-carbon hydrogen and carbon dioxide among eligible clean-fuel technologies, while a federal project in Alberta is scaling catalysts for e-methanol production from captured carbon dioxide and green hydrogen.
Biomass availability adds another route. Federal biomass programmes seek to improve access to forestry, agricultural and municipal residues, which can be converted to syngas before methanol synthesis. These distributed feedstocks fit projects that are designed around regional resource availability rather than a single national production hub.
Who Leads the Decentralized Methanol Plants Market?
Key players in the Decentralized Methanol Plants Market include thyssenkrupp Industrial Solutions, Modular Plant Solutions, Pyramid E&C, Carbon Recycling International, Enerkem, Haldor Topsoe, European Energy, ICODOS, Johnson Matthey, Casale SA, Air Liquide Engineering & Construction and Linde Engineering.
The methanol business associated with thyssenkrupp Industrial Solutions is currently marketed through thyssenkrupp Uhde. Its portfolio spans conventional and renewable feedstocks and includes engineering and EPC capability, which is relevant where plant owners want one provider to coordinate reforming, synthesis and project execution.
Modular Plant Solutions (MPS) offers the MeOH-To-Go modular plant with Topsoe process technology. Haldor Topsoe changed its company name to Topsoe in 2022, and Topsoe remains active in methanol technology and compact renewable-methanol development.
Carbon Recycling International, European Energy and ICODOS compete around carbon-utilization and e-methanol routes. Johnson Matthey, Casale, Air Liquide Engineering & Construction and Linde Engineering contribute methanol process technology, synthesis-gas engineering, catalysts or plant integration. Pyramid E&C focuses on modular reforming and methanol projects.
Enerkem Inc. entered proceedings under Canada’s Companies’ Creditors Arrangement Act in May 2025. Its current competitive position therefore differs from the other active technology and engineering providers profiled in the market.
Competition is shaped by feedstock flexibility, module size, catalyst and conversion efficiency, remote-operation capability and the ability to integrate electrolyzers or carbon capture. Project developers also assess performance guarantees and commissioning support because decentralized plants often operate with smaller site teams and tighter project economics.
Which companies are the key providers?
Key Companies includes thyssenkrupp Industrial Solutions; Modular Plant Solution; Pyramid E&C; Carbon Recycling International; Enerkem; Haldor Topsoe; European Energy; ICODOS; Johnson Matthey; Casale SA; Air Liquide Engineering & Construction; Linde Engineering
- thyssenkrupp Industrial Solutions
- Modular Plant Solution
- Pyramid E&C
- Carbon Recycling International
- Enerkem
- Haldor Topsoe
- European Energy
- ICODOS
- Johnson Matthey
- Casale SA
- Air Liquide Engineering & Construction
- Linde Engineering
Bibliography
- International Energy Agency. (2025). Global Hydrogen Review 2025. IEA.
- International Maritime Organization. (2026). Preparing Seafarers for the Energy Transition. IMO.
- International Maritime Organization. (2026). Maritime Alternative Fuel Regulatory Status. GreenVoyage2050.
- U.S. Department of Energy. (2026). Gulf Coast Hydrogen Hub. Office of Clean Energy Demonstrations.
- U.S. Department of Energy. (2024). Industrial Demonstrations Program Selections for Award Negotiations: Chemicals and Refining. Office of Clean Energy Demonstrations.
- UK Maritime and Coastguard Agency. (2025). MCA Customer Process for Alternative Fuels: Methanol. UK Government.
- UK Maritime and Coastguard Agency. (2026). Decarbonisation: Energy Efficiency and Alternative Fuels. UK Government.
- UK Department for Transport. (2025). Clean Maritime Demonstration Competition: Methanol and Other Alternative-Fuel Projects. UK Government.
- Federal Environment Agency, Germany. (2026). Implementation of the 37th Federal Immission Control Ordinance: Crediting Electricity-Based Fuels. Government of Germany.
- NOW GmbH. (2024). Launch of the Pilot Plant for the Cost-Efficient Production of Green Methanol at Leuna. Government-supported National Organisation Hydrogen and Fuel Cell Technology.
- Ministry of Land, Infrastructure, Transport and Tourism, Japan. (2026). Methanol Fuel Supplied Ship-to-Ship off Yokohama. Government of Japan.
- Ministry of Land, Infrastructure, Transport and Tourism, Japan. (2025). Roadmap for Methanol Bunkering Implementation. Government of Japan.
- Natural Resources Canada. (2026). Clean Fuels Fund. Government of Canada.
- Natural Resources Canada. (2026). Joint Evaluation and Audit of the Clean Fuels Fund Program. Government of Canada.
- Natural Resources Canada. (2025). Canadian Hydrogen Codes and Standards Roadmap. Government of Canada.
- Natural Resources Canada. (2024). Carbon-Negative Methanol and eFuels Production from Captured CO2 and Green Hydrogen. Government of Canada.
- UK Health Security Agency. (2024). Methanol: General Information. UK Government.
- thyssenkrupp Uhde. (2026). Methanol Plants.
- Pyramid E&C. (2026). Methanol Production Unit.
- Carbon Recycling International. (2026). Emissions-to-Liquids Technology and Renewable Methanol.
- Modular Plant Solutions. (2026). MeOH-To-Go Modular Methanol Plant.
- Topsoe. (2022). Haldor Topsoe Is Now Topsoe.
- European Energy. (2026). Operational and Strategic Progress for European Energy in First Quarter of 2026.
- ICODOS. (2026). E-Methanol Production Technology.
- Johnson Matthey. (2026). Methanol Process Technologies.
- Casale SA. (2026). Methanol Technologies.
- Air Liquide Engineering & Construction. (2021). Methanol Plant Technology and Engineering.
- Linde Engineering. (2026). Hydrogen and Synthesis Gas Plants.
- Innovation, Science and Economic Development Canada. (2025). CCAA Records: Enerkem Inc. Office of the Superintendent of Bankruptcy.
This Report Answers
- How feedstock availability and local offtake shape investment in decentralized methanol production.
- Why natural-gas routes continue to anchor current plant demand while carbon-utilization and renewable-hydrogen routes develop.
- Which plant configurations and technologies are used to reduce site-construction requirements and support remote operation.
- How marine fuel, chemical feedstock and industrial utility applications create different purchasing requirements.
- How current technology providers compete through process integration, modularization and project execution capability.
What does the Decentralized Methanol Plants Market cover?
The Decentralized Methanol Plants Market covers plant systems and integrated project solutions used to produce methanol at distributed, regional or site-specific locations within the supplied segment taxonomy. Counted commercial activity includes plant packages, process systems and project-level solutions associated with the covered product routes, technologies and configurations.
The assessment is focused on methanol-production assets rather than the downstream sale value of methanol itself. Projects may be designed around natural gas, biomass-derived syngas, captured carbon dioxide with hydrogen or renewable-hydrogen pathways, provided the revenue relates to the covered decentralized plant system.
What is included in the scope?
The scope includes Natural Gas Based Methanol Plants, Biomass Based Methanol Plants, CO2-to-Methanol Plants and Renewable Hydrogen Based Methanol Plants together with their supplied subsegments. It covers syngas conversion, carbon utilization, electrolysis and digital plant automation technologies when they are integrated into a decentralized methanol production project.
Application coverage includes fuel production, chemical feedstock, energy storage and industrial utility uses. Buyers include chemical manufacturers, energy and fuel companies, industrial processing companies, and utilities and infrastructure operators. Plant formats include containerized, modular, hybrid and autonomous configurations, while commercial routes follow the supplied direct sales, licensing, system-integrator and partner-network categories.
What is excluded from the scope?
The scope excludes the commodity value of methanol sold after production and methanol trading activity that does not include a plant-system sale. Centralized methanol facilities outside the decentralized plant definition are not counted simply because they use the same synthesis chemistry.
Standalone electrolyzers, hydrogen plants, carbon-capture systems, gasifiers, marine engines, bunkering terminals and methanol storage equipment are excluded when sold independently of a covered methanol plant project. Downstream formaldehyde, acetic acid, fuel-blending and chemical-processing facilities are also outside the market unless the revenue relates directly to the covered methanol-production system.
How Was the Analysis Built?
The analysis draws on more than 120 sources, over 35 company portfolios and more than 20 industry interviews across at least 25 countries.
- Primary Research: Interviews with methanol technology licensors, EPC contractors, modular-plant engineers, project developers, chemical producers, fuel suppliers and industrial buyers examine feedstock selection, plant sizing, project execution and offtake requirements.
- Desk Research: The review covers clean-fuel policy, marine-fuel regulation, hydrogen and carbon-utilization programmes, methanol technology portfolios, project disclosures and public research on synthetic-fuel production. External sources used in the article are recorded in the bibliography.
- Market Sizing and Forecasting: Estimates combine methanol-project activity with plant configuration, feedstock route, technology mix, application demand and country-level adoption. The model considers project size, modularization, process-licensing activity and the development of marine-fuel and low-carbon methanol offtake.
- Data Validation and Update Cycle: Findings are cross-checked against company activity, public project announcements and government programmes. Updates account for changes in hydrogen economics, carbon-utilization projects, methanol-fuel demand, company status and commercial plant deployment.
What is the report's scope and coverage?
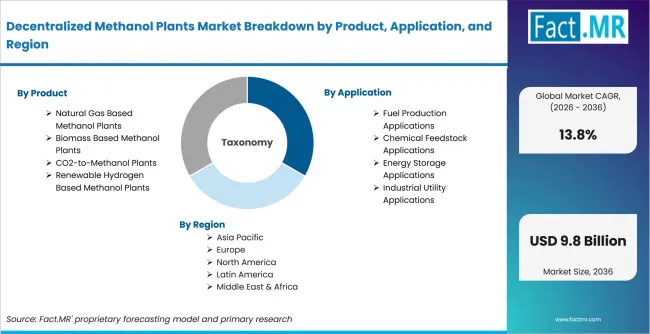
Decentralized Methanol Plants Market Breakdown By Product, Application, And Region | Source: Fact.MR
| Attribute | Details |
|---|---|
| Quantitative Units | USD billion |
| Market Definition | Decentralized methanol plant systems and integrated project solutions sold across the covered segments and applications |
| Segments Covered | Product; Application; End Use; Technology; Formulation; Distribution Channel |
| Regions Covered | North America; Latin America; Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA; UK; Germany; Japan; Canada |
| Key Companies Profiled | thyssenkrupp Industrial Solutions; Modular Plant Solution; Pyramid E&C; Carbon Recycling International; Enerkem; and others |
| Forecast Period | 2026 to 2036 |
| Base Year | 2026 |
| Market Value, 2026 | USD 2.7 billion |
| Market Value, 2036 | USD 9.8 billion |
| CAGR, 2026-2036 | 13.8% |
| Absolute Opportunity | USD 7.1 billion |
| Approach | Hybrid top-down and bottom-up approach using plant project activity, feedstock route, configuration, technology mix, application demand and country-level adoption |
How is the market segmented?
-
By Product:
- Natural Gas Based Methanol Plants
- Steam Reforming Systems
- Autothermal Reforming Systems
- Biomass Based Methanol Plants
- Gasification Systems
- Bio-Syngas Conversion Systems
- CO2-to-Methanol Plants
- Carbon Capture Integrated Systems
- Hydrogenation Systems
- Renewable Hydrogen Based Methanol Plants
- Electrolysis Integrated Systems
- Power-to-Methanol Systems
- Natural Gas Based Methanol Plants
-
By Application:
- Fuel Production Applications
- Marine Fuel Production
- Transportation Fuel Production
- Chemical Feedstock Applications
- Formaldehyde Production
- Acetic Acid Production
- Energy Storage Applications
- Hydrogen Carrier Systems
- Renewable Energy Storage
- Industrial Utility Applications
- Remote Industrial Fuel Supply
- Power Generation Applications
- Fuel Production Applications
-
By End Use:
- Chemical Manufacturing Companies
- Bulk Chemical Producers
- Specialty Chemical Producers
- Energy & Fuel Companies
- Fuel Distribution Companies
- Energy Production Companies
- Industrial Processing Companies
- Mining Companies
- Manufacturing Companies
- Utilities & Infrastructure Operators
- Power Utility Companies
- Infrastructure Service Providers
- Chemical Manufacturing Companies
-
By Technology:
- Syngas Conversion Technology
- Catalytic Conversion Systems
- Reactor Technologies
- Carbon Utilization Technology
- Carbon Capture Systems
- Carbon Conversion Systems
- Electrolysis Technology
- PEM Electrolysis Systems
- Alkaline Electrolysis Systems
- Digital Plant Automation Technology
- Remote Monitoring Systems
- Process Optimization Systems
- Syngas Conversion Technology
-
By Formulation:
- Containerized Plant Configurations
- Single Container Systems
- Multi Container Systems
- Modular Plant Configurations
- Skid Mounted Systems
- Expandable Modular Systems
- Hybrid Plant Configurations
- Renewable Integrated Systems
- Multi Feedstock Systems
- Autonomous Plant Configurations
- Unmanned Operation Systems
- Smart Plant Systems
- Containerized Plant Configurations
-
By Distribution Channel:
- Direct Project Sales
- EPC Contract Sales
- Owner Direct Contracts
- Technology Licensing Channels
- Process Licensing Agreements
- Engineering Licensing Services
- System Integrator Channels
- Industrial Integrators
- Energy Integrators
- Distributor & Partner Networks
- Regional Equipment Partners
- Strategic Alliance Networks
- Direct Project Sales
-
By Region:
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa

